Thursday, November 5, 2026 · 8:15 AM ET · Shahryar Rahmani, MTC Desk
Chips drag Nasdaq futures after Qualcomm and Arm reported. Qualcomm was down about 10% and Arm about 6% before the open (7:45 AM ET), and Nasdaq 100 futures were down about 0.7% to 0.9%. Dow futures were up about 0.5% after Wednesday’s 3% jump. Jobless claims are out at 8:30 AM ET.
Read the episode
Morning, I’m Shah, your host, and this is MTC Radio, premarket edition.
Okay, so the chip selling didn’t stop overnight. Qualcomm and Arm reported earnings, and as of about seven forty-five, Qualcomm is down about ten percent and Arm about six percent before the open. That’s pulling the Nasdaq futures lower, down somewhere around three quarters of a percent, while the Dow is still up about half a percent after that massive three percent day yesterday.
So on Qualcomm, basically, their phone chip business shrank. Handset revenue was down twenty-six percent, and they warned that costs are going up across the whole chip supply chain. Arm actually had a record quarter, but the outlook only matched what people expected.
Now, it’s the same rotation we saw yesterday. After the election, money is coming out of the chip makers and the data center names, and going into the big platforms. Amazon, Meta and Alphabet are all up more than one percent this morning. Outside of chips, AppLovin is up about twenty percent after a really strong quarter. Revenue grew fifty-five percent.
Overseas, the Bank of England raised rates this morning, for the first time since twenty twenty-three. They went to four percent.
As for Spy, it’s sitting about flat, right between our two zones. Up top we have the seven sixty-eight, seven sixty-nine zone, yesterday’s high. If we push into it, I want to see acceptance above it, not just a poke and a rejection. Down below, seven sixty-two and a half to seven sixty-four, that’s yesterday’s open and low. If we come down there, we’ll see if buyers step in and defend it.
Q Q Q is the weaker one. It’s sitting below the six eighty-eight, six ninety zone right now, and just above Tuesday’s close, so yesterday’s gap is nearly filled. If we reclaim six eighty-eight, six ninety and hold it, well, that’s the first sign of buyers coming back. However, if we keep rejecting under it, then the chip selling is still in charge, and I’m not interested in fighting that.
Okay, and then we have jobless claims at eight thirty, expected around a hundred ninety-six thousand. The Fed’s Hammack speaks at eight fifty, and Barkin at nine ten. After the close we have Airbnb and Lumentum. And tomorrow morning is the big one, the October jobs report at eight thirty.
So yeah, that’s what I’m watching. If you want to trade it with us, we’re live Monday, Tuesday, Thursday and Friday in the community. See you there.
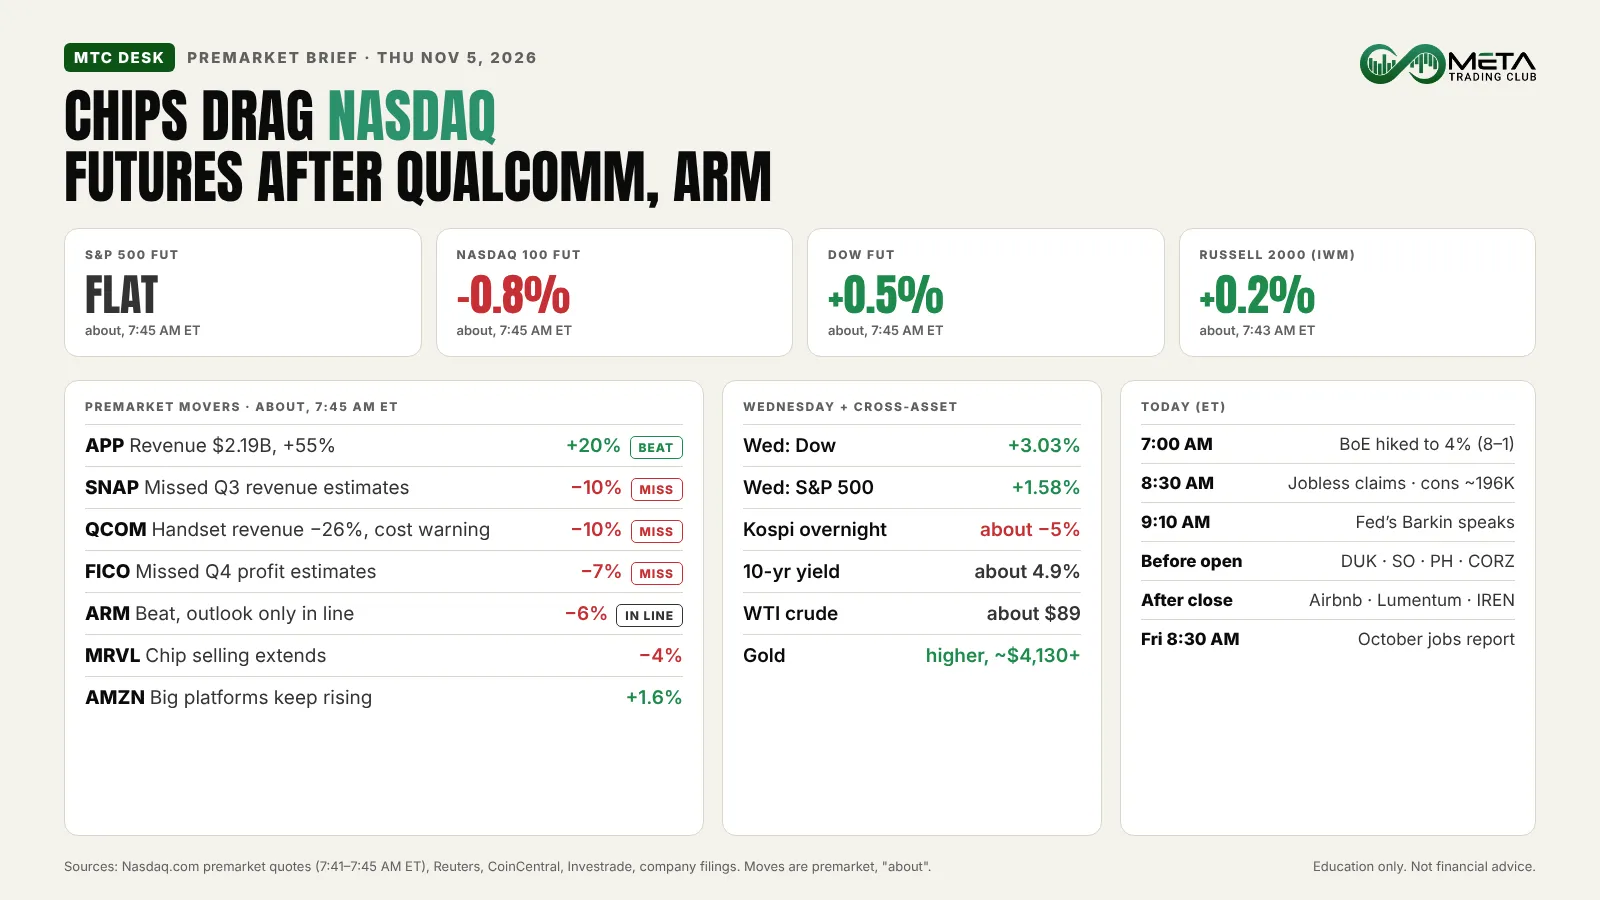
The rotation out of AI builders kept going overnight. Qualcomm’s handset chip revenue fell 26% and it warned of rising costs, and Arm beat but gave an outlook that only matched expectations (Reuters; CoinCentral). Chip stocks extended Wednesday’s losses: Marvell was about 4% lower and Nvidia about 1% to 1.5% lower.
The election is still in the mix. Chip and data center names have been under pressure since Democrats won Congress, including in key data center states where opposition to new sites is growing (Reuters; XTB). “Data center pauses will slow the pace of buildout into 2028,” UBS said, with about 30% of expected 2028 additions now at risk (Reuters).
The large platforms are going the other way. Amazon was about 1.6% higher and Meta and Alphabet about 1.2% higher, on the view that a slower AI buildout helps them (Reuters; Nasdaq.com). Overseas, the Bank of England raised rates to 4%, its first hike since 2023.
Market Snapshot: Chips Drag Nasdaq Futures
| Market | Move | Note |
|---|---|---|
| S&P 500 futures | about flat | About 7:45 AM ET |
| Nasdaq 100 futures | about −0.7% to −0.9% | Chips and data center names lower |
| Dow futures | about +0.5% | Building on Wednesday’s 3% jump |
| Russell 2000 (IWM) | about +0.2% | IWM at 7:43 AM ET (Nasdaq.com) |
| SPY premarket | 766.90 (about flat) | 7:43 AM ET; Wednesday close 766.81 |
| QQQ premarket | 685.79 (about −0.9%) | 7:42 AM ET; Wednesday close 691.95 |
On Wednesday the Dow jumped 3.03% to 53,356.12, its best day since April 2025 (XTB; Nexus Research). The S&P 500 rose 1.58% to 7,688.62, the Nasdaq 1.44% and the Russell 2000 1.58%. The full story is in our Wednesday close recap.
Top Premarket Stories
Moves are premarket, as of about 7:45 AM ET (Nasdaq.com).
Qualcomm (QCOM), about −10%. Fiscal fourth-quarter non-GAAP revenue was $10.44 billion and EPS $2.17. Handset chip revenue fell 26% to $5.14 billion, below the roughly $5.25 billion expected (per Nexus Research), and Qualcomm warned of rising input costs across the chip supply chain. It guided first-quarter revenue to $10.4–$11.2 billion and non-GAAP EPS to $2.15–$2.35, a midpoint below the roughly $2.27 expected (per Nexus Research; Qualcomm release; Reuters).
Arm Holdings (ARM), about −6%. Record September-quarter revenue of $1.44 billion, up 27%, with non-GAAP EPS of $0.52 and data center royalties doubling. The outlook was only roughly in line with expectations; Nexus Research puts the revenue guide at $1.54 billion, plus or minus $50 million (Arm shareholder letter; CoinCentral).
AppLovin (APP), about +20%. Third-quarter revenue rose 55% to $2.19 billion, ahead of the roughly $2.07 billion expected (per Nexus Research), and net income was $1.44 billion. It guided fourth-quarter revenue to $2.365–$2.395 billion and raised its buyback authorization by $3.2 billion (AppLovin release; Reuters).
Snap (SNAP), about −10%. Missed third-quarter revenue estimates (Reuters). Fair Isaac (FICO), about −7%. Missed fourth-quarter profit estimates (Reuters).
Chips and AI hardware are lower without company news: Marvell (MRVL), about −4%, Dell (DELL), about −3% to −5% and Nvidia (NVDA), about −1% to −1.5% (Reuters; Nasdaq.com).
Sectors
The split from Wednesday is still there. Semiconductors and AI infrastructure are the weak spot, while the large platforms (Amazon, Meta, Alphabet) and the Dow hold up. Overnight in Asia, South Korea’s Kospi fell about 5% on chip selling and Japan’s Nikkei about 1.8%, while Hong Kong’s Hang Seng rose about 3.5%.
Rates and Commodities
| Asset | Early Thursday | One line |
|---|---|---|
| 10-year yield | about 4.9% | About flat |
| WTI crude | about $89 | Small bounce after Wednesday’s 8% drop |
| Brent crude | about $96 | Up about 1% |
| Gold | about $4,130–$4,150 | Higher |
Oil fell sharply Wednesday on hopes of a U.S.-Iran deal after Vice President Vance blamed the war for Republican losses (XTB; CoinCentral). Reports of tanker fires in the Strait of Hormuz are unconfirmed.
Economic Data Today
| Time (ET) | Release | Consensus | Prior | Actual |
|---|---|---|---|---|
| 7:00 AM | Bank of England Rate Decision (Nov) | +25 bp to 4% | 3.75% | 4% (8–1 vote) |
| 8:30 AM | Initial Jobless Claims (week ended Oct 31) | about 196K | — | — |
| 8:30 AM | Nonfarm Productivity (Q3, prelim) | +0.6% | +1.2% | — |
| 8:30 AM | Unit Labor Costs (Q3, prelim) | +2.8% | +1.4% | — |
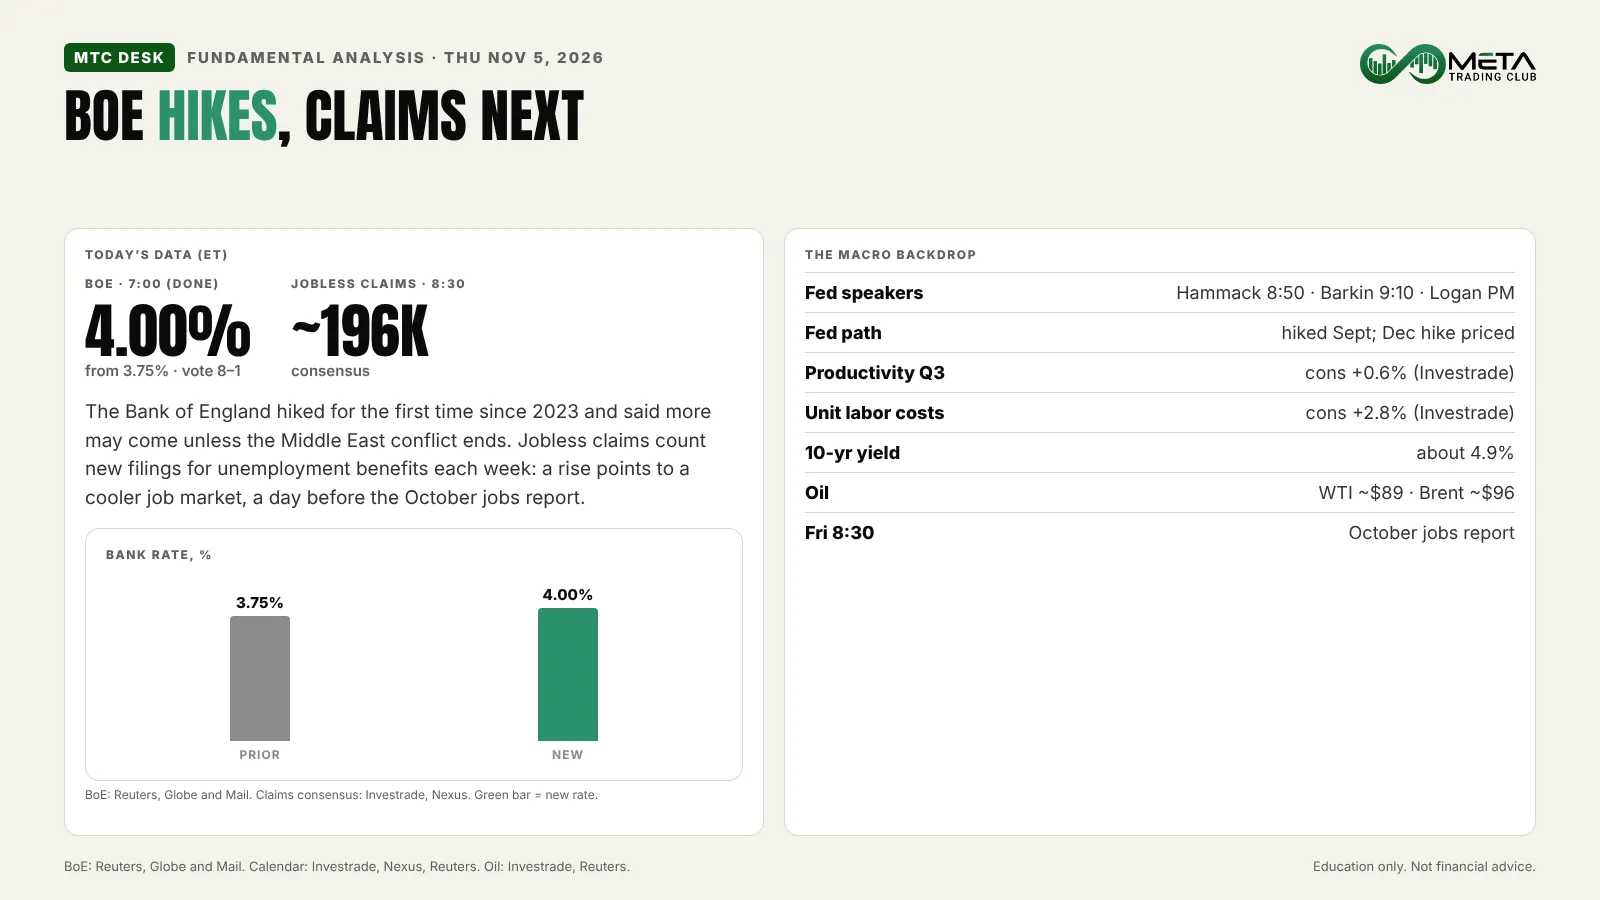
Jobless claims count new filings for unemployment benefits; consensus is about 196,000 (Investrade; Nexus Research). Productivity and unit labor cost estimates are from Investrade’s calendar. It’s the last labor check before Friday’s October jobs report at 8:30 AM.
The Bank of England raised rates by a quarter point to 4% from 3.75% on an 8–1 vote; Catherine Mann wanted a half point. Governor Bailey said more may come unless the Middle East conflict is resolved (Reuters; The Globe and Mail). At home, at least three Fed officials speak today: Cleveland’s Hammack at 8:50 AM, Richmond’s Barkin at 9:10 AM and Dallas’s Logan this evening (Reuters; Nexus Research). The Fed hiked in September, and markets price another hike in December (Reuters).
Earnings
Before the open: Duke Energy, Southern Company, Parker-Hannifin, Core Scientific and MACOM.
After the close: Airbnb, Lumentum, Atlassian, Microchip, Akamai, Affirm, IonQ and IREN.
What to Watch Next
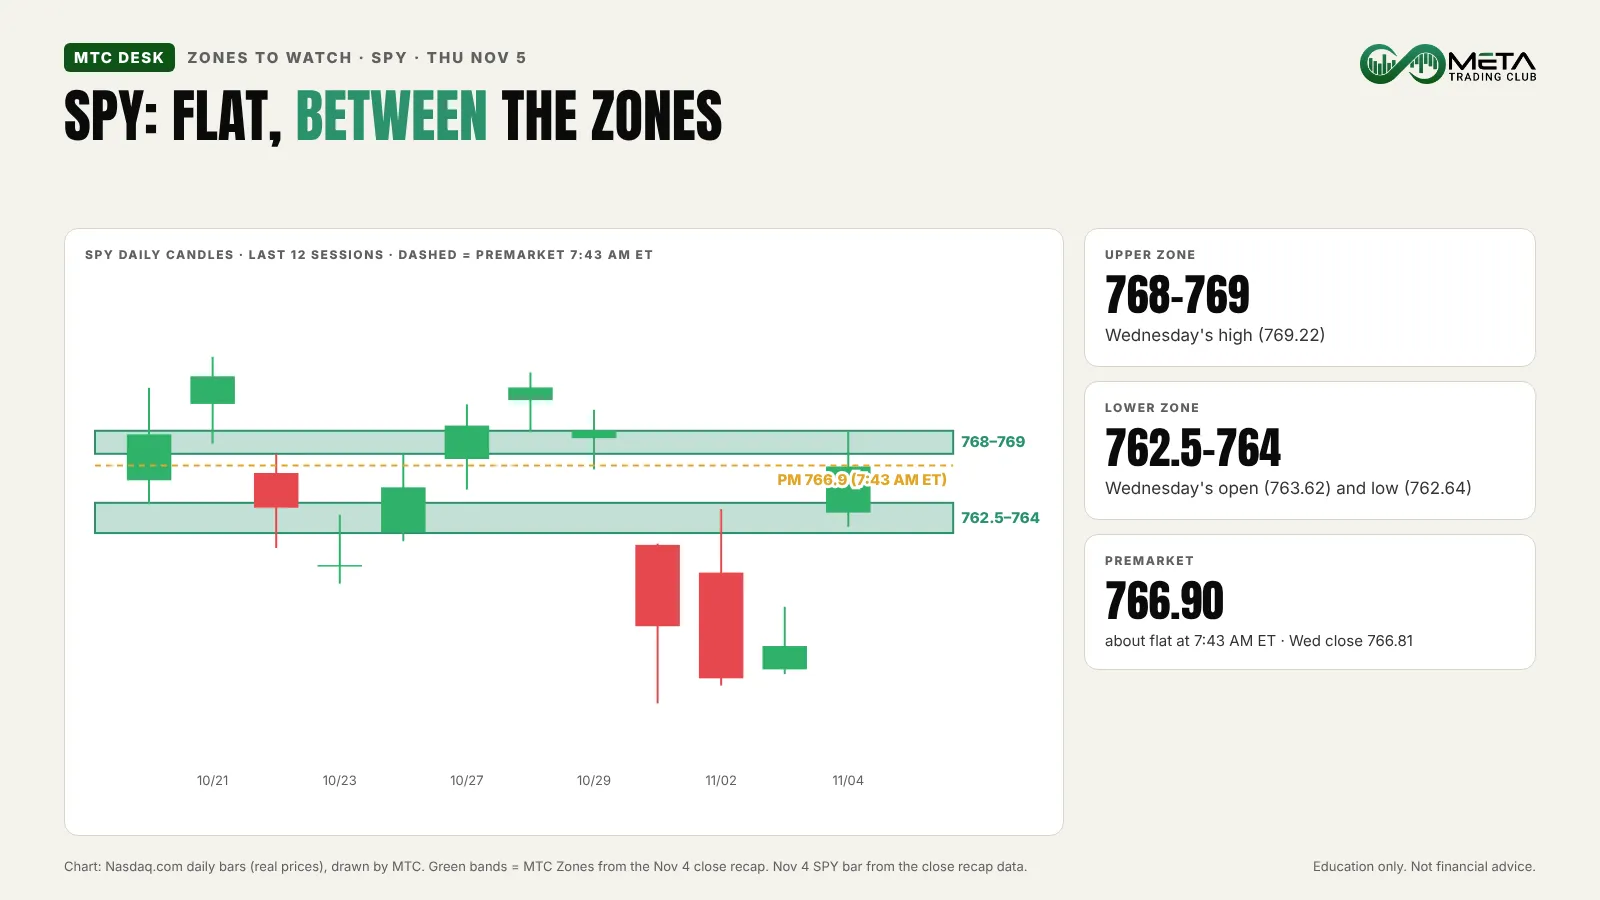
SPY is about flat at 766.9, between its two Zones. 768–769 is Wednesday’s high: a push there needs acceptance, not a poke. 762.5–764 is Wednesday’s open and low, where we’d watch for buyers to defend Wednesday’s gap.
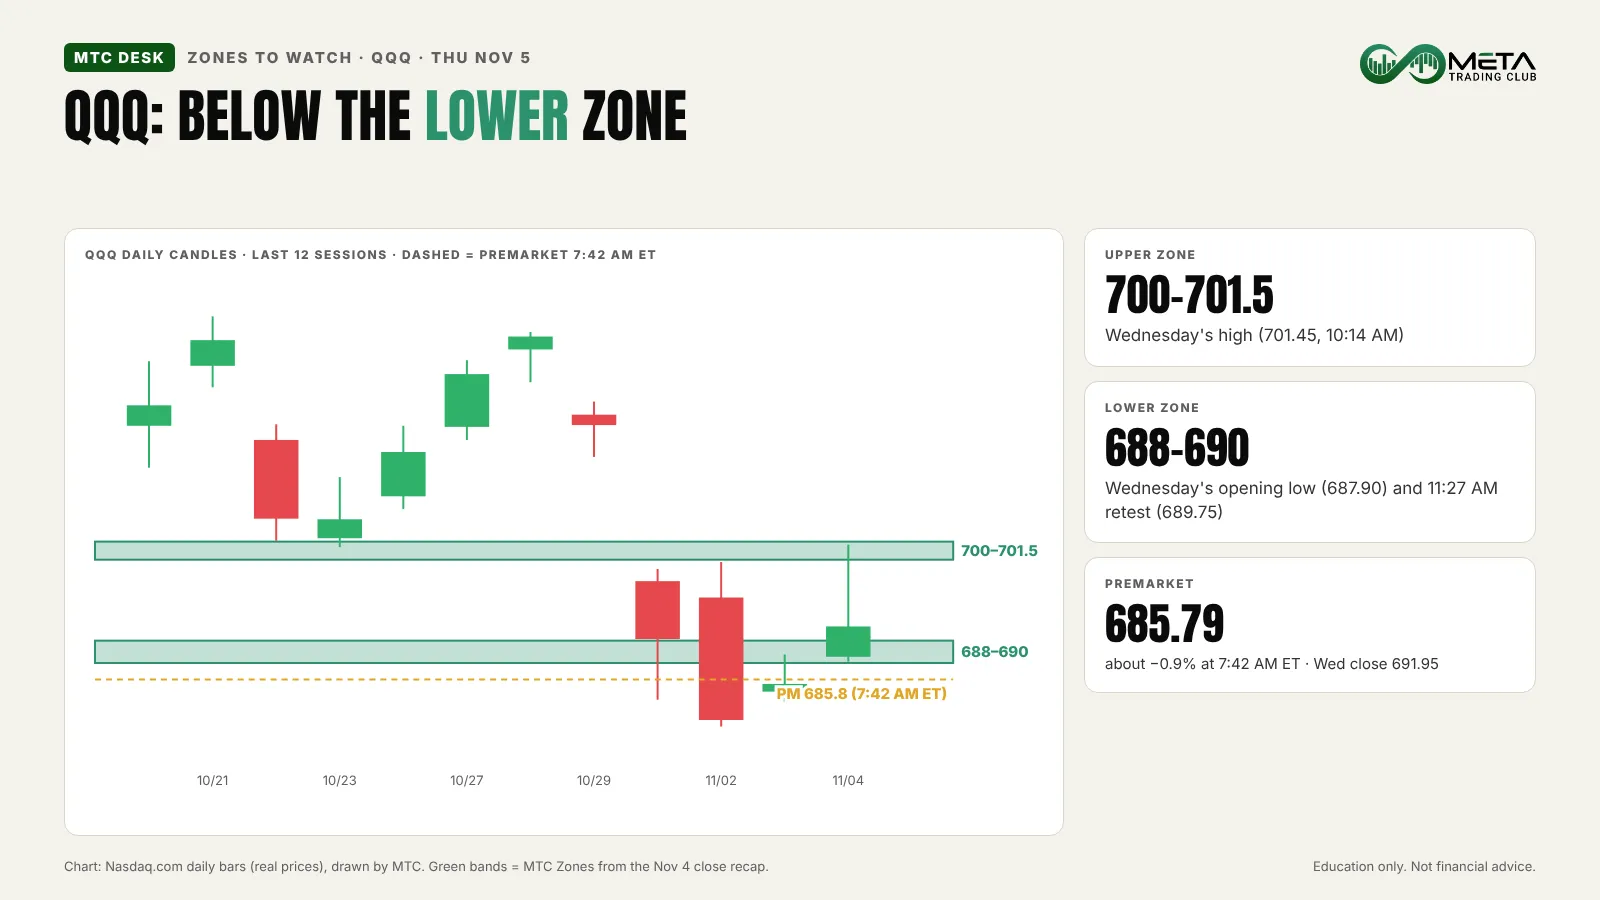
QQQ is about 685.8, below its 688–690 Zone (Wednesday’s opening low and retest) and just above Tuesday’s 685.28 close, so Wednesday’s gap is nearly filled. A reclaim of 688–690 would be the first sign of buyers; a rejection under it keeps the chip selling in charge. The upper Zone is 700–701.5, Wednesday’s high. Our guide to using premarket data to prepare for the day shows how we turn these numbers into a plan, and yesterday’s premarket brief has the election-day setup. The latest brief always lives on our stock market today page.
Risks: jobless claims at 8:30, Fed speakers at 8:50 and 9:10, Airbnb and the Airbnb, Lumentum and IREN tonight, and the October jobs report Friday at 8:30 AM. No alignment, no trade.
FAQ
Chip stocks are falling after Qualcomm and Arm reported. Qualcomm was down about 10% and Arm about 6% before the open (7:45 AM ET). Nasdaq 100 futures were down about 0.7% to 0.9%, while S&P 500 futures were about flat and Dow futures up about 0.5%.
Qualcomm’s handset chip revenue fell 26% to $5.14 billion in its fiscal fourth quarter, and it warned of rising input costs across the chip supply chain. Its first-quarter EPS guide of $2.15 to $2.35 has a midpoint below the roughly $2.27 expected, per Nexus Research.
Weekly initial jobless claims are out at 8:30 AM ET, with consensus about 196,000. Third-quarter productivity and unit labor costs also come out at 8:30 AM ET. The Bank of England raised rates to 4% at 7:00 AM ET, and the Fed’s Hammack (8:50 AM) and Barkin (9:10 AM) speak this morning.
On SPY, the upper Zone is 768 to 769 (Wednesday’s high) and the lower Zone is 762.5 to 764 (Wednesday’s open and low). On QQQ, the Zones are 700 to 701.5 and 688 to 690; QQQ was about 685.8 before the open, below the lower Zone. These are places to watch for a reaction, not entries.
Sources: Nasdaq.com premarket quotes (7:40–7:45 AM ET); Qualcomm release (SEC 8-K); Arm shareholder letter (SEC 6-K); AppLovin release (SEC 8-K); Reuters; CoinCentral; XTB; Investrade; Nexus Research; The Globe and Mail. Featured image: AI-edited from the Qualcomm logo (Wikimedia Commons file Qualcomm-Logo.svg). Premarket moves are approximate and change before the open.
Education only. Not financial advice.