Wednesday, November 4, 2026 · 5:30 PM ET · Shahryar Rahmani, MTC Desk
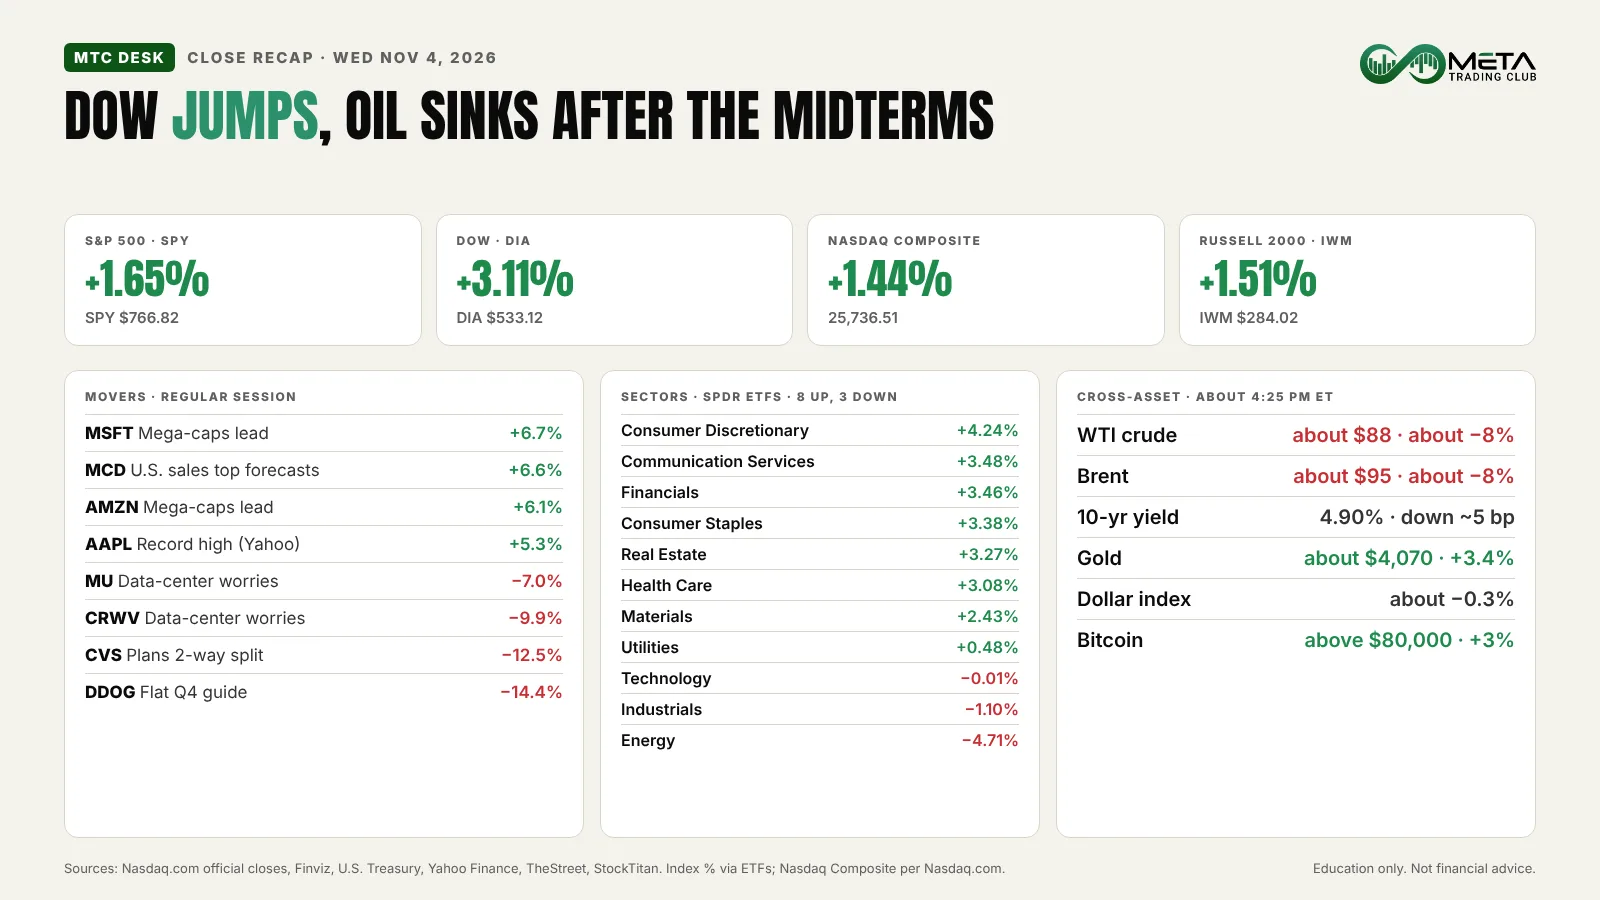
The Dow jumps about 3% the day after the midterms: Democrats won control of both the House and the Senate, and investors cheered a split government. The S&P 500 rose about 1.7% (SPY +1.65%), the Nasdaq Composite gained 1.44% (Nasdaq.com), and oil sank about 8% on hopes for an end to the Iran war.
Read the episode
Hey, I’m Shah, your host, and this is MTC Radio.
Okay, so today was a big up day, and it was all about the election. Democrats won control of both the House and the Senate. Overnight, futures dropped hard on that. Then they flipped, and by the close the Dow was up about three percent. The S&P 500 was up about one point seven, and the Nasdaq about one and a half.
Basically, the market liked that Washington is now split. Democrats run Congress, Trump is in the White House, and strategists were saying markets have historically liked that kind of gridlock. Fewer big surprises from Washington. And the money went into the big names. Microsoft was up almost seven percent, Amazon about six, Apple about five. Yahoo Finance said Apple and Microsoft both hit record highs today.
Now, the other massive move was oil. Oil fell about eight percent. W T I is around eighty eight dollars, Brent around ninety five. Traders are betting the election makes an end to the Iran war more likely. As a result, energy was the worst sector by far, down almost five percent.
But not everything was green. The data center trade got hit. In Texas, the new governor-elect has said she wants to pause new data centers, and investors are worried the new Congress will put more scrutiny on that whole build-out. CoreWeave fell about ten percent, Micron about seven, and Nvidia about three. So tech as a sector finished basically flat, even with Apple and Microsoft at records.
On the earnings side, Datadog is a really good lesson. Strong quarter, revenue up thirty five percent, beat on earnings. But they guided next quarter about flat, and the stock fell about fourteen percent. So it was all about the guidance. CVS fell about twelve and a half percent after it said it plans to split into two companies. And McDonald’s went up about six and a half percent, because U.S. sales fell less than people feared.
Okay, and then ADP said private companies added about eighty six thousand jobs, a bit better than expected. And ISM Services came in at fifty four and a half, a little under what people wanted, but still growing. The ten-year yield slipped to about four point nine percent.
Now, as for our Zones, this morning we had Q Q Q at six eighty eight, six eighty nine. It opened right above it, dipped into that Zone in the first few minutes, held, and ran all the way to about seven oh one. Then after ten we got the retest we were waiting for, at about six eighty nine seventy five, it held again and bounced. That was a pretty clear situation, the reaction and the confirmation both showed up. On Spy, the seven fifty six Zone never came into play. It gapped way above it and never looked back. So no setup there, and that’s fine.
One thing I noticed, the Q Q Q gave back a lot of the morning move. It topped out around ten fifteen and closed around six ninety two. So tech is still a bit shaky under the surface.
For tomorrow, on Spy I’m watching seven sixty eight, seven sixty nine, that’s today’s high, and seven sixty two and a half to seven sixty four below, that’s where we opened. On Q Q Q, seven hundred to seven oh one and a half above, and six eighty eight to six ninety below. If we hold above those lower Zones, well, the trend is still up. However, if we lose them, there is a possibility we start working on that gap from yesterday.
We also have the Bank of England at seven in the morning and jobless claims at eight thirty. Friday is the jobs report. And after the bell today, AppLovin, Qualcomm, Arm and Snap all reported, with some big moves, so watch how those open.
So yeah, that’s what I’m watching. If you want to trade it with us, we’re live Monday, Tuesday, Thursday and Friday in the community. See you there.
Strategists said markets tend to like gridlock, because it makes big policy swings less likely (Morgan Stanley Investment Management’s Andrew Slimmon and Freedom Capital Markets’ Jay Woods, via StockTitan; TheStreet). Overnight, S&P 500 futures had first dropped about 1.2% around midnight ET before they flipped higher.
Mega-caps carried the day. Microsoft rose 6.68%, Amazon 6.12% and Apple 5.31%, and Yahoo Finance said Apple and Microsoft both hit record highs. Eight of 11 sectors finished green.
The AI build-out trade went the other way. CoreWeave fell 9.90% and Micron 7.00% on worries that the new Congress and new state officials could slow data-center building.
The Closing Bell
S&P 500 and Dow moves are shown through their ETFs (official 4:00 PM ET closes, Nasdaq.com and Finviz). Nasdaq index levels are from Nasdaq.com.
| Index | Close | Change | Note |
|---|---|---|---|
| S&P 500 (SPY) | $766.82 | +1.65% | About +1.7% for the index |
| Dow Jones (DIA) | $533.12 | +3.11% | About +3%; banks and big platforms led |
| Nasdaq Composite | 25,736.51 | +1.44% | Was up about 2% early afternoon |
| Nasdaq 100 | 28,437.17 | +0.91% | Chips held it back |
| Russell 2000 (IWM) | $284.02 | +1.51% | Small caps joined the rally |
What Drove The Day: Why the Dow Jumps
The midterm result. Democrats took both chambers of Congress, a divided government with President Trump. Futures fell hard overnight, then turned higher before the open, and the cash session built on that move. The Dow traded above 53,000 for the first time since September 8 (CNBC via StockTitan).
Oil’s plunge. WTI fell to about $88 and Brent to about $95, both down about 8% as of about 4:25 PM ET (Finviz; Yahoo Finance). Traders bet the election raises the odds of an end to the Iran war (Yahoo Finance; TheStreet). Brent traded below $100 for the first time in weeks (TheStreet).
Data-center worries. In Texas, Democrat Gina Hinojosa, who has pledged to pause new data-center construction, won the governor’s race (Yahoo Finance; StockTitan). AI infrastructure names fell: CoreWeave −9.90%, Micron −7.00%, Nvidia −3.17%. Tesla lost 3.34% on worries about more scrutiny of Elon Musk’s companies.
Datadog (DDOG) −14.42%. Q3 revenue rose 35% to $1.20 billion against about $1.14 billion expected, and non-GAAP EPS of $0.81 beat about $0.64. But the Q4 revenue guide of $1.19–$1.20 billion is about flat with Q3, and that is what the stock traded on (Datadog release; StockStory).
CVS Health (CVS) −12.54% after it announced a plan to split into two companies (Yahoo Finance; TheStreet). It also raised its 2026 adjusted EPS outlook to at least $8.20 (StockTitan).
McDonald’s (MCD) +6.58%. U.S. same-store sales fell 0.2%, better than the about −0.5% expected (Yahoo Finance; TheStreet, citing AP), and global same-store sales rose 1.5%. Novo Nordisk rose 4.93% after a beat-and-raise (CoinCentral; Reuters), and Uber gained 4.91%.
Sectors: Shoppers and Banks Lead, Energy Sinks
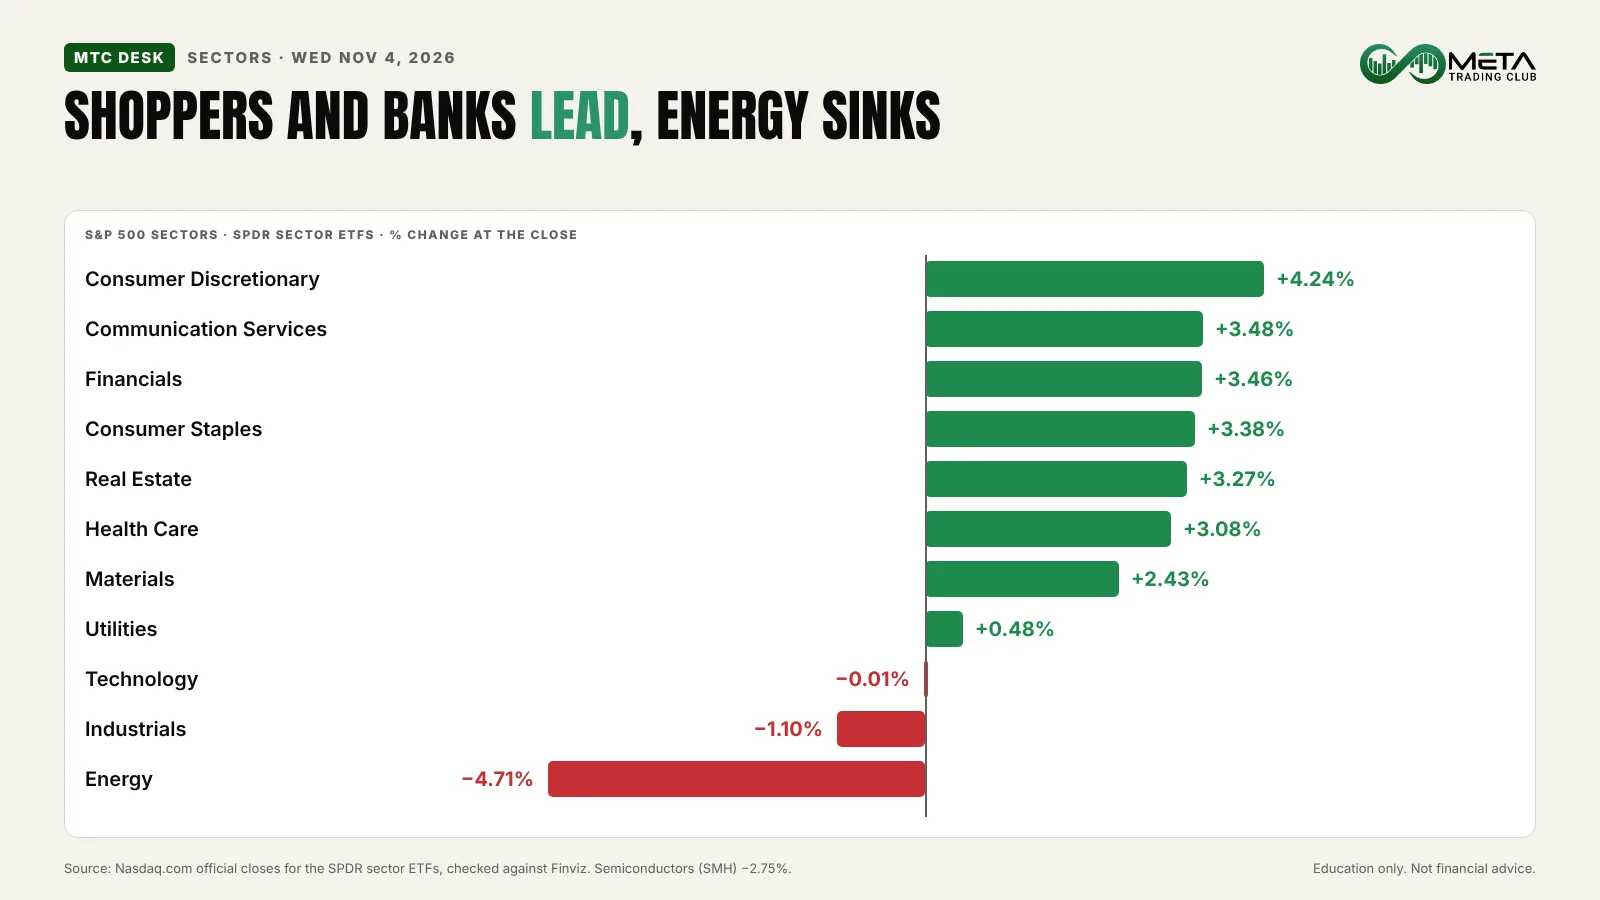
Consumer Discretionary led at +4.24%, followed by Communication Services (+3.48%), Financials (+3.46%), Consumer Staples (+3.38%), Real Estate (+3.27%), Health Care (+3.08%), Materials (+2.43%) and Utilities (+0.48%). Technology was flat (−0.01%) as record highs in Apple and Microsoft offset the chip sell-off (SMH −2.75%). Industrials fell 1.10% and Energy lost 4.71% with oil. The rotation in one line: money moved into shoppers, banks and big platforms and out of oil and the AI build-out. Our guide to bull vs bear markets explains why breadth matters as much as the index.
Rates, Dollar and Commodities
| Asset | Level | One line |
|---|---|---|
| 10-year Treasury yield | 4.90% | Down about 5 basis points (U.S. Treasury) |
| WTI crude | about $88 (about −8%) | Back under $90 on Iran-war hopes |
| Brent crude | about $95 (about −8%) | Below $100 for the first time in weeks |
| Gold | about $4,070 (+3.4%) | Up about 3.4% |
| Dollar index | about −0.3% | Slightly weaker |
| Bitcoin | above $80,000 (+3%) | Back above $80,000 |
Economic Data Today
| Time (ET) | Release | Consensus | Prior | Actual |
|---|---|---|---|---|
| 8:15 AM | ADP National Employment Report (Oct) | +67K to +75K | +90K (as first reported) | +86K |
| 10:00 AM | ISM Services PMI (Oct) | 54.8 | 54.9 | 54.5 |
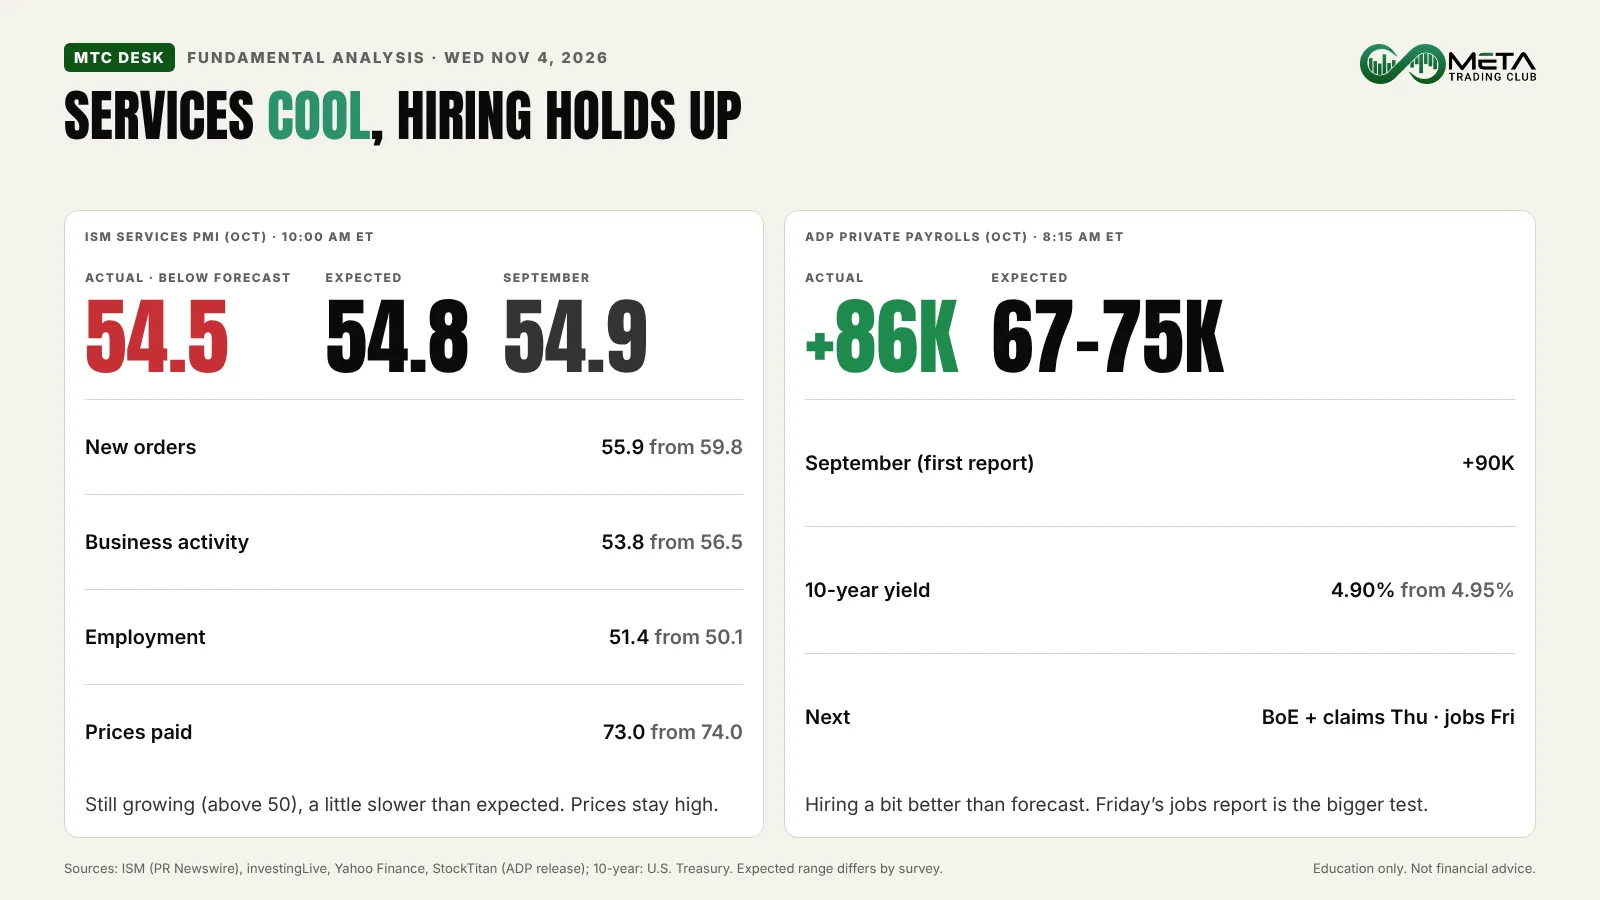
ADP private payrolls rose 86,000 in October, above the roughly 67,000–75,000 expected (Yahoo Finance; StockTitan, citing the ADP release). Hiring is slow but steady, not cracking.
The ISM Services PMI came in at 54.5 against 54.8 expected and 54.9 in September (ISM via PR Newswire; investingLive). Above 50 means services are still growing. New orders cooled to 55.9 from 59.8, and prices paid stayed high at 73.0. See how inflation reports move the stock market for why that prices number matters.
Earnings After the Close
AppLovin, Qualcomm, Arm and Snap reported after the bell, and McKesson was also scheduled for the evening. At about 4:22 PM ET, AppLovin was about 18% higher, Qualcomm about 6% lower, Arm about 4% lower and Snap about 10% lower (Nasdaq.com; Finviz). We could not confirm the release numbers from two sources by publish time, so the full breakdown comes in tomorrow’s coverage.
What to Watch Next
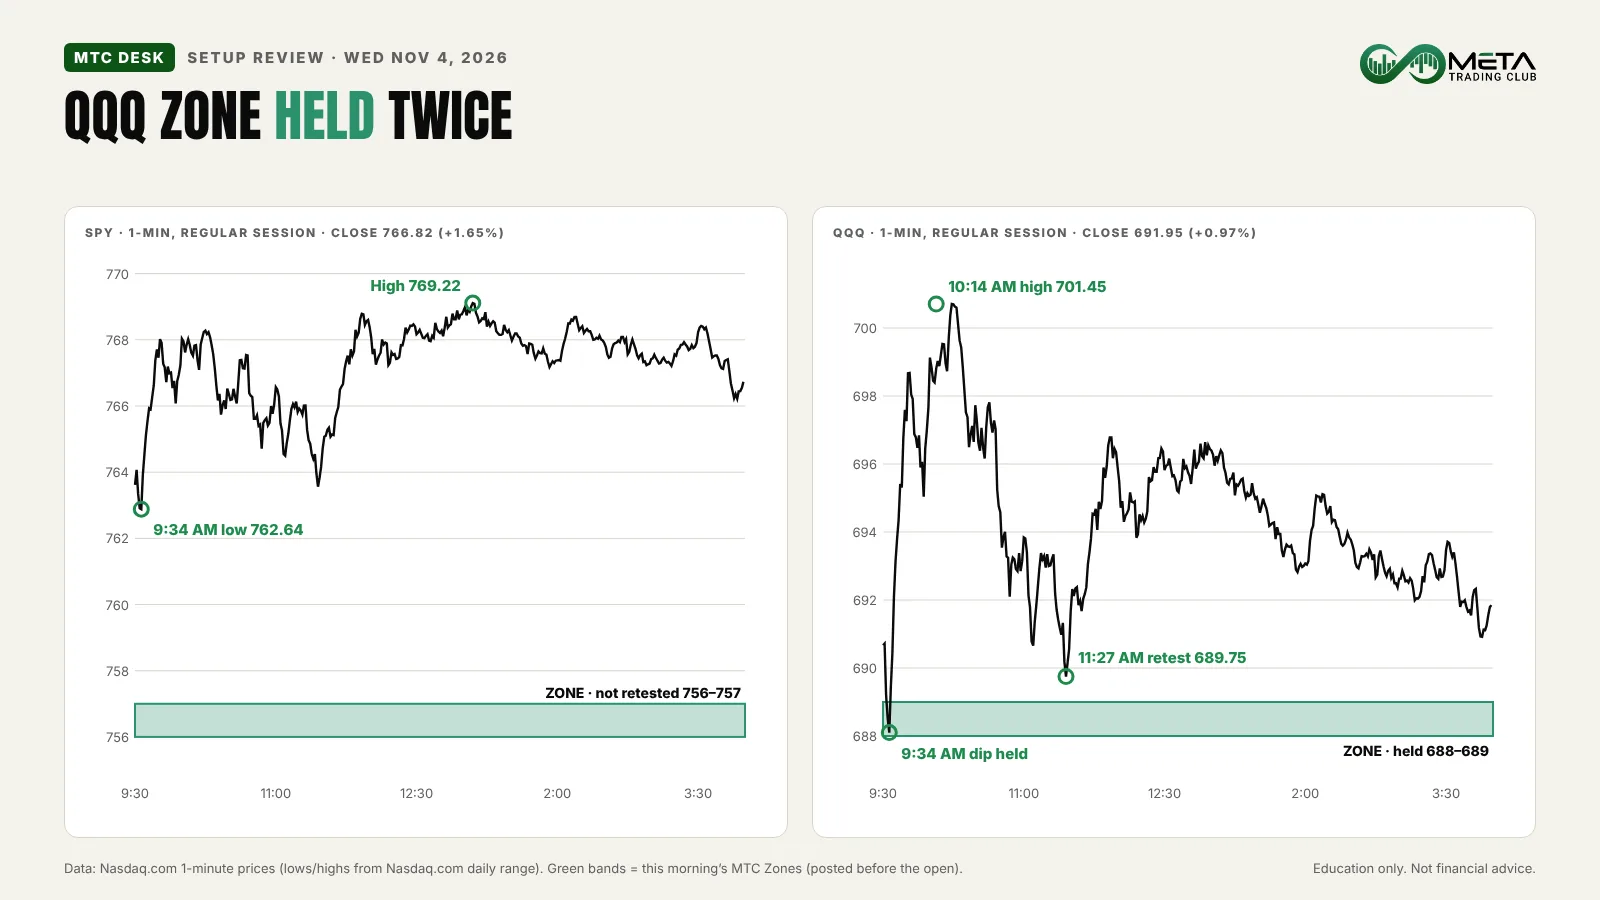
Per Nasdaq.com 1-minute data, this morning’s premarket brief flagged QQQ 688–689 and SPY 756–757. QQQ dipped to 687.90 at 9:34 AM ET, held, and ran to 701.45 by 10:14 AM ET; its 11:27 AM ET retest held at 689.75. SPY opened at 763.62 and never came back to its Zone. Yesterday’s close recap has how these Zones were set.
For Thursday, the Zones to watch for a reaction are SPY 768–769 (today’s high) and 762.5–764 (today’s open and low), and QQQ 700–701.5 and 688–690. Our guide to using premarket data to prepare for the day shows how we build these levels.
Calendar (ET): the Bank of England at 7:00 AM and jobless claims at 8:30 AM Thursday, then the October jobs report at 8:30 AM Friday. Risks: the after-hours reports from Qualcomm, Arm and AppLovin, oil headlines on Iran, and whether tech holds after giving back its morning pop. No alignment, no trade.
FAQ
Democrats won control of both the House and the Senate, which leaves Washington split with President Trump. Strategists said markets have historically liked that kind of gridlock. The Dow rose about 3% (the DIA ETF closed up 3.11%), led by big moves in Microsoft, Amazon, Apple and JPMorgan.
Traders bet the election raises the odds of an end to the Iran war. WTI crude fell to about $88 and Brent to about $95, both down about 8% as of about 4:25 PM ET, and the energy sector lost 4.71%.
Investors worried that a Democratic Congress and new state officials could slow data-center building. In Texas, Gina Hinojosa, who has pledged to pause new data centers, won the governor’s race. CoreWeave fell 9.90%, Micron 7.00% and Nvidia 3.17%.
The ISM Services PMI came in at 54.5 for October, a little below the 54.8 expected and down from 54.9. Anything above 50 means services are still growing. New orders cooled to 55.9 from 59.8.
Sources: Nasdaq.com official closes, index levels, after-hours quotes and 1-minute prices; Finviz quotes and futures; U.S. Treasury daily yield curve; Yahoo Finance; TheStreet; StockTitan (CNBC data); ISM via PR Newswire; investingLive; Datadog release; StockStory; CoinCentral; Reuters via Investing.com. After-hours and futures moves are approximate and carry their time. Featured image: AI-edited from a U.S. Capitol photo (Architect of the Capitol, public domain).
Education only. Not financial advice.