Tuesday, November 3, 2026 · 7:55 AM ET · Shahryar Rahmani, MTC Desk
Apple slips about 4% before the open (7:45 AM ET) after warning that memory costs will squeeze its holiday-quarter margin, and S&P 500 futures are about flat as voters head to the polls. The day brings JOLTS at 10:00 AM; AMD and the midterm results land after the close.
Read the episode
Morning, I’m Shah, your host, and this is MTC Radio, premarket edition.
So here’s the morning in one line: Apple had a great quarter, and the stock is still down, on election day.
Let’s start with Apple. Sales came in around one hundred fourteen and a half billion dollars, up twelve percent, and earnings beat too. But Apple said memory chips keep getting more expensive, and that’s going to squeeze its profit margin over the holidays. As of about seven forty-five, the stock is down about four percent before the open. Here’s the thing: a beat isn’t enough when the outlook gets weaker.
Now, the three things that matter today.
One, it’s election day. The midterms are on, and results come in after the close. So the real reaction is probably tomorrow morning, not today.
Two, job openings data at ten o’clock. The market expects about seven point one million. It’s a warm-up for Friday’s jobs report.
Three, AMD reports tonight. It fell hard yesterday with the rest of the chip stocks, and chips are bouncing a little this morning.
Futures? Pretty much flat for the S&P 500, the Nasdaq a touch higher, and the Dow a bit lower.
So what am I watching? On SPY, the Zone around seven fifty to seven fifty-two. That’s Friday’s low and yesterday’s close, and premarket is sitting right on it. If price tests it and pushes back up, with a higher low on the five-minute chart, that’s interesting. If it breaks clean and can’t get back above, the pullback probably isn’t done. Above us, the Zone around seven sixty-one to seven sixty-four is where yesterday’s bounce failed. A quick poke up there doesn’t count. I’d want price to hold above it.
On the Nasdaq side, QQQ is right back at Friday’s low, which broke yesterday. Do sellers defend it, or does price reclaim it? And I want SPY and QQQ to agree before I trust anything.
Calendar, all Eastern: job openings and factory orders at ten. Then AMD and the election results after the close.
Nothing before ten for me. Let the number land, let it settle, then see how price reacts at the Zones.
See you at the open. We trade live four days a week, Monday, Tuesday, Thursday and Friday. This is education, not financial advice. No alignment, no trade.
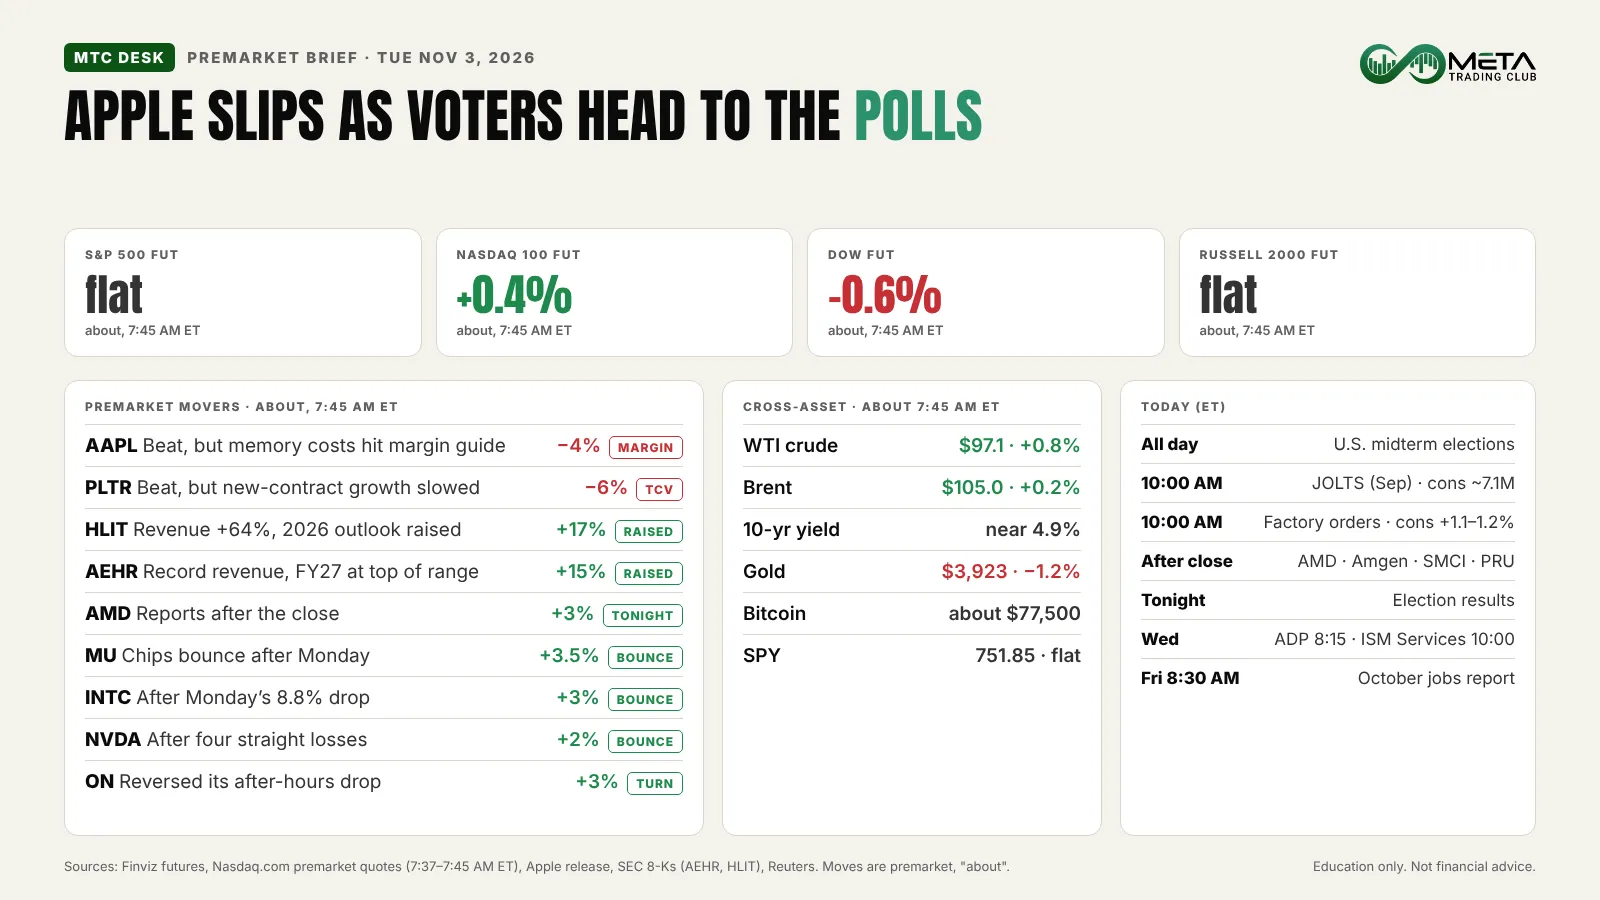
S&P 500 futures were about flat at 7:45 AM ET, Nasdaq 100 futures were up about 0.4% and Dow futures were down about 0.6%, with Apple, a Dow member, lower. On Monday the S&P 500 fell 0.51% as a tech and chip sell-off (technology −2.94%) outweighed gains in eight of 11 sectors.
Apple is the story of the morning. Its September-quarter revenue of $114.5 billion was a record and beat estimates, but it guided December-quarter gross margin to 45%–46%, below the 47.9% it just reported, and CEO John Ternus said it expects “even higher memory costs.”
It is also election day. All 435 House seats and 35 Senate seats are on the ballot, and results arrive after the close. That puts tonight’s results and AMD earnings ahead of Wednesday’s open, so overnight gap risk is higher than usual.
Oil is back up after Monday’s 7%+ drop, on a reported U.S. strike on Iran’s Qeshm Island. Our guide to using premarket data to prepare for the day shows how we turn these numbers into a plan.
Market Snapshot
| Market | Level / move | Note |
|---|---|---|
| S&P 500 futures | about flat | 7:45 AM ET; Monday cash close 7,541.40 (−0.51%) |
| Nasdaq 100 futures | about +0.4% | Chips bounce after Monday’s sell-off |
| Dow futures | about −0.6% | Apple is a Dow member |
| Russell 2000 futures | about flat | Small caps were about flat Monday too |
| SPY premarket | 751.85 (about flat) | 7:44 AM ET; Monday close 752.10 |
| QQQ premarket | 683.51 (about +0.4%) | 7:44 AM ET; Monday close 681.09 |
Top Premarket Stories
Moves are premarket, as of about 7:45 AM ET (Nasdaq.com).
Apple (AAPL), about −4%. Fiscal fourth-quarter revenue rose 12% to $114.5 billion, ahead of the roughly $113.4 billion expected, and EPS of $2.10 beat the roughly $1.99 consensus. Apple guided December-quarter revenue growth of 7%–10% and gross margin of 45%–46%, as memory chip prices keep rising (Apple release; earnings call via Investing.com; Reuters).
Palantir (PLTR), about −6%. Third-quarter revenue jumped 96% to $2.313 billion and Palantir raised its 2026 revenue outlook to $8.530–$8.534 billion (company release). Traders focused on new deals instead: total contract value of $2.918 billion grew 6% from a year ago, after 49% growth the quarter before (Tradingpedia; Traders Union).
Harmonic (HLIT), about +17%. Third-quarter revenue rose 64% to $148.8 million, above the top of its guidance, and the broadband equipment maker raised its 2026 revenue outlook to $545–$555 million (SEC 8-K; Reuters).
Aehr Test Systems (AEHR), about +15%. Record fiscal first-quarter revenue of $33.0 million was up 200%, and the chip-testing company now expects fiscal 2027 revenue of $150 million, the top of its prior $130–$150 million range (SEC 8-K).
Chips bounce. AMD (about +3%) reports tonight after falling 7.5% on Monday; Micron (about +3.5%), Intel (about +3%) and Nvidia (about +2%) are also higher. We found no company news behind the Micron and Intel moves, so we read them as a rebound from Monday’s selling.
Sectors
Before the open, semiconductors are leading the rebound while mega-cap tech is split: Apple is lower and Nvidia is higher. Monday’s scoreboard showed the rotation clearly, with technology down 2.94% and energy down 3.93% while consumer discretionary rose 2.39%. All 11 sectors are in our Monday close recap.
Rates, Dollar and Commodities
| Asset | About 7:45 AM ET | One line |
|---|---|---|
| 10-year yield | near 4.9% | 4.91% at Monday’s close (Treasury) |
| WTI crude | $97.1 (+0.8%) | Rebounds after Monday’s 7.6% drop |
| Brent crude | about $105 | Reported U.S. strike on Iran’s Qeshm Island |
| Gold | $3,923 (−1.2%) | Gives back part of Monday’s gain |
| Bitcoin | about $77,500 | Under $78K |
The dollar index is left out today because we could only confirm it with one source.
Economic Data Today
| Time (ET) | Release | Consensus | Prior | Actual |
|---|---|---|---|---|
| 10:00 AM | JOLTS Job Openings (Sep) | 7.1M–7.16M | 7.08M | 7.5M |
| 10:00 AM | Factory Orders (Sep) | +1.1% to +1.2% | +0.1% | +1.8% |
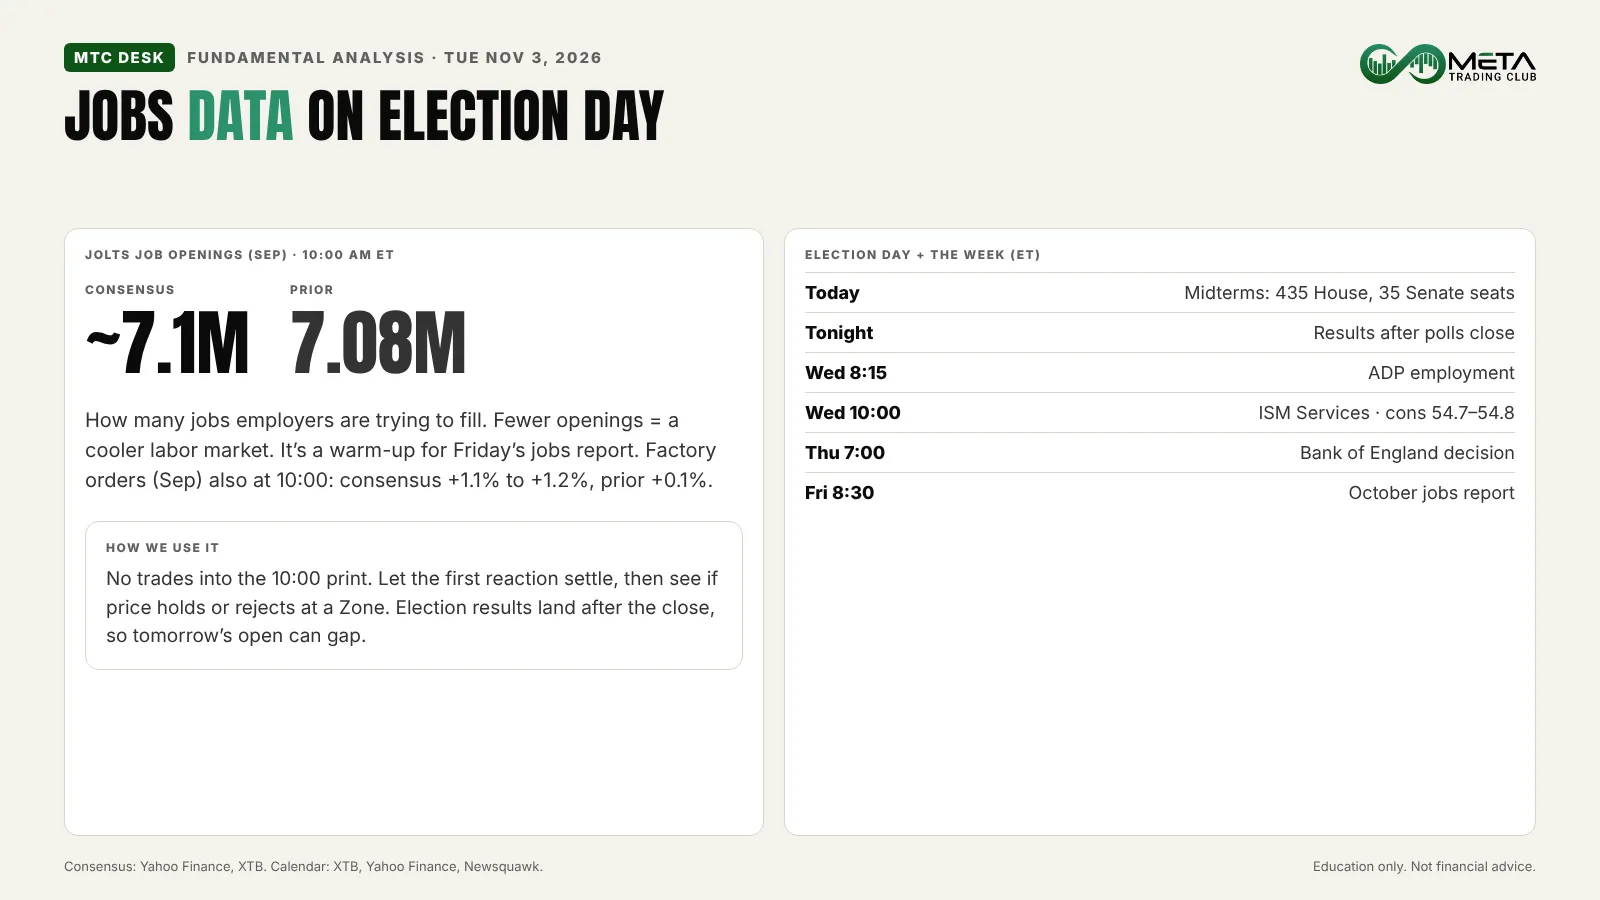
JOLTS counts the jobs employers are trying to fill. Consensus is about 7.1 million (Yahoo Finance; XTB has 7.164 million) after 7.08 million. Fewer openings point to a cooler labor market, which usually takes some pressure off yields. It is the warm-up for Friday’s October jobs report at 8:30 AM. No Fed speakers are confirmed for today.
Factory orders (Sep) are expected up about 1.1%–1.2% after +0.1%; a big miss would hint at softer business spending.
Midterms: prediction markets put Democrats’ Senate odds at about 73%–75% this morning (Yahoo Finance; CNBC via Stocktwits). Markets tend to react to the surprise against those odds, not the vote itself.
Earnings
Before the open: Pfizer, Archer-Daniels-Midland, Marathon Petroleum, Keurig Dr Pepper, Yum! Brands, Ferrari and Eaton are on the calendar.
After the close: AMD (it guided about $13 billion in third-quarter revenue), Amgen, Super Micro Computer and Prudential. AMD lands on the same night as the election results, after a chip sell-off that took the semiconductor ETF down 2.71% on Monday.
What to Watch Next
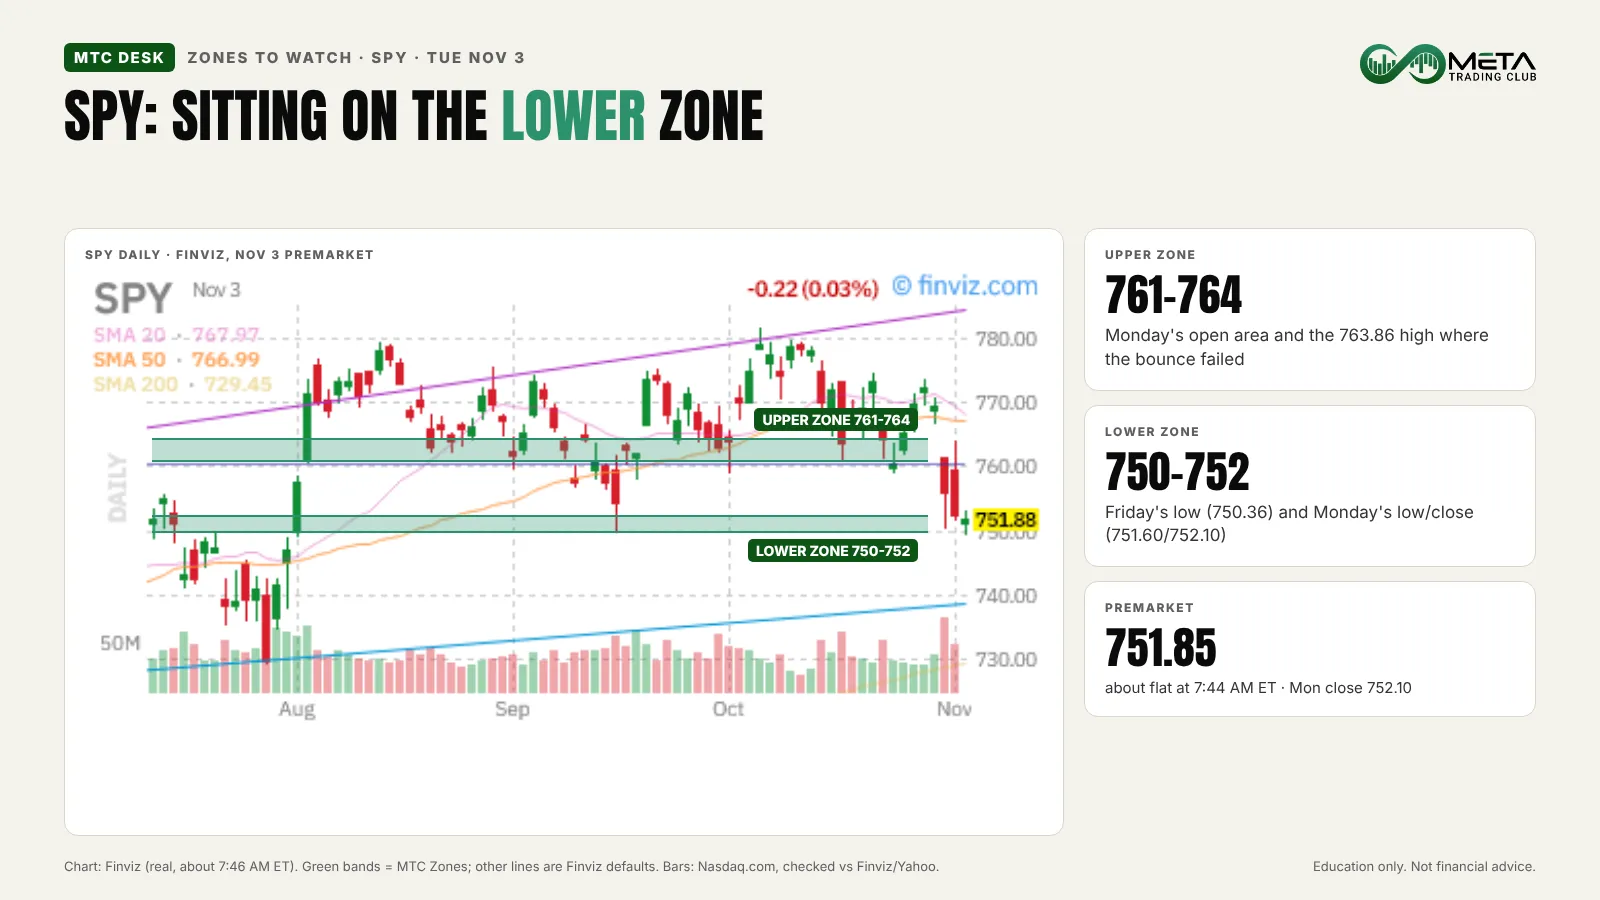
SPY 750–752 is Friday’s low and Monday’s low and close, and premarket sits right on it. A test that holds and pushes back up is the reaction we’d want; a clean break with no reclaim says the pullback has more room. SPY 761–764 is where Monday’s bounce failed, so strength needs acceptance above it, not a poke.
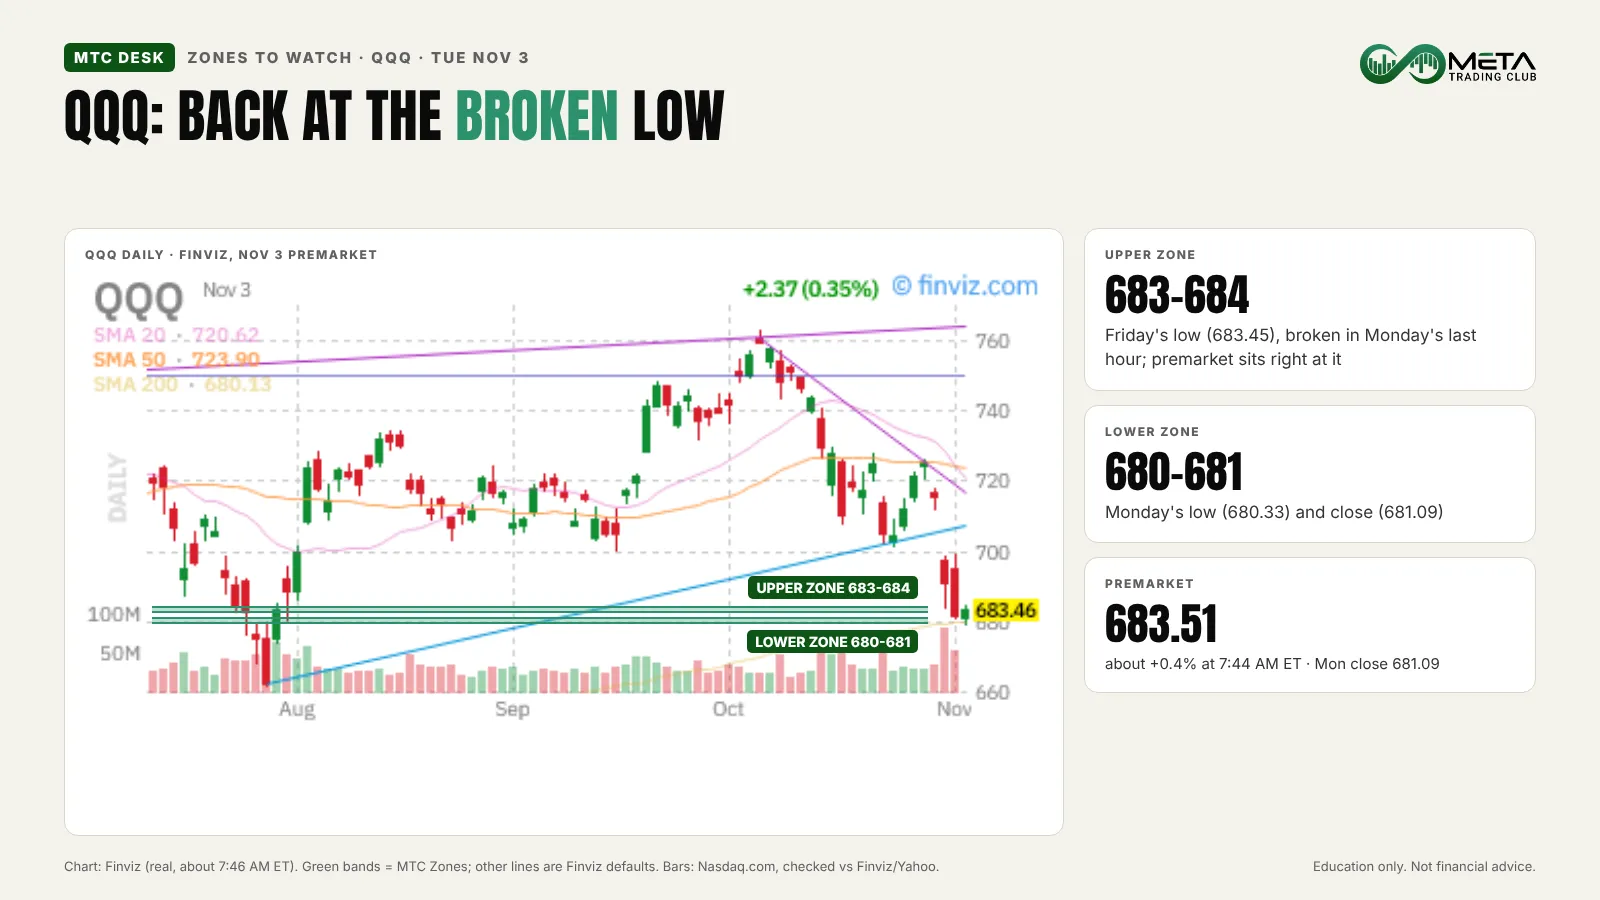
QQQ 683–684 is Friday’s low, broken in Monday’s last hour, and 680–681 is Monday’s low and close. We want SPY and QQQ to agree before trusting a move. If you’re unsure which kind of market this is, our guide to bull vs bear markets is a good place to start, and yesterday’s premarket brief has the Zones we were watching.
Risks: the 10:00 AM JOLTS print, AMD and the election results tonight, ADP and ISM Services on Wednesday, and the jobs report at 8:30 AM Friday. No alignment, no trade.
FAQ
Apple beat on revenue ($114.5 billion, up 12%) and EPS ($2.10), but it guided its December-quarter gross margin to 45%–46% and said it expects even higher memory costs. The stock was down about 4% before the open at 7:45 AM ET.
Voting runs all day and results come in after the close, so the main market reaction is more likely at Wednesday’s open. Prediction markets put Democrats’ Senate odds at about 73%–75% on Tuesday morning; a surprise versus those odds is what tends to move prices.
The September JOLTS job openings report is out at 10:00 AM ET, alongside factory orders. Consensus is about 7.1 million to 7.16 million openings (Yahoo Finance, XTB), after 7.08 million last time.
The lower Zone is 750 to 752 (Friday’s low and Monday’s low and close) and the upper Zone is 761 to 764 (Monday’s open and the high where the bounce failed). They are places to watch for a reaction, not entries.
Featured image: AI-edited from an Apple Newsroom press photo. Sources: Finviz futures (about 7:45 AM ET); Nasdaq.com premarket quotes (7:37–7:45 AM ET); Apple’s fourth-quarter release and earnings call (via Investing.com); Palantir, Harmonic and Aehr company releases and SEC 8-K filings; Reuters; Yahoo Finance; Stocktwits; Tradingpedia; Traders Union; The National; EnergyNow; XTB; U.S. Treasury. Premarket moves are approximate and change before the open.
Education only. Not financial advice.