Thursday, November 5, 2026 · 4:55 PM ET · Shahryar Rahmani, MTC Desk
The Nasdaq correction arrived one day after the post-election rally. The Nasdaq Composite fell 5.52% to 24,315.00 and closed more than 10% below its October 6 record, as chip and AI data-center stocks led a broad sell-off. The S&P 500 fell about 4.4% and the Dow about 1,830 points, both their worst day since April 2025 (CNN).
Read the episode
Hey, I’m Shah, your host, and this is MTC Radio.
Okay, so yesterday’s whole post-election rally is gone. Completely. The Nasdaq fell about five and a half percent today and closed in a correction, which means it’s now more than ten percent below its October high. The S&P 500 was down about four point four percent, and the Dow lost about eighteen hundred points. Every single sector finished red.
Basically, the market is now pricing in what a Democratic Congress means for the whole data center build-out. And it’s not just Congress. Texas matters too, because the new governor-elect there campaigned on a temporary pause on new data centers. So investors are reading it as, data centers get slower and more expensive to build, and that hits everyone who sells into that build-out. On top of that, Nomura said hedge funds are rushing to lock in their gains for the year, so you get selling on top of selling.
And the chip stocks took the worst of it. The semiconductor E T F fell about eleven and a half percent. Micron and AMD were both down more than seventeen percent. Nvidia fell almost nine percent, and C N N said that wiped out its gains for the year. Tesla was down about eleven percent too. Even yesterday’s winners, like Amazon and Meta, slipped. The Nasdaq 100 had its worst day since March of twenty twenty.
Now, there was one name going the other way. AppLovin was up about thirty one percent. They beat on revenue, revenue up fifty five percent, beat on earnings, and guided next quarter well above what people expected. So on a day like this, a stock with its own strong news can still go up. Really good thing to notice.
Meanwhile, money went into bonds. The ten-year yield dropped to about four point eight four percent. Fear spiked, the VIX jumped about sixty percent, its biggest one-day jump in about two years. On the data side, jobless claims came in at a hundred eighty nine thousand, lower than expected, so layoffs are still low.
Now, this morning on Spy our Zone was seven sixty two and a half to seven sixty four. Spy opened right on top of it, and nobody defended it. It broke through in the first few minutes and never came back. On Q Q Q, our Zone was six eighty eight to six ninety, and it opened below that, lost six eighty pretty quickly and just kept pushing lower. So both of them agreed early, and that was a pretty clear situation. In the live session I took a small position on Q Q Q puts after that six eighty break, and closed it for about three R. To be honest, it wasn’t my full system, there was no retest, so it was small size only.
For tomorrow, on Spy I’m watching seven sixty two and a half to seven sixty six above, that’s where the break started, and seven thirty three to seven thirty four and a half below, that’s today’s low and close. On Q Q Q, six eighty to about six eighty three and a half above, and six forty seven to six forty nine below. If we keep rejecting and pushing under today’s low, well, the sellers are still in control. However, if buyers step in at that low and we reclaim it, this could turn into a bounce. I’m not going to guess. I’ll let the price show me.
And we have the jobs report at eight thirty tomorrow morning. On a market this fragile, a surprise either way can move things fast. In early after-hours trading, Airbnb was up about twelve percent and Atlassian down about seventeen, so watch how those open too.
So yeah, that’s what I’m watching. If you want to trade it with us, we’re live Monday, Tuesday, Thursday and Friday in the community. See you there.
The why: investors are pricing in what a Democratic Congress, and Democratic wins in data-center states like Texas, could mean for the AI build-out. Texas Governor-elect Gina Hinojosa campaigned on a temporary data-center moratorium (CNN). eToro’s Jakub Rochlitz said the market now sees the build-out as “slower and more expensive” (Fox Business), and Nomura’s Charlie McElligott said hedge funds are rushing to lock in 2026 gains (Yahoo Finance).
The Nasdaq 100 lost 6.36%, its worst day since March 2020 (CNN). All 11 sectors fell, and the VIX jumped about 60%, its biggest one-day jump in about two years (CNN).
The one big green name was AppLovin, up 31.01% after a beat and a strong outlook.
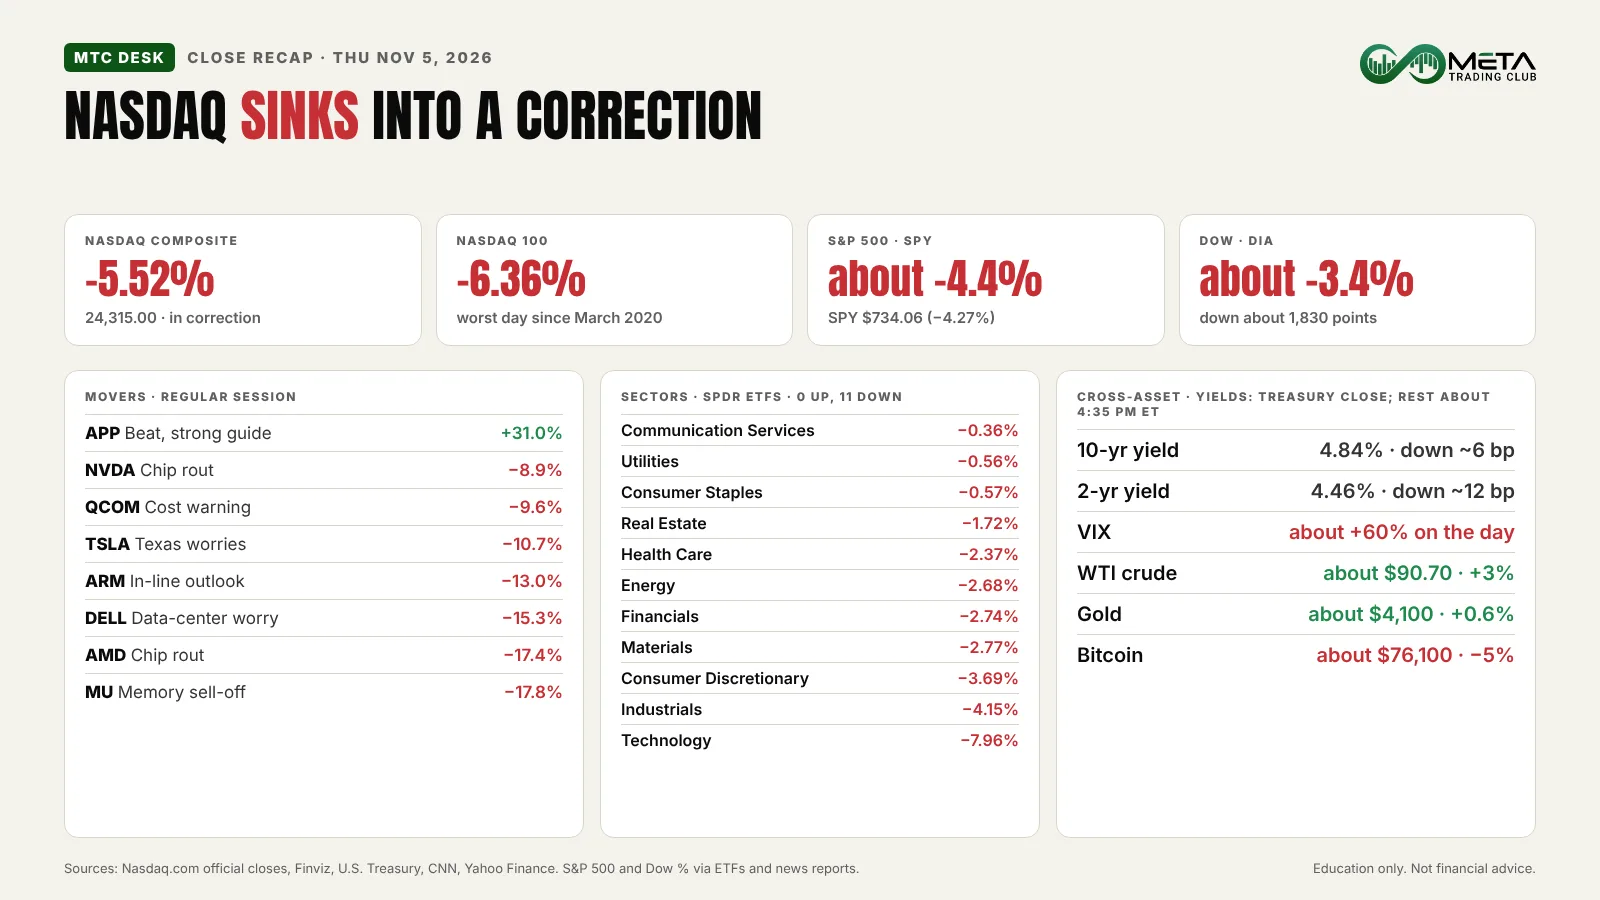
The Closing Bell
Nasdaq index levels are from Nasdaq.com and CNN. S&P 500 and Dow moves are shown through their ETFs (official 4:00 PM ET closes, Nasdaq.com and Finviz) and news reports.
| Index | Close | Change | Note |
|---|---|---|---|
| Nasdaq Composite | 24,315.00 | −5.52% | Closed in correction |
| Nasdaq 100 | 26,629.81 | −6.36% | Worst day since March 2020 (CNN) |
| S&P 500 (SPY) | $734.06 | −4.27% | About −4.4% for the index |
| Dow Jones (DIA) | $514.86 | −3.42% | Down about 1,830 points |
| Russell 2000 (IWM) | $271.33 | −4.47% | Small caps fell with the market |
What Drove The Nasdaq Correction
The AI build-out trade unwound. On Wednesday, chip and data-center names had already slipped while the indexes rallied. On Thursday the selling spread. The Dow’s 1,569-point jump from Wednesday was erased, and more (CNN).
Chips took the worst of it. The semiconductor ETF (SMH) fell 11.50%. Micron dropped 17.77%, AMD 17.39%, Marvell 16.63%, Arm 13.03%, Taiwan Semiconductor 11.16%, Broadcom 10.15% and Nvidia 8.91%. CNN said Nvidia’s drop erased its gains for the year. AI server maker Dell fell 15.27%. AMD CEO Lisa Su told Yahoo Finance the market is “a little bit short-sighted” and she doesn’t see AI chip demand slowing.
Qualcomm fell 9.59% after its report warned of higher memory and input costs (CNN). Our Qualcomm earnings reaction has the numbers.
Beyond chips. Tesla fell 10.66%, as Democratic wins in Texas raised questions about data-center plans and a possible SpaceX merger (Yahoo Finance). Palantir lost 9.49% as software’s AI winners were sold too. The large platforms that rose Wednesday slipped too: Meta −3.62% and Amazon −1.99% (CNN). Microsoft fell 3.26% and Apple 1.25%.
AppLovin (APP) +31.01%. Third-quarter revenue rose 55% to $2.185 billion and diluted EPS was $4.30, against about $2.07 billion and $4.04 expected (company release; Bloomberg estimates via Yahoo Finance). It guided fourth-quarter revenue to $2.365–$2.395 billion, above the roughly $2.25 billion expected, and raised its buyback authorization by $3.2 billion.
Sectors: Tech Down 8%, Nothing Green
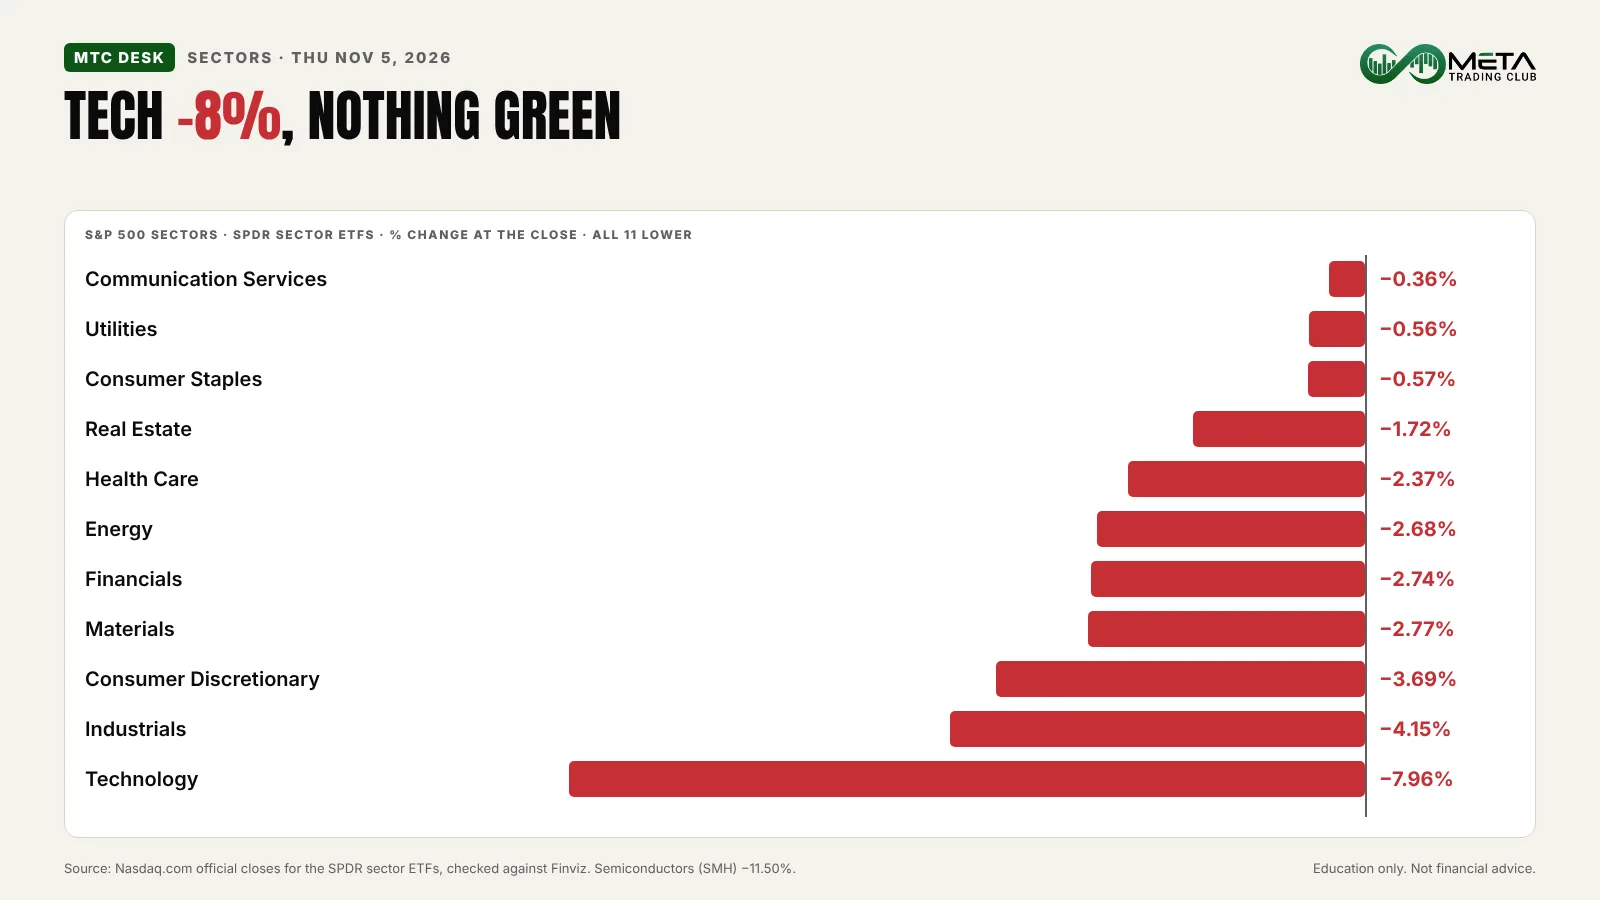
Technology fell 7.96%, the worst sector by far, followed by Industrials (−4.15%) and Consumer Discretionary (−3.69%). Materials (−2.77%), Financials (−2.74%), Energy (−2.68%), Health Care (−2.37%) and Real Estate (−1.72%) were in the middle. The defensive groups fell least: Consumer Staples −0.57%, Utilities −0.56% and Communication Services −0.36%. When nothing is green, breadth tells you this was a market-wide de-risking, not a rotation. Our guide to bull vs bear markets explains why that matters.
Rates, Commodities and Crypto
| Asset | Level | One line |
|---|---|---|
| 10-year Treasury yield | 4.84% | Down about 6 basis points (U.S. Treasury) |
| 2-year Treasury yield | 4.46% | Down about 12 basis points (U.S. Treasury) |
| WTI crude | about $90.70 (about +3%) | Bounced after Wednesday’s drop (Finviz, about 4:35 PM ET) |
| Brent crude | about $98.60 (about +4%) | Near $98 (Finviz, about 4:35 PM ET; Yahoo Finance) |
| Gold | about $4,100 (about +0.6%) | A small safe-haven bid (Finviz, about 4:35 PM ET) |
| Bitcoin | about $76,100 (about −5%) | Gave back Wednesday’s bounce (Finviz, about 4:35 PM ET) |
Economic Data Today
| Time (ET) | Release | Consensus | Prior | Actual |
|---|---|---|---|---|
| 7:00 AM | Bank of England decision | Hike to 4% expected | 3.75% | 4% (8–1 vote) |
| 8:30 AM | Initial Jobless Claims (week ended Oct 31) | about 196K | 195K | 189K |
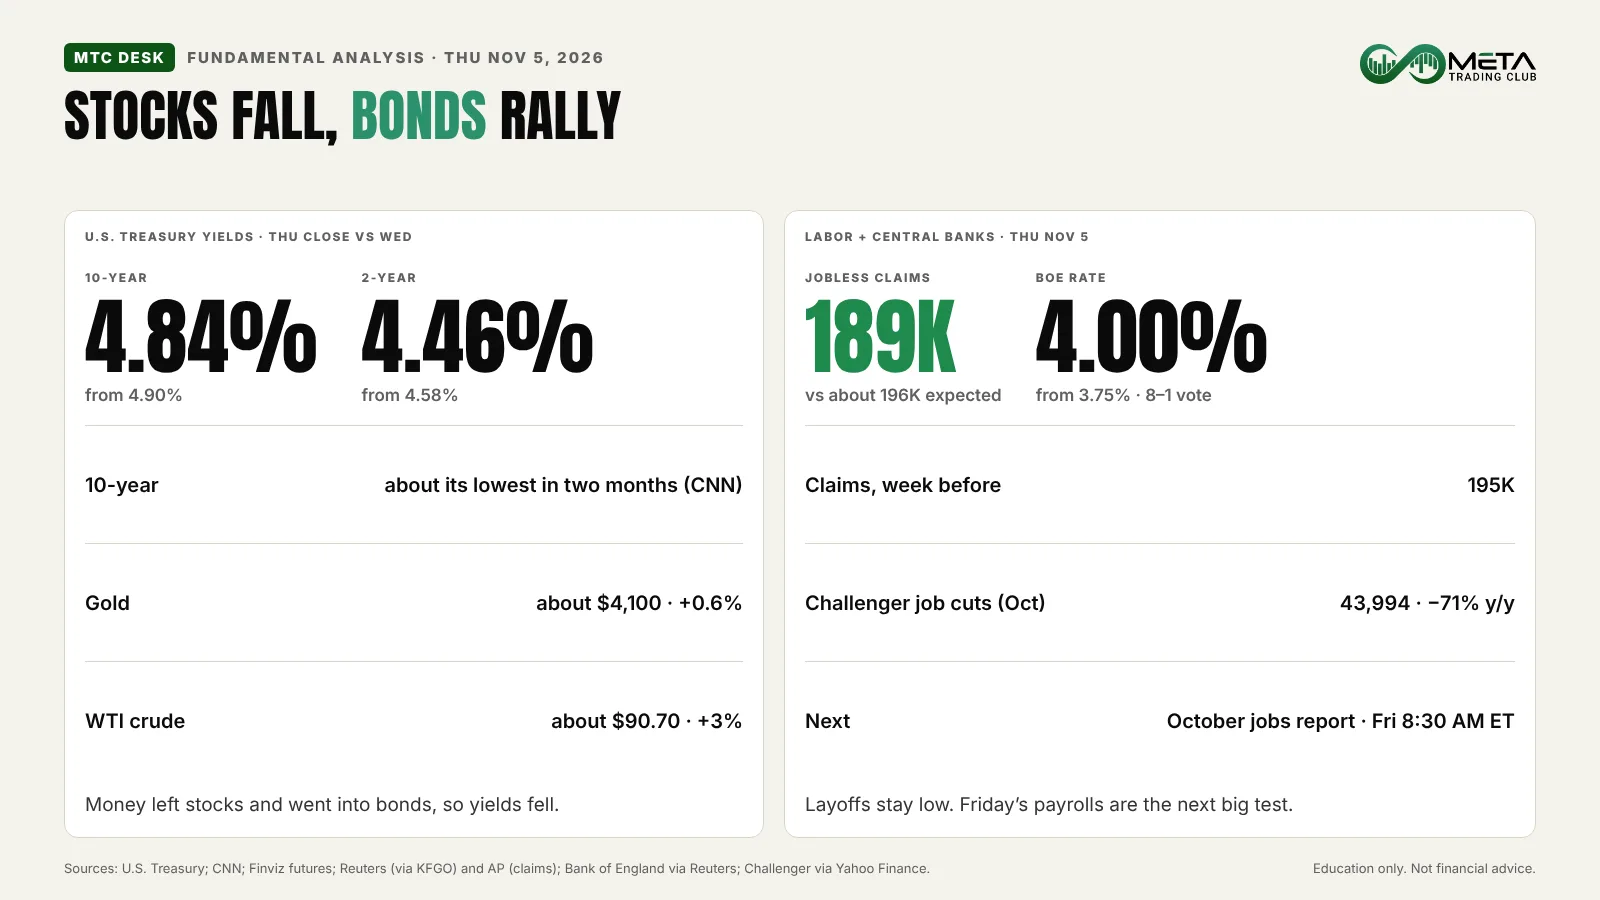
Jobless claims fell to 189,000, below the roughly 196,000 expected and the fewest since mid-July (Reuters; AP). Challenger counted 43,994 announced job cuts in October, down 71% from a year earlier (via Yahoo Finance). Layoffs stay low, which puts the focus on Friday’s payrolls.
The Bank of England raised rates by a quarter point to 4%, its first hike since 2023, and Governor Bailey said more may come unless the Middle East conflict is resolved (Reuters).
Earnings After the Close
Airbnb, Atlassian, Affirm, Microchip, Akamai, Lumentum, IonQ and IREN reported after the bell. At about 4:30 PM ET, Airbnb was about 12% higher, Atlassian about 17% lower, Affirm about 9% lower, and Microchip and Akamai about 5% lower (Finviz). We have not checked the release numbers against two sources yet, so the full breakdown comes in tomorrow’s coverage.
What to Watch Next
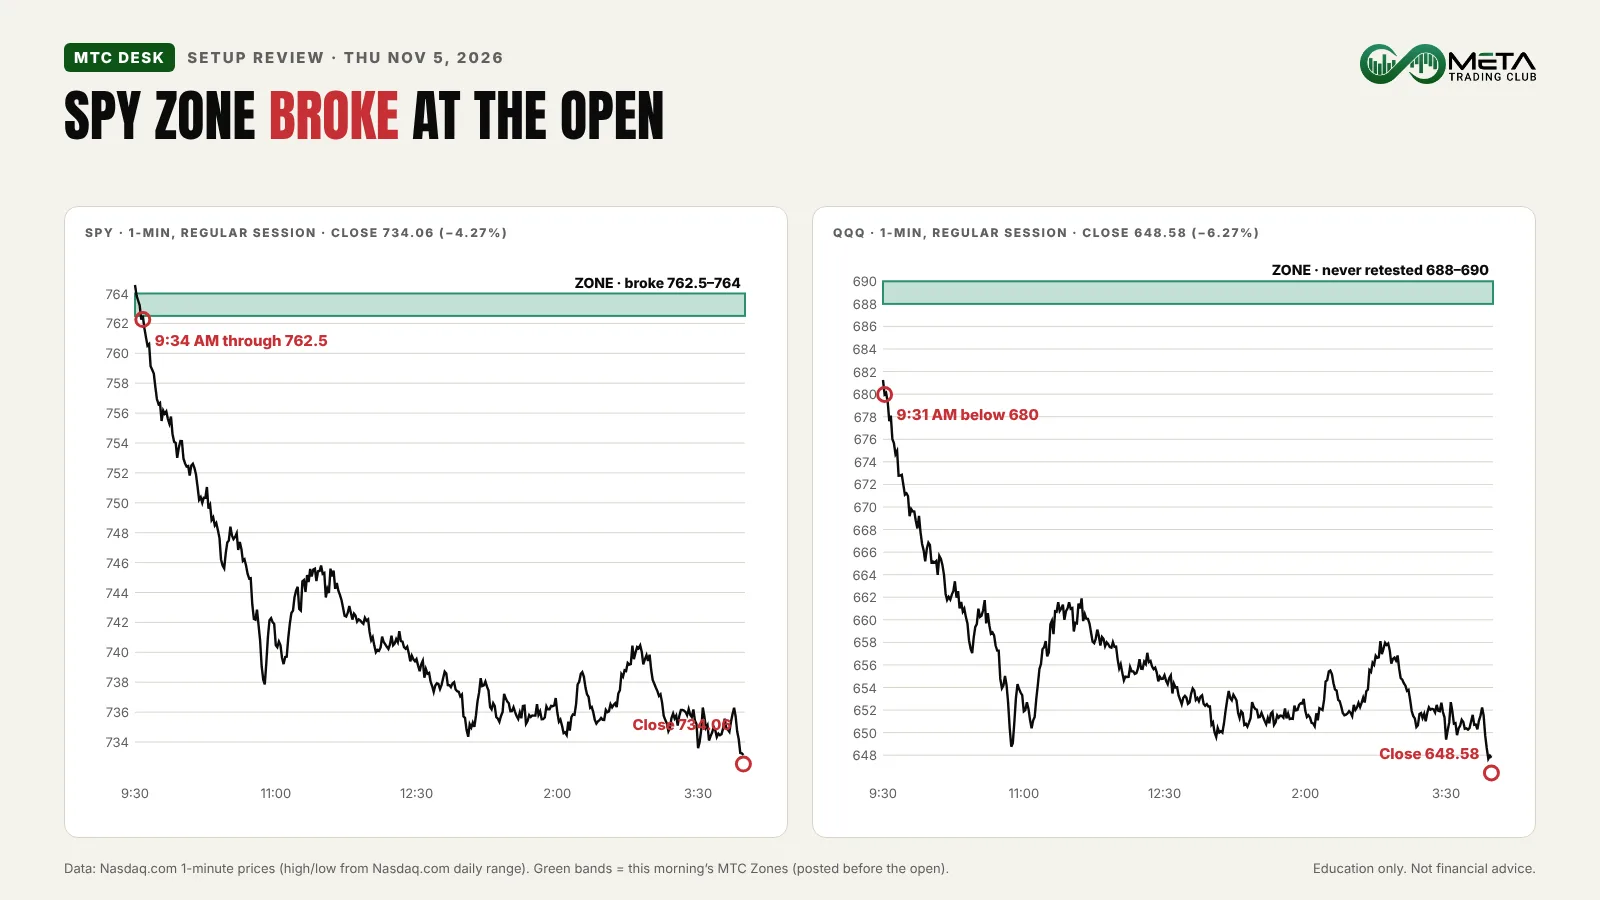
This morning’s premarket brief flagged SPY 762.5–764 and QQQ 688–690, with a split bias. Per Nasdaq.com 1-minute data, SPY opened at 764.57, right on the Zone, and broke through 762.5 at about 9:34–9:36 AM ET with no buyers stepping in. QQQ opened at 681.26, under its Zone, and lost 680 at 9:31 AM ET. Both indexes agreed early, and the sell-off never let up. Yesterday’s close recap shows how these Zones were set.
For Friday, the Zones to watch for a reaction are SPY 762.5–766 (where today’s break started) and 733–734.5 (today’s low and close), and QQQ 680–683.6 and 647–649. After a day this big, the first question is whether sellers keep control near today’s low, or buyers show up there. Our guide to using premarket data to prepare for the day shows how we build these levels.
Calendar (ET): the October jobs report at 8:30 AM Friday (payrolls expected near 65,000 and unemployment at 4.2%, per Nexus). Risks: the after-hours reports, more selling in chips, and a jobs surprise on a fragile tape. No alignment, no trade.
FAQ
Chip and AI data-center stocks sold off hard as investors priced in what a Democratic Congress, and Democratic wins in data-center states like Texas, could mean for the AI build-out. The Nasdaq Composite fell 5.52% to 24,315.00 and closed more than 10% below its October 6 record, which is the usual definition of a correction.
The VanEck Semiconductor ETF (SMH) fell 11.50%. Micron dropped 17.77%, AMD 17.39%, Marvell 16.63%, Arm 13.03%, Broadcom 10.15% and Nvidia 8.91%. CNN said the chip index had its worst day in about six and a half years.
AppLovin reported third-quarter revenue of $2.185 billion, up 55%, and diluted EPS of $4.30, both above estimates, and guided fourth-quarter revenue to $2.365 billion to $2.395 billion, above the roughly $2.25 billion expected (Bloomberg, via Yahoo Finance). It closed up 31.01%.
Bonds rallied as money left stocks. The 10-year Treasury yield fell to 4.84% from 4.90%, and the 2-year yield fell to 4.46% from 4.58%, according to U.S. Treasury data.
Sources: Nasdaq.com official closes, index levels and 1-minute prices; Finviz quotes, after-hours quotes and futures; U.S. Treasury daily yield curve; CNN; Yahoo Finance; Fox Business; AppLovin Q3 2026 release (SEC 8-K Ex. 99.1); Reuters (via KFGO); AP (via ABC News); Nexus. After-hours and futures moves are approximate and carry their time. Featured image: AI-edited from the Nasdaq MarketSite in Times Square, New York (photo: ajay_suresh, Wikimedia Commons, CC BY 2.0).
Education only. Not financial advice.