Tuesday, November 3, 2026 · 8:30 PM ET · Shahryar Rahmani, MTC Desk
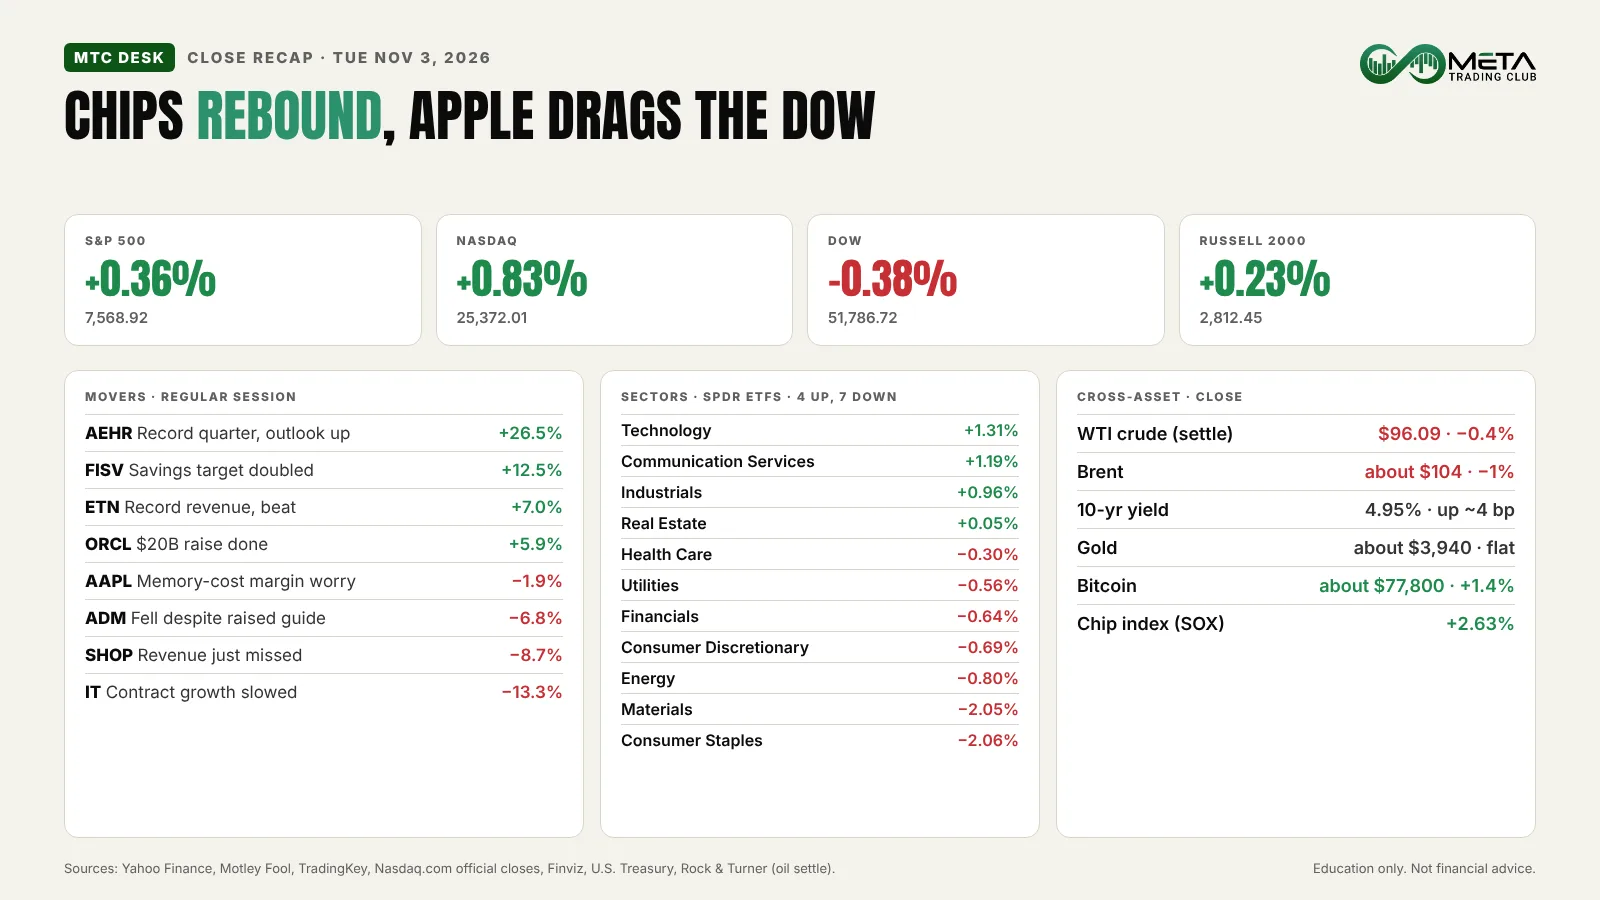
A chips rebound lifted the Nasdaq 0.83% on Election Day, while Apple (−1.90%) dragged the Dow down 0.38%. The S&P 500 added 0.36% to 7,568.92. After the bell, AMD beat on revenue and earnings and its stock was up about 4.6% by 7:27 PM ET.
Read the episode
Hey, I’m Shah, your host, and this is MTC Radio. Okay, so today the Nasdaq was green, but if you looked under the hood, most stocks were actually red.
So what happened? Chips came back. After last week’s sell-off, the chip stocks bounced really hard. The chip index was up a bit over two and a half percent, and every single name in it closed green. Nvidia was up a bit over two percent. And chips are a massive piece of the Nasdaq, so the Nasdaq finished up a bit over three quarters of a percent, and the S&P 500 was up about a third of a percent.
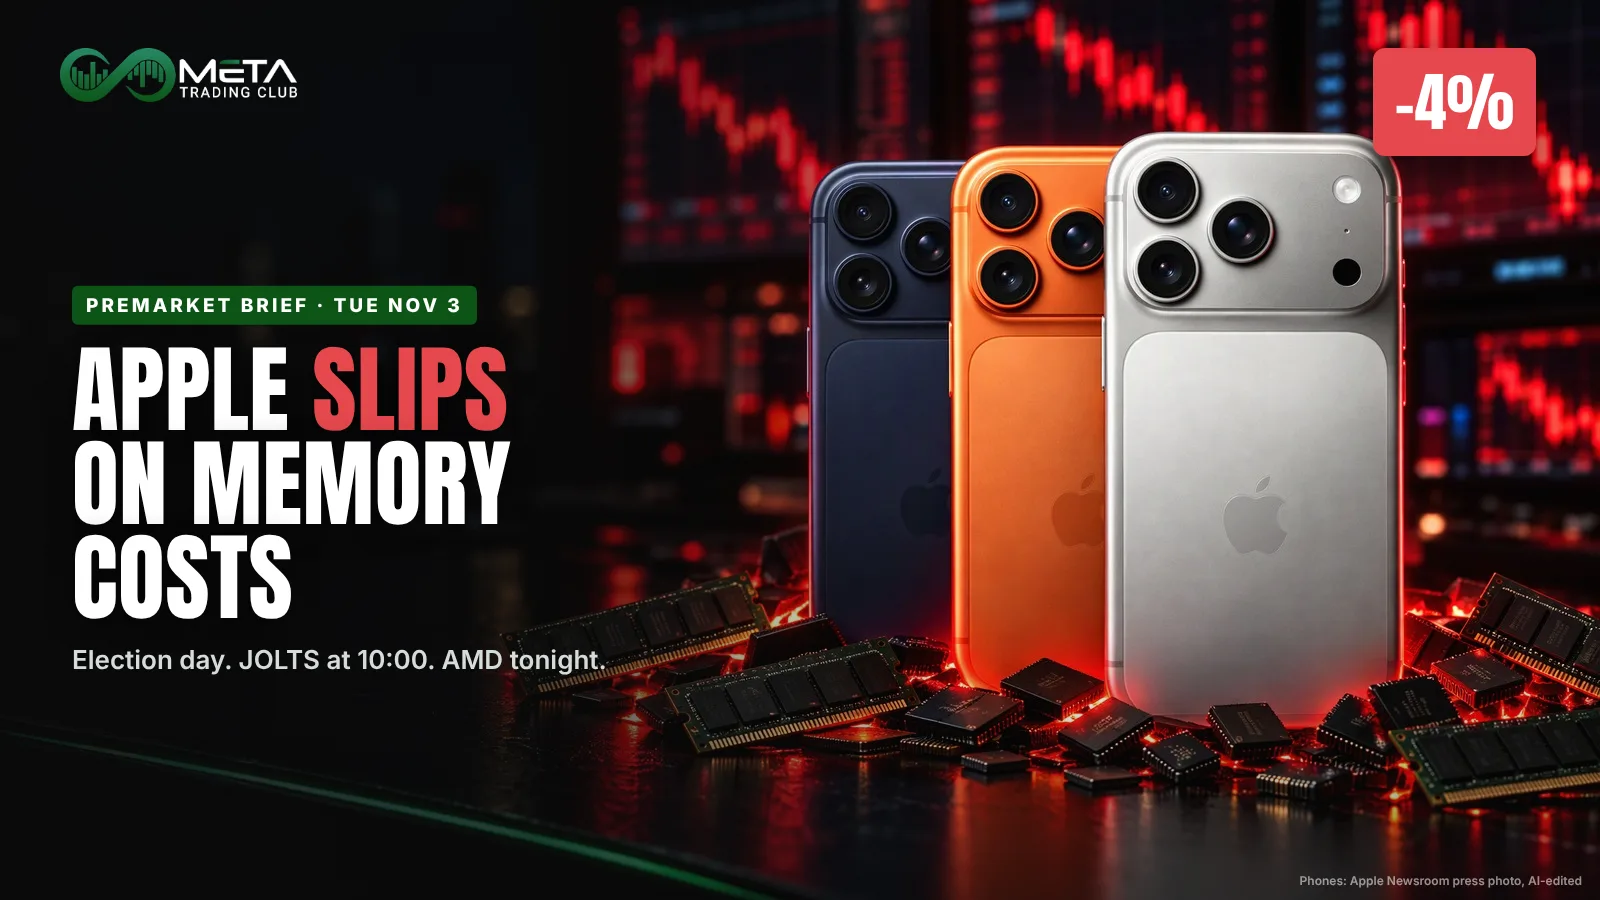
Now, the Dow was down about four tenths of a percent. Why? Because of Apple. Apple slipped about two percent again today. Basically, the market is still digesting that warning about memory costs. Apple said those costs keep going up, and that squeezes their margins for the holiday quarter. So yeah, Apple was the biggest weight on the Dow.
Now, what I really want you to notice. Only four out of eleven sectors were green today. Consumer staples and materials were each down about two percent. So the index was green, but it was a pretty narrow day. A few big winners can definitely hide a lot of red underneath.
Of course, it’s also election day. The midterms. So trading was quiet, and the results come in tonight. Analysts are saying a Democratic sweep is not really priced in, so as a result, the open tomorrow could move fast in either direction.
On the data side, job openings came in at about seven and a half million. That’s more than the seven point one million that was expected. Factory orders also beat. So the economy still looks pretty solid, and the ten-year yield went up, to about four point nine five percent.
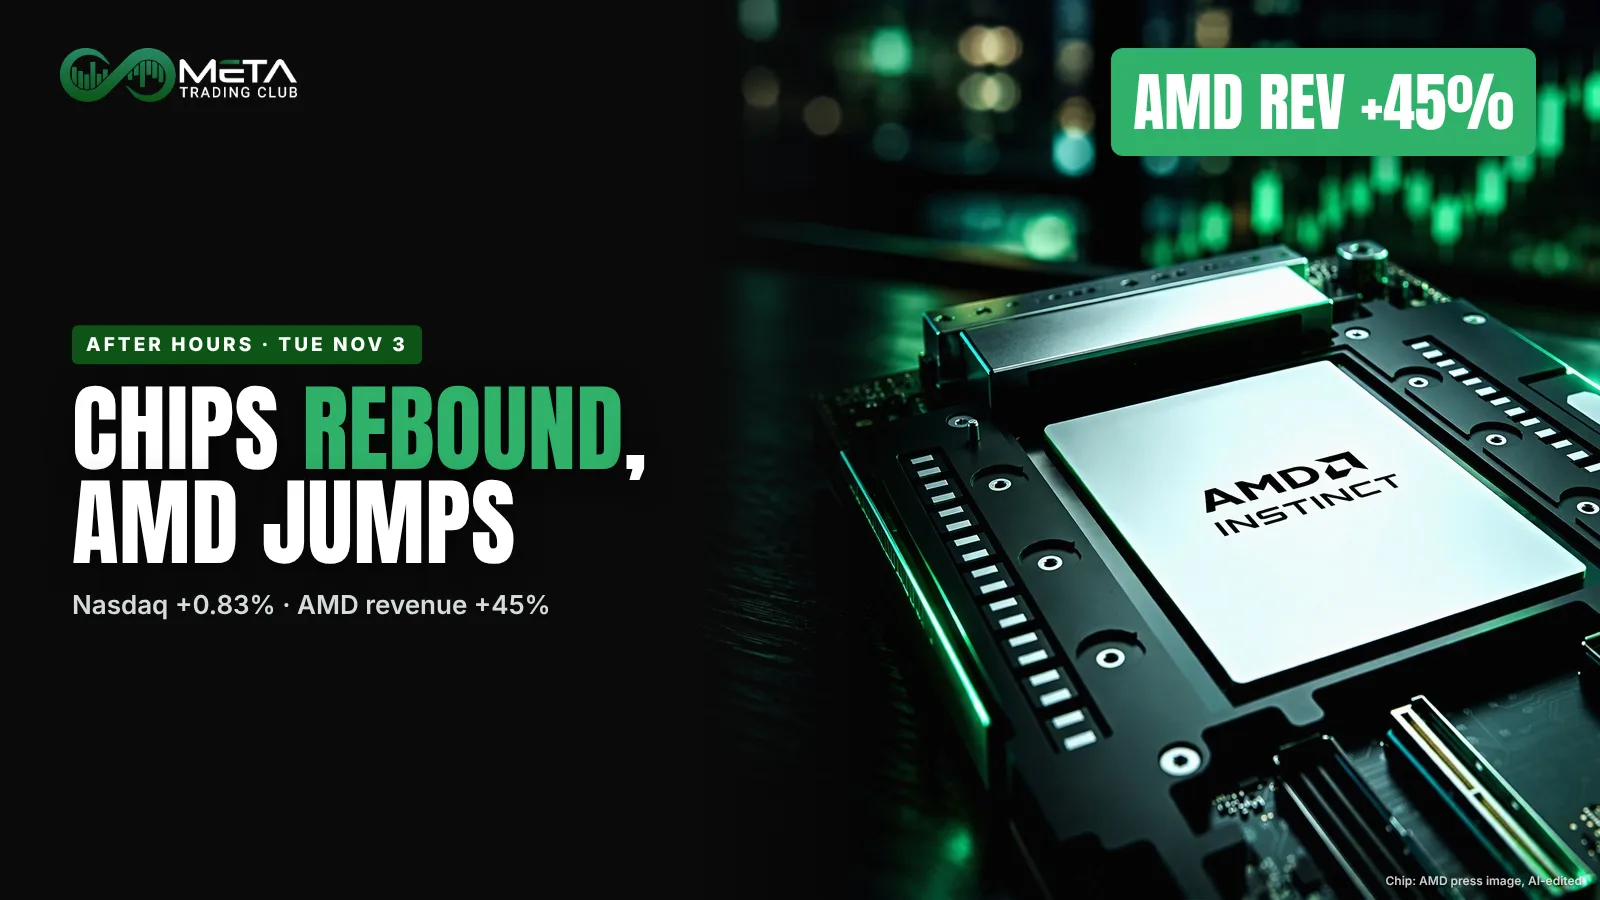
Then after the close, AMD reported. And it was a strong report. Revenue was up forty-five percent, and the data center business almost doubled, to about eight and a half billion dollars. They beat on revenue and they beat on earnings. The stock was up about four and a half percent after hours, as of about seven thirty. Super Micro also reported, sales came in way above last year, and the stock was up about seven percent after hours.
All right, so how am I reading this? This morning we had the Spy seven fifty, seven fifty two zone as the floor, and on Q Q Q, six eighty, six eighty one as the floor, with six eighty three, six eighty four, the zone we lost on Monday, to reclaim. Both floors got tested before the open, and both held. Q Q Q opened right back above six eighty three, six eighty four, and then in the afternoon it came back to retest that zone and held it again. So we got the reaction, and on Q Q Q, we got the confirmation on the retest. But Spy never got to its upper zone. That’s pretty normal for an event day. I’d call it a B.
Now, for tomorrow. On the Spy, I’m watching seven fifty six, seven fifty seven, that’s today’s high, and seven fifty two, seven fifty three below, that’s today’s open and the low. On Q Q Q, six eighty eight, six eighty nine is today’s high, and six eighty three, six eighty four is the zone we reclaimed. If it keeps holding above it, well, buyers are still in control. However, if the election news pushes us below it and we can’t reclaim it, well, then we have a different situation.
Keep in mind, the election results can gap us right past all of these levels. So I’m not interested in chasing the first move. I want to see Spy and Q Q Q agree first. Then we have ADP at eight fifteen, and the ISM services number at ten. And on Friday, we get the jobs report at eight thirty.
That’s the show. We trade live four days a week, Monday, Tuesday, Thursday and Friday. If you want to sit in with us, you know where to find us. This is education, not financial advice. No alignment, no trade.
The rally was narrow. The chip index rose about 2.6% with all 30 members higher, and Technology was the best sector, but only four of 11 sectors finished green. Consumer Staples and Materials each lost about 2%, and most S&P 500 stocks fell.
Voters went to the polls for the midterm elections, so trading was subdued. Prediction markets put Democrats’ Senate chances at about 73% to 76% on Tuesday, and analysts said a Democratic sweep isn’t priced in. Results come in overnight.
The data was firm. JOLTS job openings rose to 7.5 million, above the 7.1 million expected, and factory orders jumped 1.8%. The 10-year yield rose to 4.95%.
The Closing Bell
| Index | Close | Change | Note |
|---|---|---|---|
| S&P 500 | 7,568.92 | +0.36% | Tech up, most stocks down |
| Nasdaq Composite | 25,372.01 | +0.83% | Chip rebound led the way |
| Nasdaq 100 | 28,180.26 | +0.68% | Apple held it back |
| Dow Jones | 51,786.72 | −0.38% | Apple was the heaviest drag |
| Russell 2000 | 2,812.45 | +0.23% | Small caps edged up |
What Drove The Day
The chip rebound. Semiconductors bounced after last week’s slide: the PHLX Semiconductor Index rose 2.63% with every member up (TradingKey), and the semiconductor ETF (SMH) gained 2.01%. Nvidia rose 2.29% (Yahoo Finance, The Motley Fool).
Apple (AAPL) −1.90%. Apple extended its post-earnings slide. It guided December-quarter gross margin to 45%–46% and warned that memory-chip costs will rise further, which squeezes profit. It was the heaviest weight on the Dow (StockTitan, Rock & Turner).
Aehr Test Systems (AEHR) +26.50%. Revenue tripled to a record $33.0 million, bookings were $46.7 million, and Aehr moved its fiscal 2027 revenue outlook to $150 million, the top of its prior range (SEC 8-K). It was about 15% higher before the open (7:45 AM ET) and kept climbing.
Eaton (ETN) +6.95%. Revenue rose 28% to a record $8.9 billion, above the roughly $8.53 billion expected, and adjusted EPS of $3.68 beat $3.54. Its 2026 EPS guide of $13.70–$13.80 sits above the $13.60 consensus, helped by data-center demand (Yahoo Finance). Fiserv jumped 12.46% after doubling its cost-savings target to $1 billion and announcing a $500 million buyback.
Oracle (ORCL) +5.86% after it completed its roughly $20 billion stock-and-bond raise for AI data centers; with the deal done, the overhang cleared (Rock & Turner). Palantir slipped 1.65%, well off its premarket level (about −6% at 7:45 AM ET), as investors weighed slower new U.S. contract growth.
The losers. Gartner fell about 13% as contract-value growth slowed to 1.1%. Sysco lost 9.32% on cost pressure, Shopify fell 8.74% after revenue of $3.74 billion just missed the $3.75 billion expected, and Archer-Daniels-Midland (−6.76%) and Keurig Dr Pepper (−5.65%) fell even with raised or reaffirmed guidance.
Sectors: Tech Up, Defensives Down
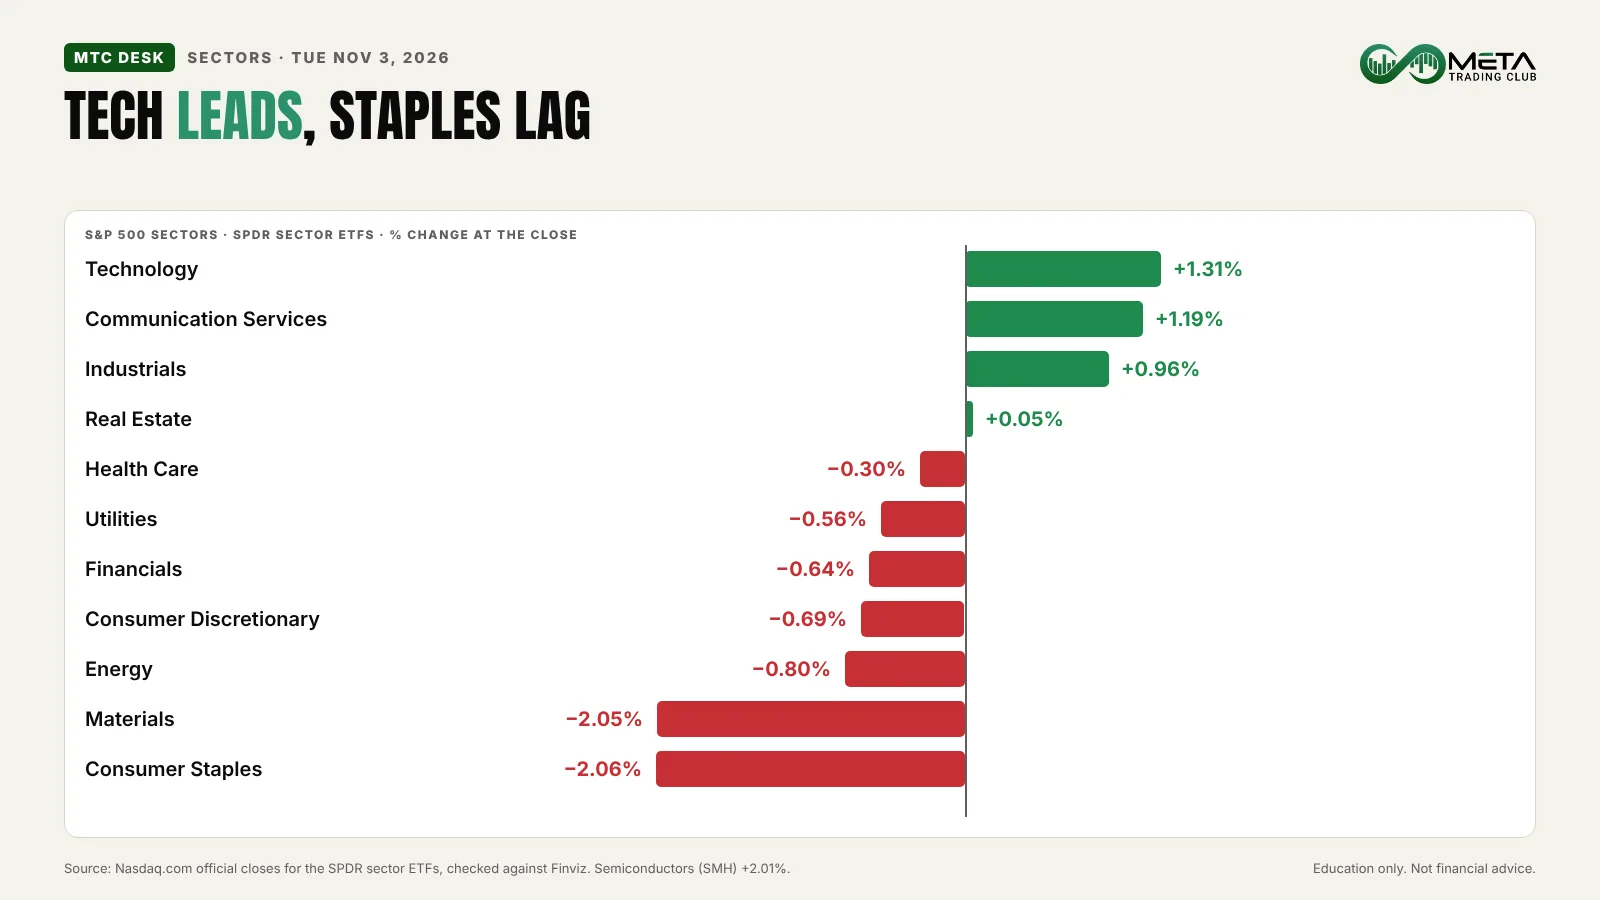
Technology led at +1.31%, followed by Communication Services (+1.19%), Industrials (+0.96%) and Real Estate (+0.05%). Health Care (−0.30%), Utilities (−0.56%), Financials (−0.64%), Consumer Discretionary (−0.69%) and Energy (−0.80%) slipped, and Materials (−2.05%) and Consumer Staples (−2.06%) fell the most. The one reason: money went into chips and tech while staples and materials lagged. Our guide to bull vs bear markets explains why a green index can hide a mostly red day.
Rates and Commodities
| Asset | Close | One line |
|---|---|---|
| 10-year Treasury yield | 4.95% | Up about 4 basis points (U.S. Treasury) |
| WTI crude | $96.09 (−0.4%) | Lowest settle in nearly four weeks |
| Brent crude | about $104 (−1%) | Wartime premium keeps unwinding |
| Gold | about $3,940 | Little changed |
| Bitcoin | about $77,800 (+1.4%) | Higher on the day |
Crude is down about 8% in two sessions from Friday’s $104.12 settle as the wartime premium unwinds (Rock & Turner). Gasoline still averaged $4.14 a gallon nationally, per AAA (via Yahoo Finance).
Economic Data Today
| Time (ET) | Release | Consensus | Prior | Actual |
|---|---|---|---|---|
| 10:00 AM | JOLTS Job Openings (Sep) | 7.1M–7.16M | 7.19M (Aug, revised) | 7.5M |
| 10:00 AM | Factory Orders (Sep) | +1.1% to +1.2% | +0.3% (Aug, revised) | +1.8% |
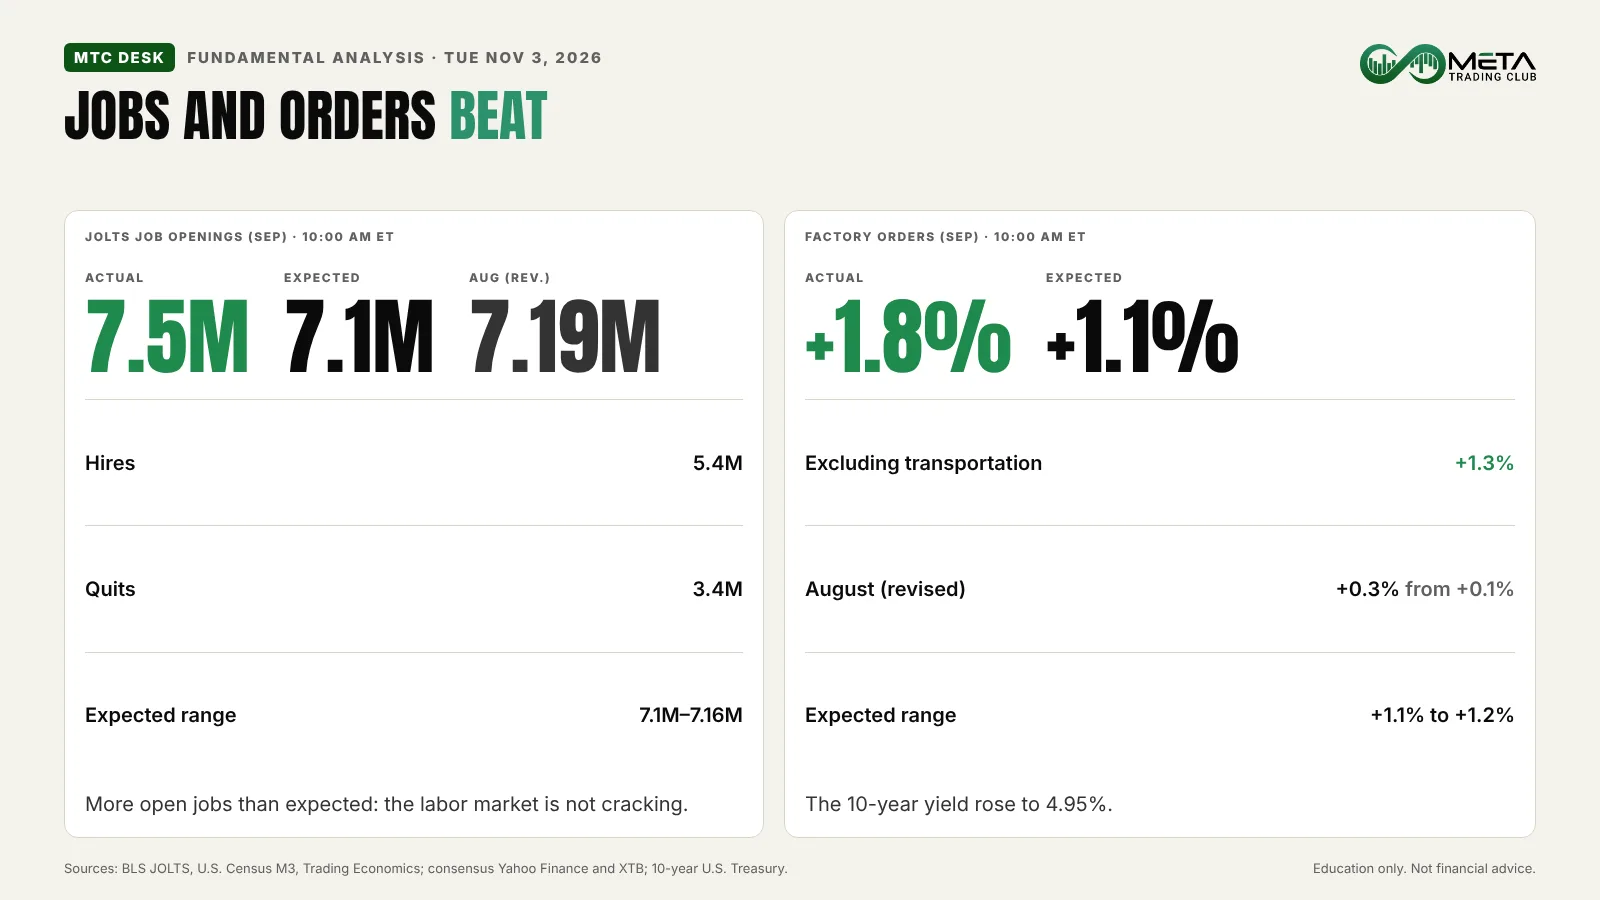
JOLTS showed 7.5 million job openings in September against 7.1–7.16 million expected, with August revised up to 7.19 million (BLS). Hires were 5.4 million and quits were 3.4 million. More openings mean employers still want workers, so the labor market isn’t cracking. See how inflation reports move the stock market for why firm data pushes yields up.
Factory orders rose 1.8% against +1.1% to +1.2% expected, and 1.3% excluding transportation (U.S. Census Bureau). The 10-year yield rose to 4.95%.
Earnings After the Close
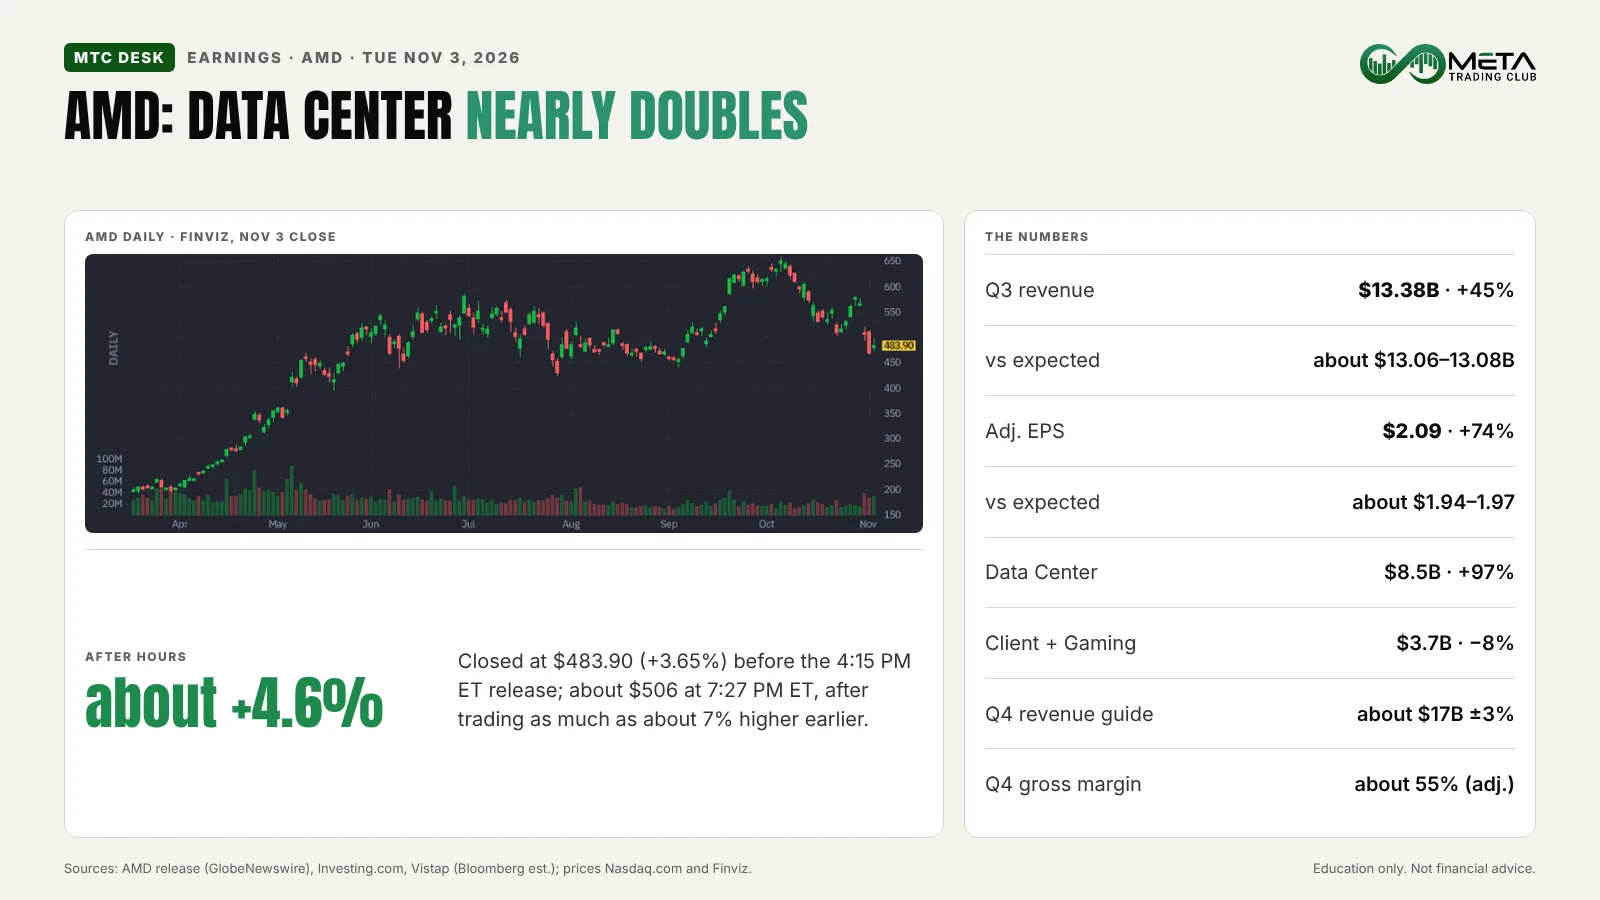
AMD reported revenue of $13.38 billion, up 45%, against about $13.06–$13.08 billion expected, and adjusted EPS of $2.09 against about $1.94–$1.97 (Investing.com; Bloomberg via Vistap). Data center revenue nearly doubled to a record $8.5 billion, up 97%. AMD guided fourth-quarter revenue to about $17 billion, plus or minus 3%, and said on the call it expects 2027 revenue to grow more than 80%. The stock closed up 3.65% at $483.90 before the 4:15 PM ET release and was about 4.6% higher at 7:27 PM ET, after trading as much as about 7% higher earlier in the evening.
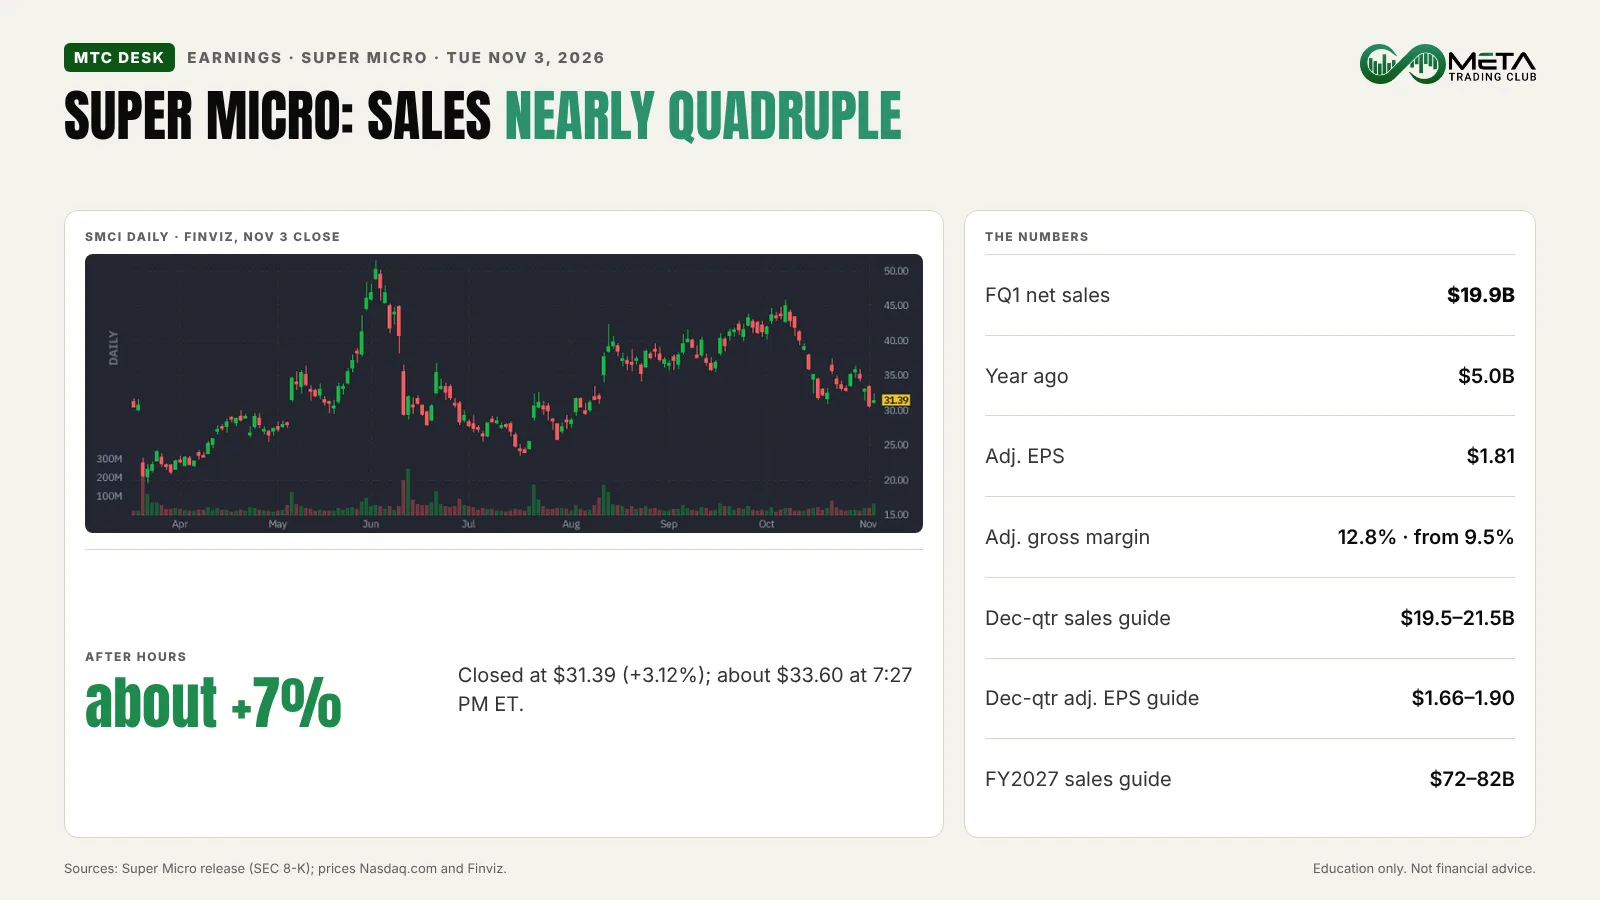
Super Micro Computer (SMCI) posted fiscal first-quarter net sales of $19.9 billion, up from $5.0 billion a year earlier, and adjusted EPS of $1.81 (SEC 8-K). It guided December-quarter sales to $19.5–$21.5 billion. Shares were about 7% higher after hours (7:27 PM ET).
Amgen (AMGN) grew revenue 8% to $10.4 billion with adjusted EPS of $6.45, up 14%; Repatha sales rose 37%. It guided 2026 revenue to $38.9–$39.7 billion. Shares were about 1.4% lower after hours (7:27 PM ET). Prudential Financial (PRU) earned an adjusted operating $3.77 a share, down from $4.05 a year ago, and returned $741 million to shareholders; shares were about 1.1% higher after hours (7:27 PM ET).
What to Watch Next
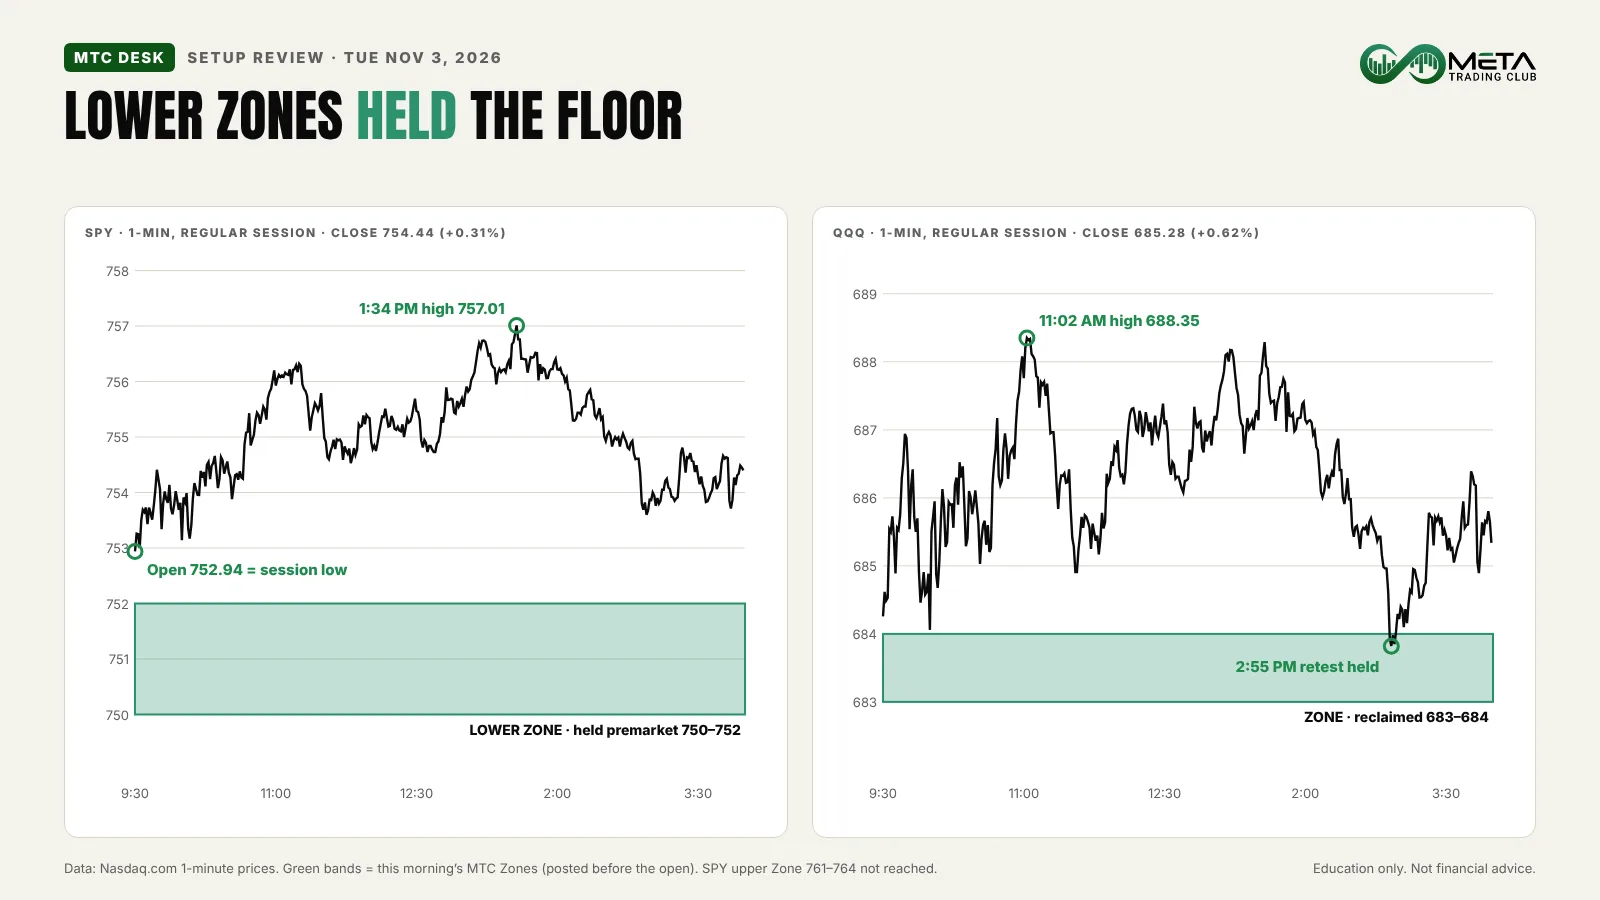
This morning’s premarket brief flagged SPY 750–752 and QQQ 680–681 as the floors to watch. Both were tested before the open (SPY 750.31 at 7:01 AM ET, QQQ 680.83 at 7:00 AM ET) and held. QQQ opened back above 683–684, the Zone it lost Monday, ran to 688.35 at 11:02 AM ET, and held that Zone on a 2:55 PM ET retest. SPY never reached its 761–764 upper Zone.
For Wednesday, the Zones to watch for a reaction are SPY 756–757 above (today’s high) and SPY 752–753 below (today’s open and low). On QQQ, 688–689 is today’s high and 683–684 is the reclaimed floor. Election results can gap the open past all of them, so we wait for SPY and QQQ to agree before trusting a move. Our guide to using premarket data to prepare for the day shows how we build these levels.
Calendar (ET): midterm results overnight, ADP employment at 8:15 AM and ISM Services at 10:00 AM Wednesday (consensus 54.7–54.8). The Bank of England and jobless claims follow Thursday, and the October jobs report lands at 8:30 AM Friday. Risks: an election surprise, higher yields, and how AMD trades at the open. No alignment, no trade.
FAQ
The Nasdaq Composite rose 0.83% because chip stocks rebounded after last week’s sell-off. The chip index gained about 2.6% with all 30 members higher, and Nvidia rose 2.29%. Apple fell 1.90%, which pulled the Dow down 0.38%.
AMD reported third-quarter revenue of $13.38 billion, up 45%, against about $13.06 to $13.08 billion expected, and adjusted EPS of $2.09 against about $1.94 to $1.97. Data center revenue nearly doubled to $8.5 billion. It guided fourth-quarter revenue to about $17 billion. The stock was about 4.6% higher after hours at 7:27 PM ET.
September job openings rose to 7.5 million, above the 7.1 million expected, after a revised 7.19 million in August. More open jobs than expected means the labor market is still firm, and Treasury yields rose.
Trading was quiet during Election Day itself. Results come in after polls close, so the reaction shows up in the next session. Prediction markets put Democrats’ Senate chances at about 73% to 76% on Tuesday, and analysts said a Democratic sweep was not priced in.
Sources: Yahoo Finance; The Motley Fool; TradingKey; StockTitan; Vistap Global; Rock & Turner (oil settle, mover reasons); Nasdaq.com official closes, after-hours quotes and 1-minute prices; Finviz; U.S. Treasury daily yield curve; BLS JOLTS; U.S. Census Bureau M3; company releases (AMD via GlobeNewswire) and SEC 8-K filings (Super Micro, Amgen, Prudential, Aehr); Investing.com (AMD call). After-hours moves are approximate and carry their time. Featured image: AI-edited from an AMD press image (AMD Instinct).
Education only. Not financial advice.