Wednesday, November 18, 2026 · 5:30 PM ET · Shahryar Rahmani, MTC Desk
The Nvidia rally fades in a day and health insurers sink the Dow (−1.11%), while the S&P 500 slips 0.23%. Nvidia opened up about 2.5% after its beat and $130 billion guide, then closed about −2.9%, its fifth straight loss (AP; Stock Titan). UnitedHealth fell 10.21% and Humana 13.04% after a proposed Medicare Advantage audit rule (Stock Titan).
Read the episode
Hey, I’m Shah, your host, and this is MTC Radio.
Okay, so Nvidia gave the market everything it asked for last night, and the stock still closed red today. It opened up about two and a half percent after the beat and that hundred and thirty billion dollar guide, and then it just faded all day. It closed down almost three percent. That’s five red days in a row for Nvidia.
The way I read it, people are worried about Nvidia without Jensen Huang. One money manager told Reuters the real question is what the company looks like in three to five years without a leader like him. So the numbers were great, but the market was trading the uncertainty.
Then the health insurers got crushed. The government proposed a new audit rule for Medicare Advantage plans, and UnitedHealth fell about ten percent, Humana about thirteen. That’s a big reason the Dow dropped about five hundred and sixty points, a bit over one percent.
The S&P 500 slipped about a quarter of a percent. That’s five straight losses, the longest streak since June. But the Nasdaq actually finished up about four tenths of a percent, and small caps were up about half a percent. So it really depended on what you owned today.
Retail was the bright spot. TJ Maxx’s parent company jumped about eight percent, and Target was up about four, both on earnings. Energy was the worst sector, down more than three percent, because oil fell after bigger than expected builds in US crude and fuel supplies.
And at two o’clock we got the Fed minutes. Almost every official said more rate hikes are probably coming, and a couple even said a bigger hike could be on the table in December. The market pretty much shrugged, because a December hike is already priced in. The ten-year yield actually eased a little, to around five point oh six.
After the bell, Palo Alto Networks beat on sales and earnings and raised its full year outlook. It also announced a deal to buy a startup called Applied Compute. The stock was up about six and a half percent at around four thirteen. But remember, it already ran almost ten percent during the day, so we’ll see if buyers hold it tomorrow.
Now, on Spy, our upper zone this morning was seven thirty three up to seven thirty five and a half. Spy opened right inside it, around seven thirty four, and got rejected fast. By about ten to ten it was around seven thirty and three quarters. Then late morning it came down into our lower zone, seven twenty seven to seven twenty nine, and it held. It never broke Tuesday’s low. It bounced back to about seven thirty two and a half by lunchtime, and a second dip in the afternoon held too. So that lower zone gave us a reaction and a confirmation. Q Q Q opened inside its upper zone, around six sixty one and a half, and got rejected the same way. The lower zone on Q Q Q never got tested.
So for the second day, a zone that broke on Tuesday acted like a ceiling. And a strong earnings number didn’t change that.
For tomorrow, on Spy I’m watching the same seven thirty three to seven thirty five and a half up top, and seven twenty seven to seven twenty nine below. On Q Q Q, six sixty and a half to about six sixty three above, and six fifty four to six fifty six below, that’s today’s low area. We’ll see if we reject or break them. Walmart reports before the open, and Anthropic is expected to start trading tomorrow, so the open could be busy.
So yeah, that’s what I’m watching. We’re live tomorrow in the community, so if you want to trade it with us, come hang out. See you there.
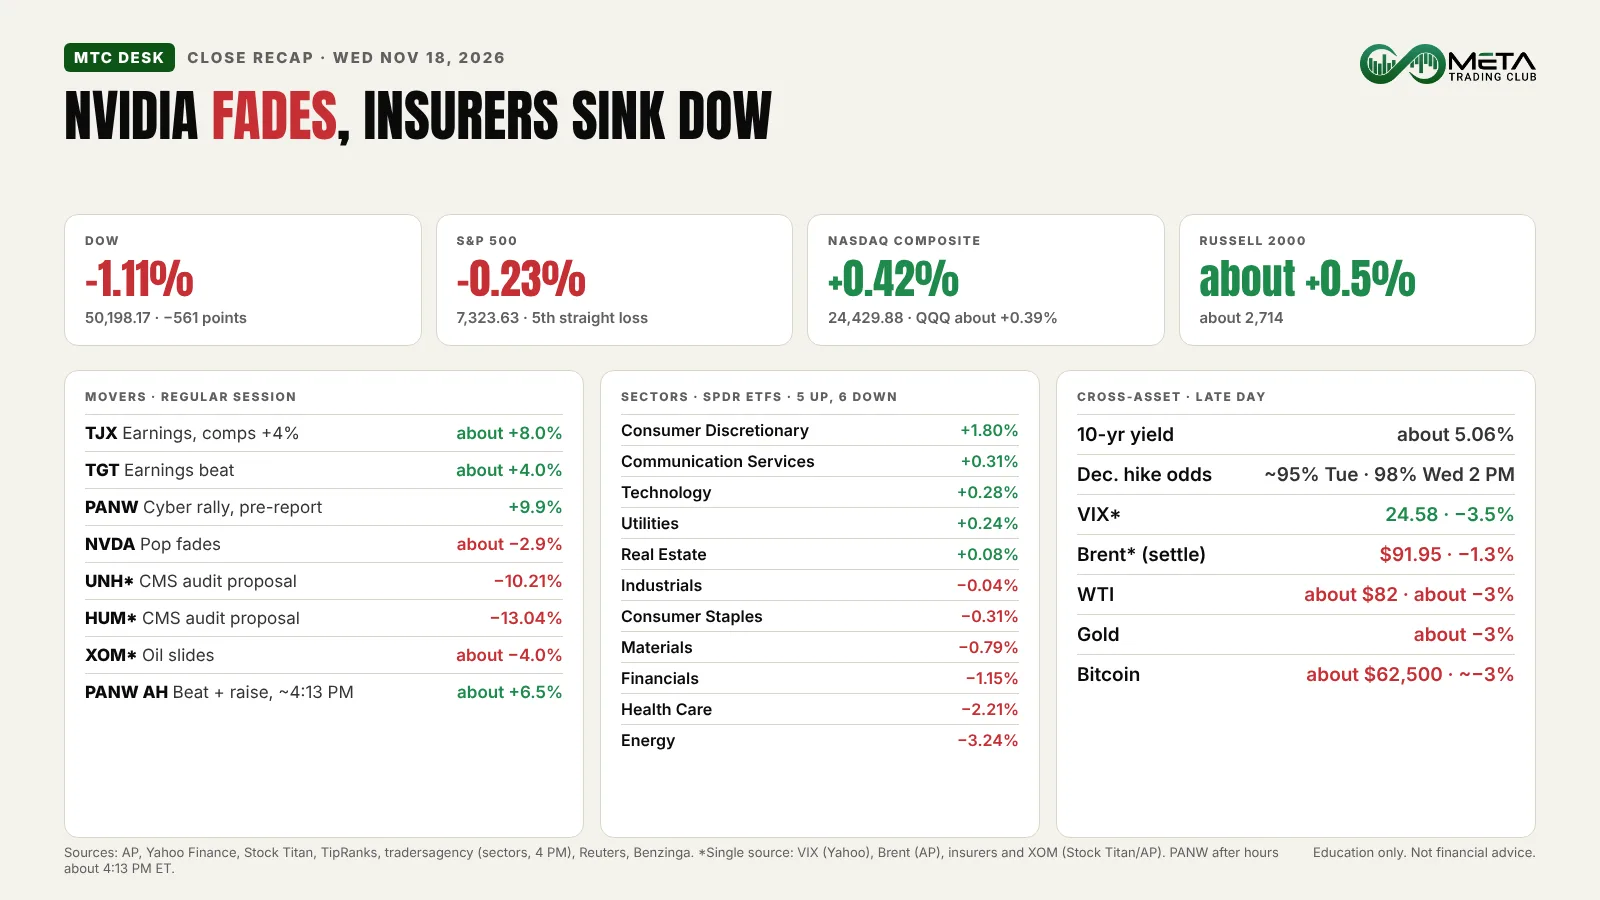
The Dow fell 1.11% (561 points) to 50,198.17 and the S&P 500 slipped 0.23% to 7,323.63, its fifth straight loss and the longest losing streak since June (AP). The Nasdaq Composite rose 0.42% to 24,429.88 and the Russell 2000 gained about 0.5% (AP; Yahoo Finance; tradersagency).
Retailers carried the gainers: TJX rose about 8% and Target about 4% on earnings (AP; Stock Titan). The FOMC minutes at 2:00 PM ET leaned hawkish, but the reaction was muted (XTB). After the bell, Palo Alto Networks beat and rose about 6.5% at about 4:13 PM ET (Stock Titan).
The Closing Bell
Index levels are from AP, checked against Yahoo Finance. ETF changes are from Stock Titan; our usual official ETF price feed was not reachable tonight, so SPY and QQQ levels are approximate.
| Index | Close | Change | ETF |
|---|---|---|---|
| Dow Jones | 50,198.17 | −1.11% (−561.25 points) | — |
| S&P 500 | 7,323.63 | −0.23% (−16.90) | SPY about −0.30% |
| Nasdaq Composite | 24,429.88 | +0.42% (+101.50) | QQQ about +0.39% |
| Russell 2000 | about 2,714 | about +0.5% | — |
The shape of the day: stocks opened higher on Nvidia, sold off within the first half hour, hit their lows in the late morning, bounced back to about flat around lunch and drifted between small gains and losses into the close (AP; Yahoo Finance; Reuters).
Nvidia Rally Fades: What Drove the Day
Nvidia gave back its opening pop and closed about −2.9% (AP; Stock Titan). The numbers were strong, but Reuters quoted NewEdge Wealth’s Jay Peters: the question is “what the company may look like in 3-5 years without a visionary leader like Jensen.” Micron went from about +1.5% to about −1% (AP). Our Tuesday close recap has the full Nvidia report.
Health insurers sank the Dow. The Centers for Medicare & Medicaid Services proposed a Medicare Advantage audit rule. UnitedHealth fell 10.21%, Humana 13.04%, Elevance 7.63% and Centene 7.06% (Stock Titan). Health Care was the second-worst sector at −2.21%.
Energy was the worst sector at −3.24% as oil fell after bigger-than-expected US crude and fuel inventory builds (Yahoo Finance; Stock Titan). Exxon Mobil and Chevron each lost about 4% (AP).
Retail and gaming led. TJX rose about 8% after comparable sales grew 4%, and Target about 4% after an earnings beat and a higher sales outlook (AP; Stock Titan). Take-Two gained 6.2% on the GTA VI rollout (AP). Palo Alto Networks rose 9.90% ahead of its report as cyber stocks rallied (Stock Titan).
Sectors: Discretionary Up, Energy Down
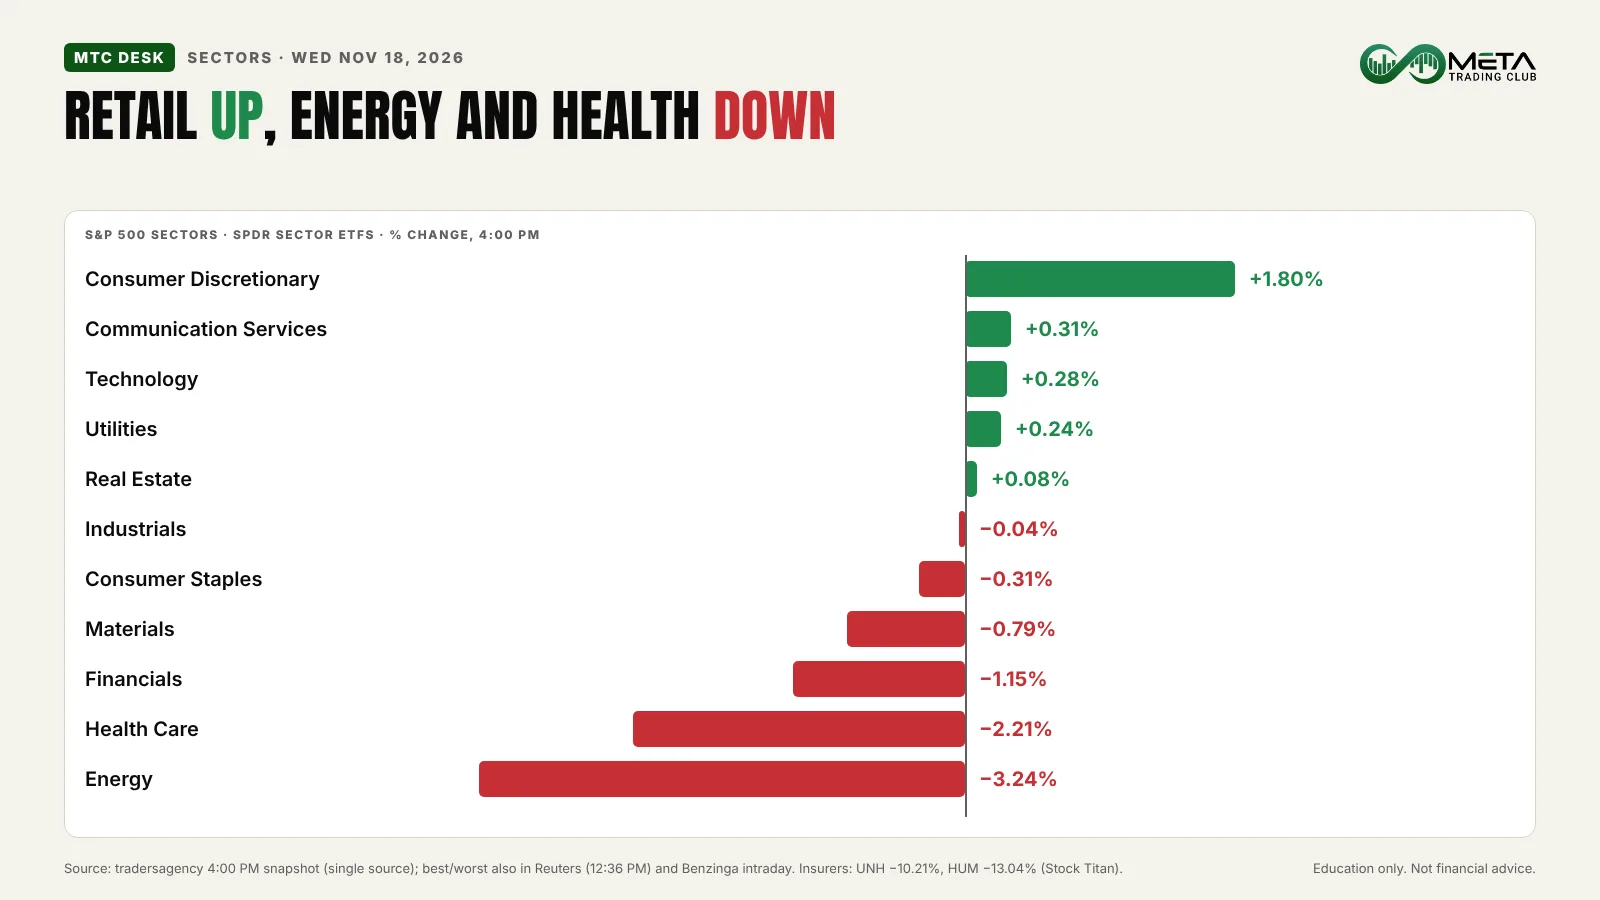
Five of 11 sectors rose at the 4:00 PM snapshot (tradersagency; single source, with the same leaders and laggards in Reuters and Benzinga during the day). Consumer Discretionary led at +1.80%, then Communication Services +0.31%, Technology +0.28%, Utilities +0.24% and Real Estate +0.08%. Industrials slipped 0.04%, Staples 0.31%, Materials 0.79% and Financials 1.15%. Health Care (−2.21%) and Energy (−3.24%) were the worst.
Rates, Commodities and Crypto
| Asset | Level | One line |
|---|---|---|
| 10-year Treasury yield | about 5.06% | Down about 3–4 basis points from 5.10% (AP) |
| December hike odds | about 95%–98% | CME FedWatch about 95% (Tue midday, Reuters); LSEG 98% (about 2 PM ET Wed, TipRanks) |
| Dollar index | about 103.8 | Highest since April 2025 (Benzinga, afternoon; single source) |
| Brent crude | $91.95 (−1.3%) | Settle (AP) |
| WTI crude | about $82 (about −3%) | Bigger-than-expected US inventory builds (Yahoo Finance; Stock Titan) |
| Gold | about −3% | Lowest in more than a year (Yahoo Finance; Bloomberg) |
| Bitcoin | about $62,500 | About −3% (Yahoo Finance; Bloomberg) |
| VIX | 24.58 | Yahoo Finance |
Economic Data Today
| Time (ET) | Release | Consensus | Prior | Actual |
|---|---|---|---|---|
| 8:30 AM | Housing starts (Oct) | 1.23M–1.27M | 1.191M (revised) | 1.309M |
| 2:00 PM | FOMC minutes (Oct 27–28 meeting) | — | — | Almost all see more hikes as likely |
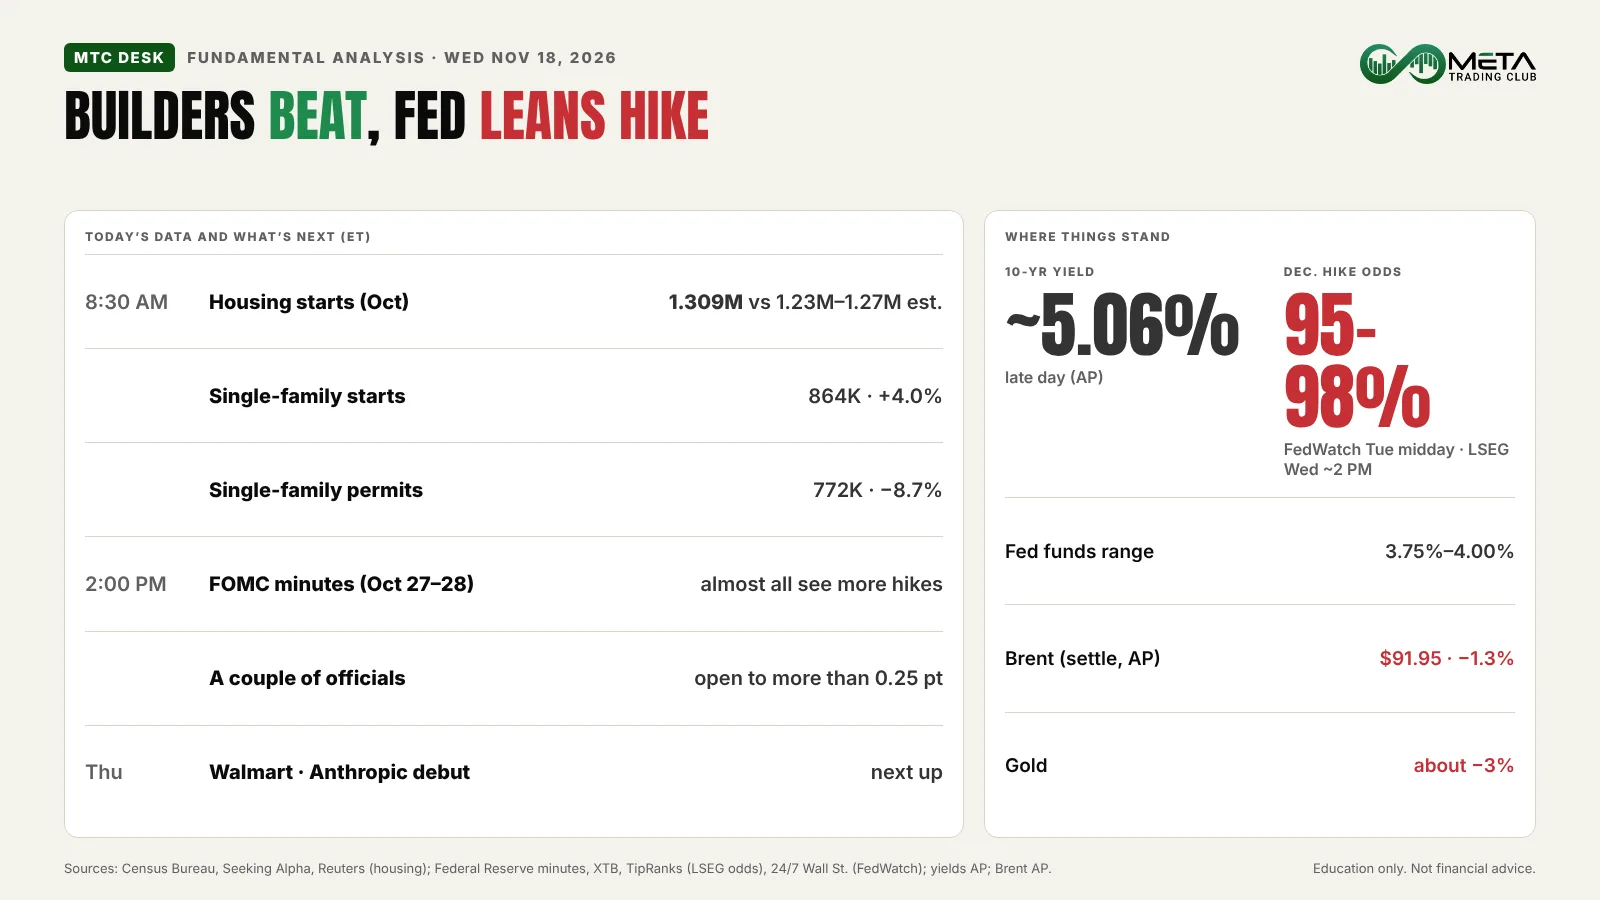
Builders started more homes than expected. Housing starts rose 9.9% to a 1.309 million annual rate, above the 1.23 million (Seeking Alpha) to 1.27 million (Trading Economics) forecasts (Census). Single-family starts rose 4.0% to 864,000, but single-family permits fell 8.7% to 772,000 (Census; Reuters), a softer sign for the months ahead.
The FOMC minutes from the October 27–28 meeting, when the Fed held at 3.75%–4.00% with two officials voting for a hike, said almost all participants saw further increases as likely appropriate. A couple said a move bigger than a quarter point could be considered in December if inflation data are unfavorable (Federal Reserve). XTB called the reaction calm, since a December hike is already priced.
After the Bell: Palo Alto Networks Beats and Raises
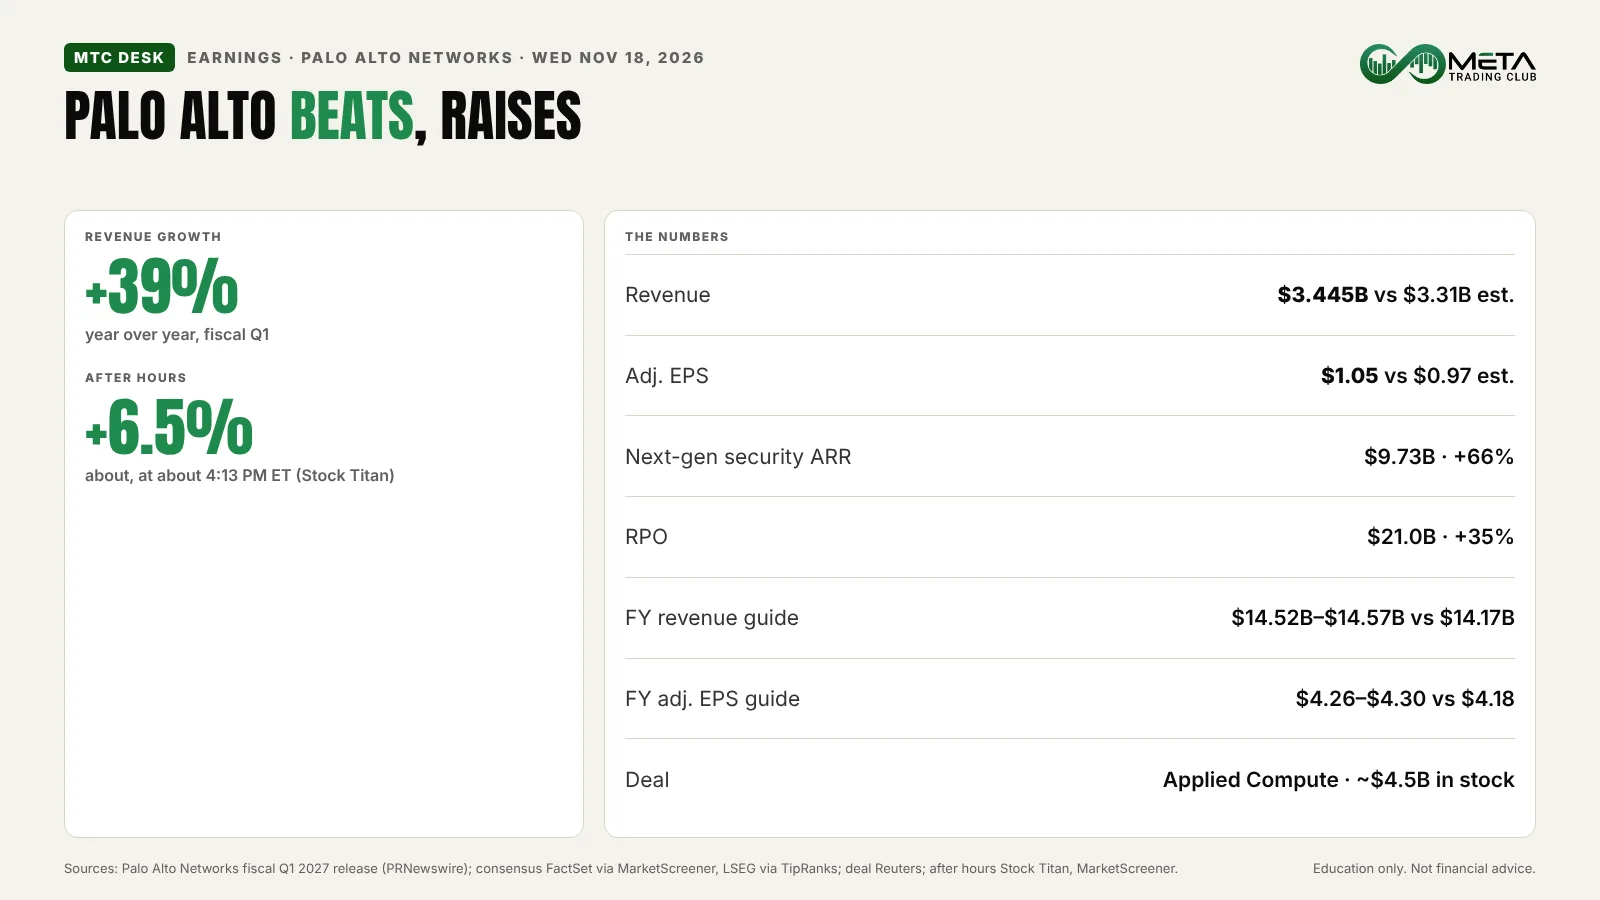
Palo Alto Networks (PANW) reported revenue of $3.445 billion, up 39%, against $3.31 billion expected (company release; FactSet via MarketScreener). Adjusted EPS was $1.05 against $0.97. Next-generation security ARR, its recurring subscription revenue, grew 66% to $9.73 billion.
It raised its full-year revenue guide to $14.52–$14.57 billion against about $14.17 billion expected, and agreed to buy Applied Compute in an all-stock deal valued at about $4.5 billion (Reuters). The stock rose about 6.5% at about 4:13 PM ET (Stock Titan) after a 9.90% gain in the regular session. Everpure (formerly Pure Storage) also reported after the close; its stock move was not confirmed tonight.
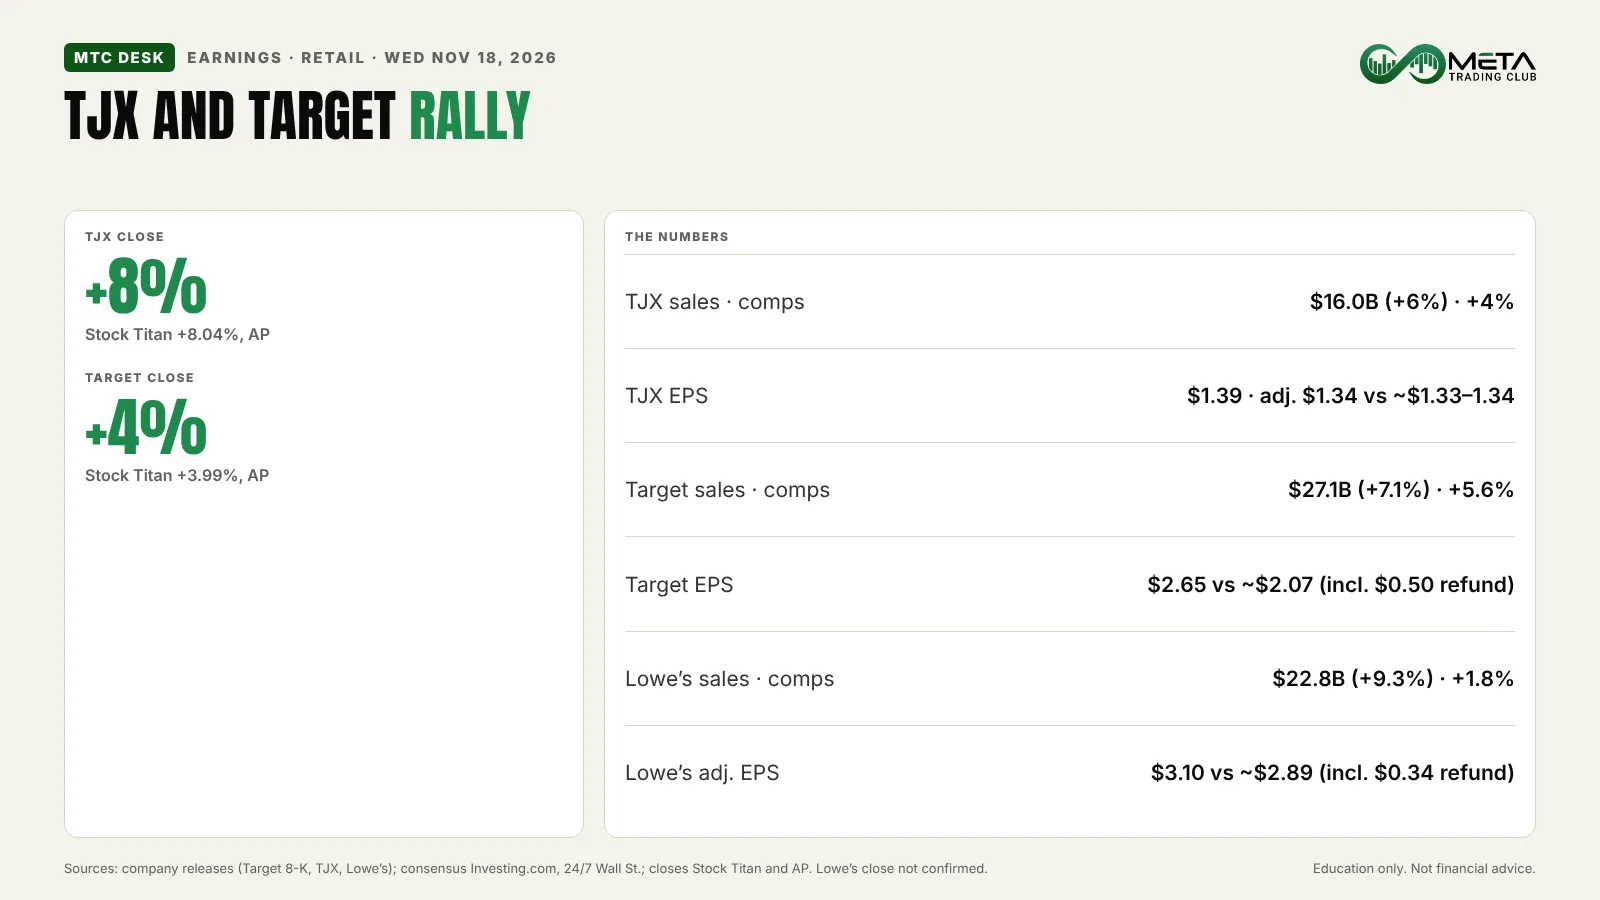
Before the open: TJX posted sales of $16.0 billion (+6%), comparable sales +4% and adjusted EPS of $1.34. Target earned $2.65 a share against about $2.07 expected, including a $0.50 tariff refund, with comparable sales up 5.6%. Lowe’s earned an adjusted $3.10, including a $0.34 refund, on $22.8 billion in sales and raised its sales outlook (company releases; Investing.com; Startup Fortune). Our premarket brief covered them before the open.
Setup Review and What to Watch Next
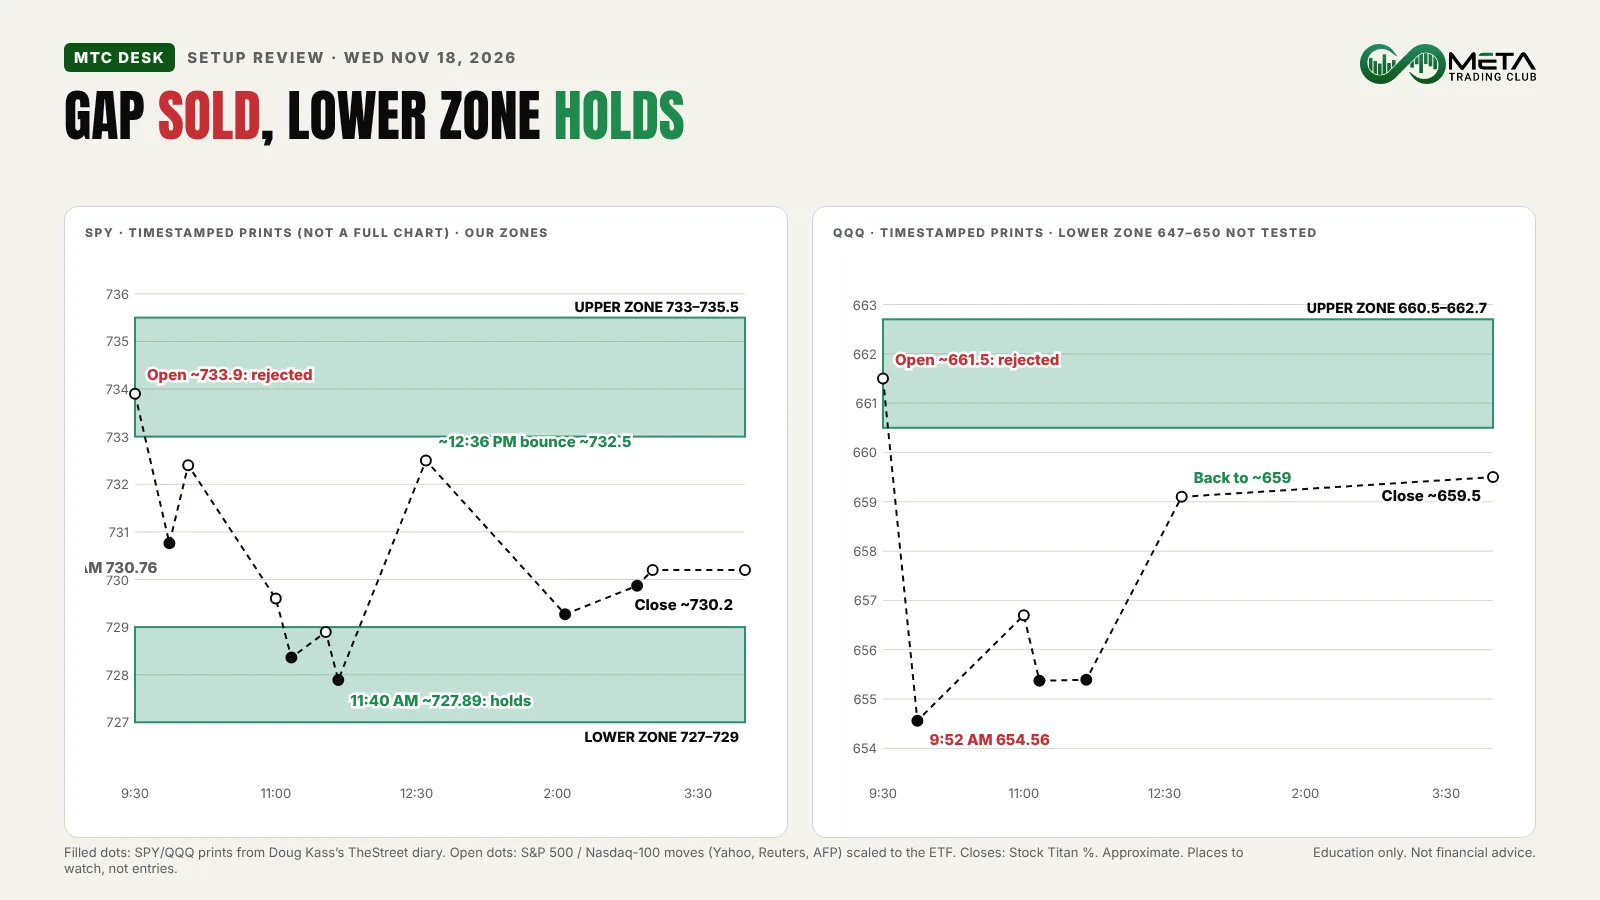
How our morning Zones did. Our data feed for a full intraday chart was blocked tonight, so these prices are timestamped prints (Doug Kass, TheStreet) and index moves (Yahoo Finance; Reuters), all approximate. SPY opened about 733.9, inside its 733–735.5 Upper Zone, and was rejected to about 730.76 by 9:52 AM. Late in the morning it reached the 727–729 Lower Zone (about 727.89 at 11:40 AM), held above Tuesday’s 727.00 low and bounced to about 732.5 by 12:36 PM; an afternoon dip held too. QQQ opened inside its 660.5–662.7 Upper Zone and was rejected to about 654.56; its 647–650 Lower Zone was not tested.
Honest grade: both Upper Zones gave a rejection, and the SPY Lower Zone gave a reaction and a confirmation. For the second day, a Zone that broke on Tuesday acted as the ceiling, and a strong earnings number did not change that.
Thursday’s Zones to watch for a reaction: SPY 733–735.5 and 727–729, and QQQ 660.5–662.7 and 654–656 (Wednesday’s low area). They come from prints, not a full chart, so the morning brief will re-check them. Our guide to bull vs bear markets explains why a five-day losing streak in the S&P 500 doesn’t change the bigger trend on its own; our Monday close recap covers the chip sell-off.
Thursday: Walmart before the open, Anthropic expected to start trading on Nasdaq (it reportedly priced at $83 a share, above its $70–$78 range, per Bloomberg; the company has not confirmed it), and Intuit, Ross Stores, Keysight and Gap after the close. Risks: a sloppy open around the Anthropic debut, more pressure on insurers, and hike-size talk with the 10-year near 5%.
FAQ
Nvidia opened up about 2.5% after beating estimates and guiding fourth-quarter revenue to $130 billion, then closed about 2.9% lower, its fifth straight loss (AP; Stock Titan). Reuters quoted investors worried about the company’s future without Jensen Huang, whose exit as CEO came last week.
The Centers for Medicare & Medicaid Services proposed a new audit rule for Medicare Advantage plans. UnitedHealth fell 10.21%, Humana 13.04%, Elevance 7.63% and Centene 7.06% (Stock Titan), and the drop helped pull the Dow down 561 points.
The minutes of the October 27–28 meeting said almost all officials saw further rate increases as likely appropriate, and a couple said a move bigger than a quarter point could be considered in December if inflation data are unfavorable (Federal Reserve). Markets took it calmly; December hike odds were about 95% (CME FedWatch, Tuesday midday) to 98% (LSEG, about 2 PM ET Wednesday).
Walmart reports Thursday before the open, Anthropic is expected to start trading on Nasdaq Thursday, and Intuit, Ross Stores, Keysight and Gap report after Thursday’s close. Friday is monthly options expiration.
Sources: AP (via KDH News); Yahoo Finance; Stock Titan; TipRanks; Reuters (via MarketScreener); Bloomberg (via Swissinfo and Yahoo Finance); Benzinga (via TradingView); tradersagency; XTB; Doug Kass, TheStreet; Federal Reserve FOMC minutes; Census Bureau; Seeking Alpha; Palo Alto Networks fiscal Q1 2027 release (PRNewswire); MarketScreener (FactSet); TJX, Target (8-K) and Lowe’s releases; Investing.com; 24/7 Wall St. After-hours, ETF and commodity levels are approximate and carry their time. Featured image: color-graded from a photo of an NVIDIA H100 GPU by Geekerwan (CC BY 3.0, Wikimedia Commons).
Education only. Not financial advice.