Monday, November 16, 2026 · 5:00 PM ET · Shahryar Rahmani, MTC Desk
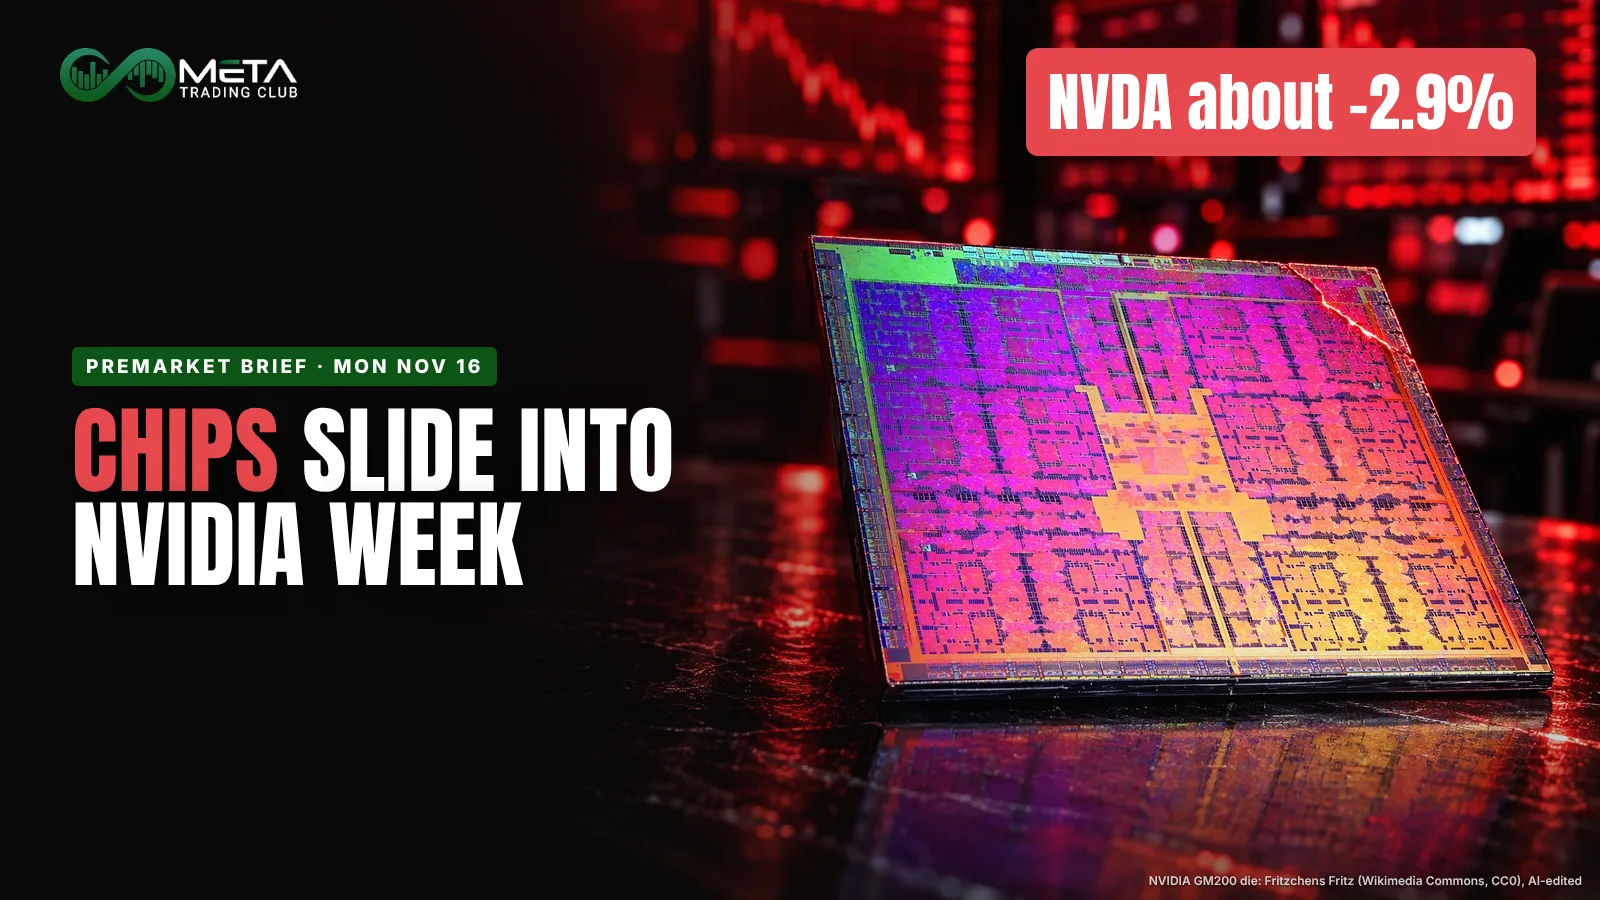
Chip stocks sell off a day before Nvidia reports, and the Nasdaq drops 2.49%. Micron fell 7.62%, Intel −7.07%, AMD −5.58% and Nvidia −4.12%, and the chip ETF (SMH) lost 5.11%. Investors grew cautious on chip valuations and AI spending ahead of Nvidia’s first report since Jensen Huang left as CEO (Motley Fool; Yahoo Finance).
Read the episode
Hey, I’m Shah, your host, and this is MTC Radio.
Okay, so chips dragged the whole market down today, and it’s all about Nvidia. Nvidia reports tomorrow after the close, and nobody wanted to hold chips going into it. Micron was down more than seven and a half percent, Intel about seven, AMD more than five and a half, and Nvidia itself about four. The chip group as a whole lost about five percent.
Now, Nvidia’s report tomorrow is the first one since Jensen Huang left as CEO. And a CNBC report today said the board isn’t considering bringing him back. And on top of that, people are just nervous about how expensive chip stocks got and how much money companies are pouring into data centers. So they sold first and decided to ask questions after the report.
And it didn’t stay in chips. Alphabet was down about four percent, Amazon down more than three. The Nasdaq lost about two and a half percent, the S&P 500 almost two, and the Dow dropped more than seven hundred points. Only two of the eleven sectors finished green, staples and utilities, and both barely. And the part I didn’t like, the S&P and the Nasdaq both closed right near the lows of the day. The VIX, the fear gauge, jumped almost twenty percent, to about twenty three.
There were a couple of green spots. Tyson Foods was up almost nine percent, because people liked its outlook for next year more than they hated the earnings miss. And after the bell, AECOM was up about seven percent, as of about four thirty. They beat on earnings, their backlog hit a record, about twenty eight billion dollars, and they gave a first look at next year that people seem to like.
On the data side, the New York factory survey fell to about eight, from about twenty five last month, so factories there are still growing, just a lot slower. Up here in Canada, inflation held at three point one percent, a touch cooler than expected. And the ten-year yield stayed above five percent, around five point one two.
Now, this morning on Spy, our lower zone was seven forty five to seven forty eight. Spy opened right inside it and bounced to about seven fifty. So we got a reaction. But it never confirmed, it never pushed higher. Around ten o’clock it broke below the zone, came back up to test it from underneath until about noon, failed right there, and then slid all afternoon to about seven thirty eight. Q Q Q did the exact same thing around its six sixty seven to six seventy one and a half zone. So, reaction, yes. Confirmation, no. And once that zone broke, it turned into the exact place the sellers came back in.
In the live room I took Google puts right after the open, took some off when it broke two eighty eight, and closed the rest on a trailing stop around ten thirty. Closed green. Once you’ve taken some off, your stop is in profit, and holding the rest gets a lot easier.
For tomorrow on Spy, I’m watching seven forty five to seven forty seven and a half up top, that’s today’s broken zone, and seven thirty three to seven thirty five and a half below. On Q Q Q, six sixty six and a half to six sixty eight and a half above, and six fifty four to six fifty six below. We’ll see how price reacts at those. Retail sales come out at eight thirty in the morning, Home Depot reports before the open, and then Nvidia after the close. Big day.
So yeah, that’s what I’m watching. If you want to trade it with us, we’re live tomorrow morning in the community, and we go live four days a week. Join us if you want. See you there.
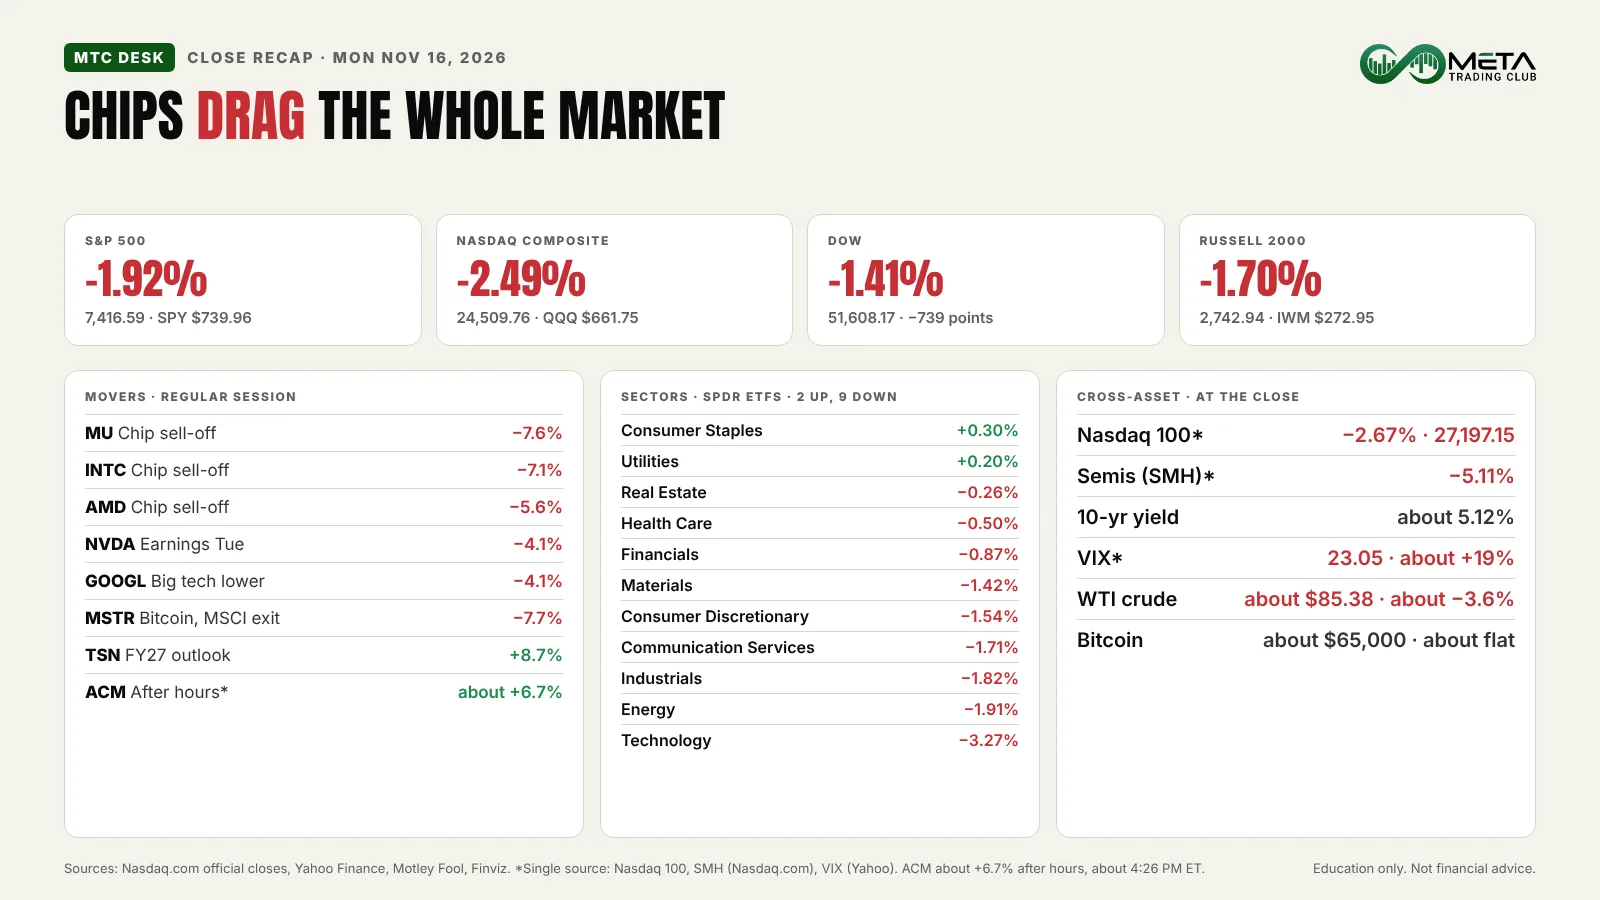
The S&P 500 lost 1.92% to 7,416.59 and the Dow fell 739 points (−1.41%) to 51,608.17 (Yahoo Finance; Motley Fool). Only two of 11 sectors rose, both indexes closed near their lows, and the VIX jumped about 19% to 23.05.
Nvidia reports Tuesday after the close. A CNBC report said its board is not considering bringing Huang back (via Yahoo Finance), and Anthropic’s IPO is expected Thursday. After the bell, AECOM rose about 6.7% at about 4:26 PM ET on an earnings beat and a record backlog.
The Closing Bell
Index levels are from Yahoo Finance, checked against the Motley Fool and Nasdaq.com; ETF closes are official 4:00 PM ET prints from Nasdaq.com.
| Index | Close | Change | ETF |
|---|---|---|---|
| S&P 500 | 7,416.59 | −1.92% (−145 points) | SPY $739.96 (−1.91%) |
| Nasdaq Composite | 24,509.76 | −2.49% (−627 points) | QQQ $661.75 (−2.67%) |
| Nasdaq 100 | 27,197.15 (Nasdaq.com) | −2.67% | |
| Dow Jones | 51,608.17 | −1.41% (−739 points) | DIA $515.73 (−1.42%) |
| Russell 2000 | 2,742.94 | −1.70% (−48 points) | IWM $272.95 (−1.65%) |
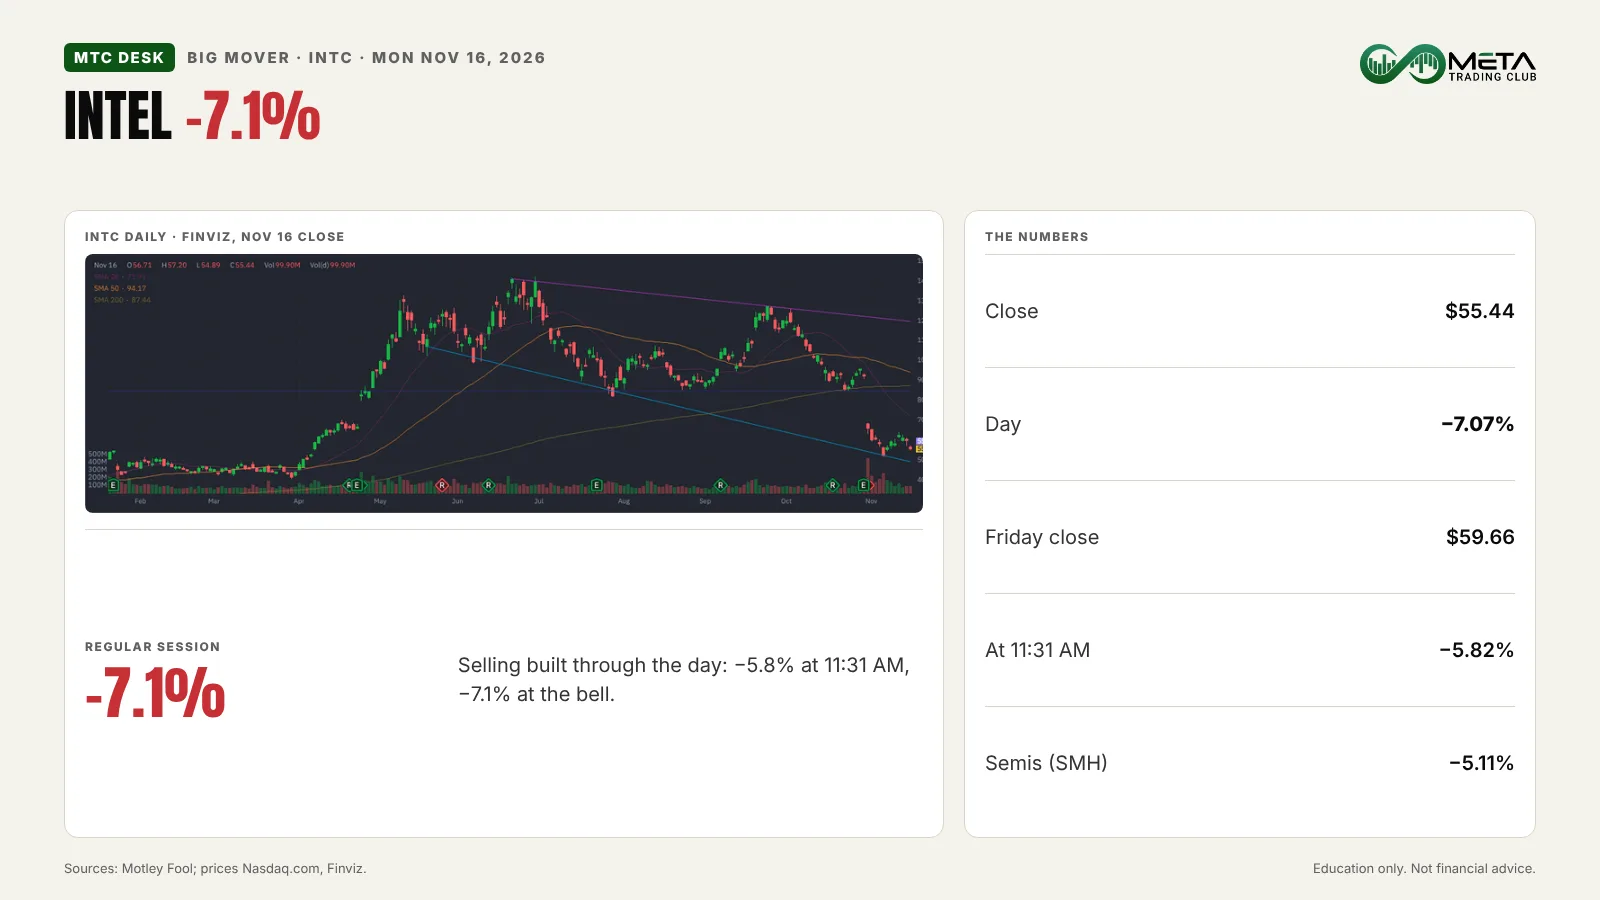
The shape of the day: at 11:31 AM the Nasdaq was down 1.34% and the S&P 500 0.99% (Motley Fool). Selling kept building, and the S&P 500 made its low of 7,400.15 at about 2:47 PM (Yahoo Finance).
Chip Stocks Sell Off: What Drove the Day
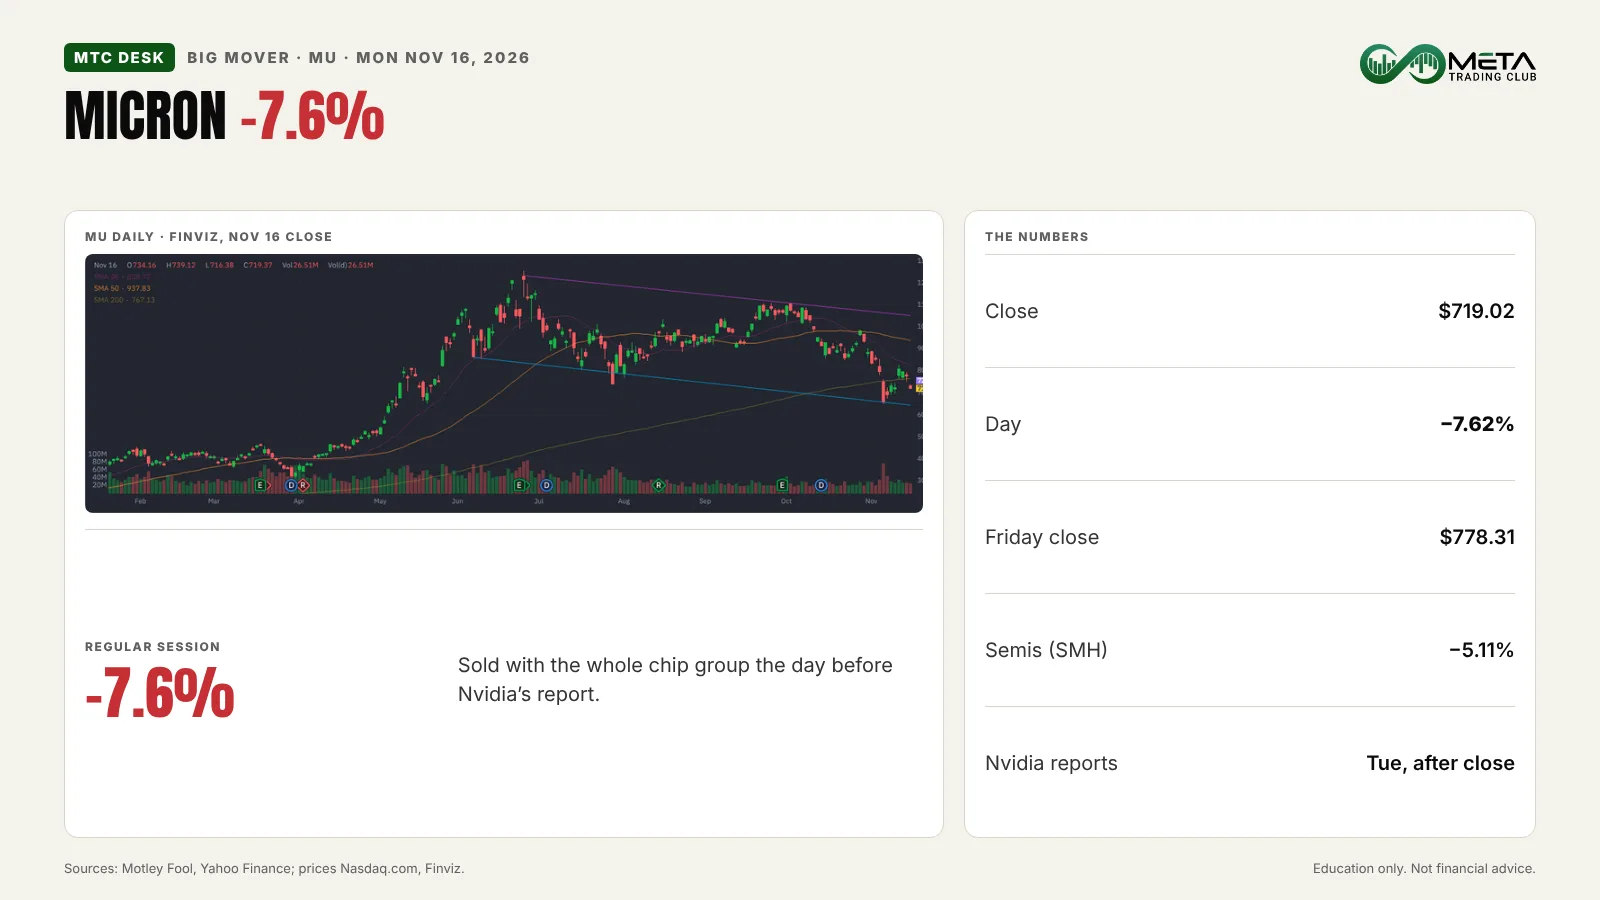
Micron closed at $719.02, down 7.62% from $778.31 (Nasdaq.com; Finviz). It sold with the group. Intel fell 7.07% to $55.44 after being down 5.82% at 11:31 AM, so the selling built into the close. AMD lost 5.58% and Broadcom 3.92%. AI-infrastructure names fell too: Nebius −7.55%, Dell −6.95%, Super Micro −6.85% and CoreWeave −6.12% (Nasdaq.com).
Nvidia fell 4.12% to $156.14. A CNBC report said the board is not considering bringing Jensen Huang back as CEO, after the Financial Times reported he had discussed a possible return (via Yahoo Finance). The Motley Fool says investors are cautious on chipmaker valuations and AI infrastructure spending going into the report, and Yahoo Finance also cites tighter US restrictions on overseas access to advanced chips. Our Friday close recap covers the chip selling at the end of last week.
Big tech followed: Alphabet −4.07%, Amazon −3.34%, Tesla −2.69%, Meta −2.38%, Microsoft −1.12% and Apple −0.98% (Nasdaq.com; Motley Fool). Strategy (MSTR) fell 7.70% as Bitcoin touched its lowest level since July and on its removal from MSCI’s indexes (Motley Fool).
The green names. Tyson Foods jumped 8.74% as its fiscal 2027 outlook outweighed a fourth-quarter earnings miss (Motley Fool; Schaeffer’s). Aramark rose 2.74% on its report day after trading about 5.4% lower at about 7:37 AM ET, while Baidu fell 5.37% (Nasdaq.com). Our guide to bull vs bear markets explains why one rough day does not change the bigger trend on its own.
Sectors: Only Two Rose
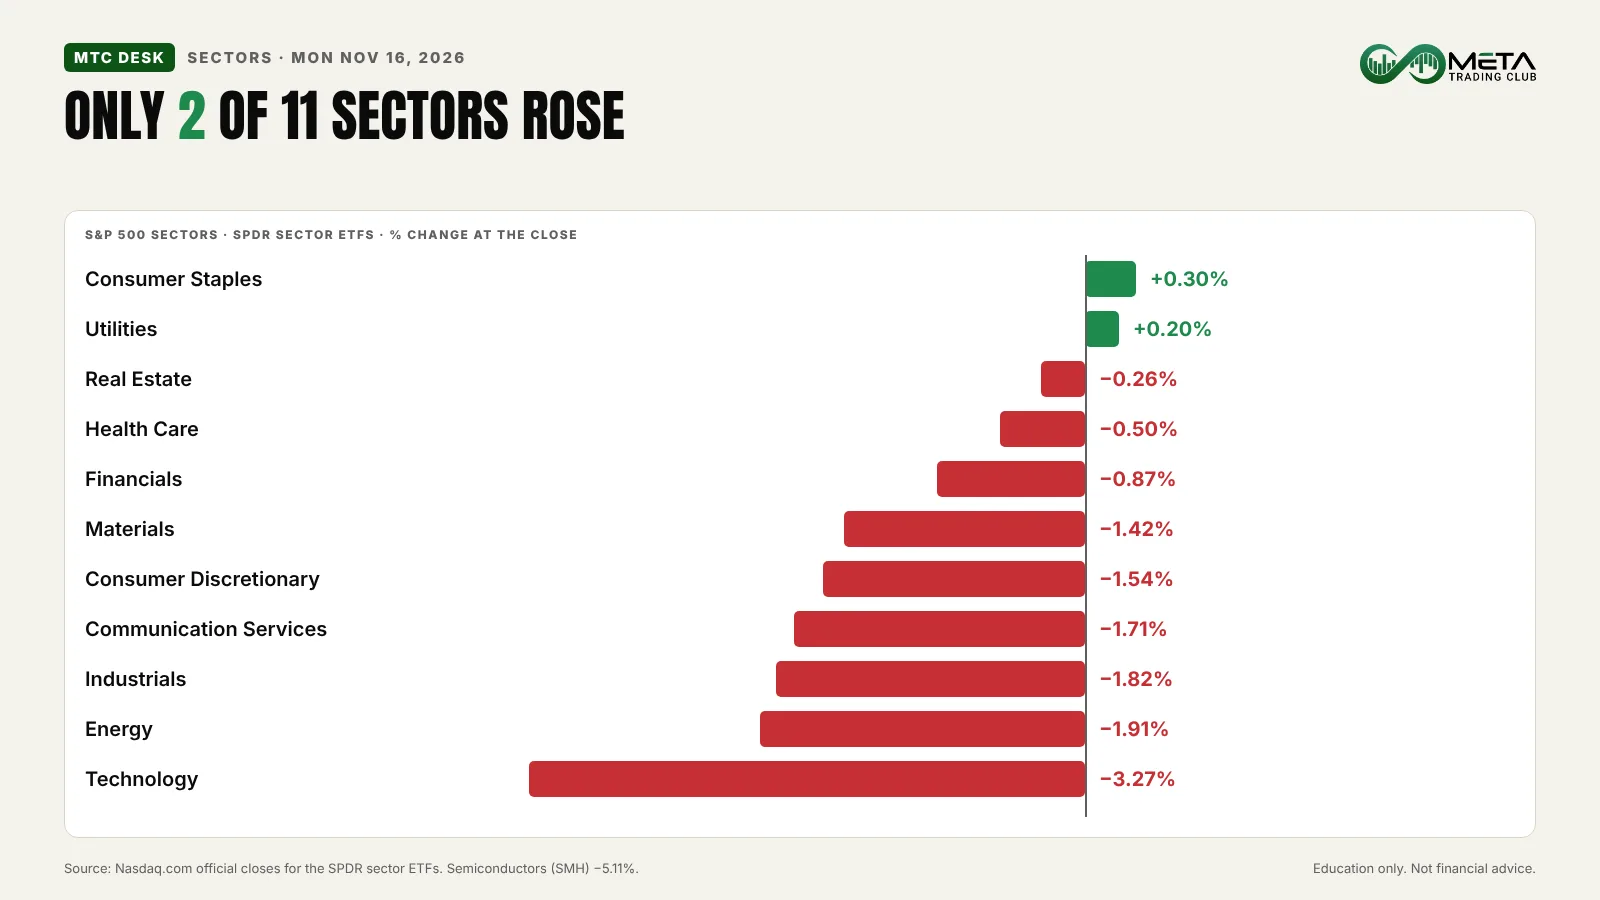
Consumer Staples (+0.30%) and Utilities (+0.20%) were the only sectors up. Real Estate fell 0.26%, Health Care 0.50% and Financials 0.87%; Materials −1.42%, Consumer Discretionary −1.54%, Communication Services −1.71%, Industrials −1.82% and Energy −1.91%. Technology was the worst at −3.27%, and semiconductors (SMH) −5.11%. Bank stocks dipped at midday as reports of bank app outages spiked (Yahoo Finance); JPMorgan closed −2.26% and Bank of America −1.78%.
Rates, Commodities and Crypto
| Asset | Level | One line |
|---|---|---|
| 10-year Treasury yield | about 5.12% | Yahoo Finance at the close; 5.15% at 11:31 AM (Motley Fool) |
| WTI crude | about $85.38 (about −3.6%) | Yahoo Finance; USO −3.81% (Nasdaq.com) |
| Gold | about $3,854 (about −0.8%) | Yahoo Finance; GLD −0.72% (Nasdaq.com) |
| Bitcoin | about $65,000 (about flat) | Yahoo Finance and Motley Fool, after its lowest level since July |
| VIX | 23.05 (about +19%) | Yahoo Finance |
| US dollar (UUP) | +0.20% | A little firmer (Nasdaq.com) |
Oil slid as shipments through the Strait of Hormuz keep recovering (Yahoo Finance). Cheaper oil and weaker factory data would usually help bonds, but the 10-year yield stayed above 5%. This morning, markets fully priced a December Fed rate hike (CME FedWatch via Reuters, 5:43 AM ET).
Economic Data Today
| Time (ET) | Release | Consensus | Prior | Actual |
|---|---|---|---|---|
| 8:30 AM | NY Fed Empire State manufacturing (Nov) | about 17.6–19 | 25.5 | 7.8 |
| 8:30 AM | Canada CPI (Oct) y/y | 3.2% | 3.1% | 3.1% |
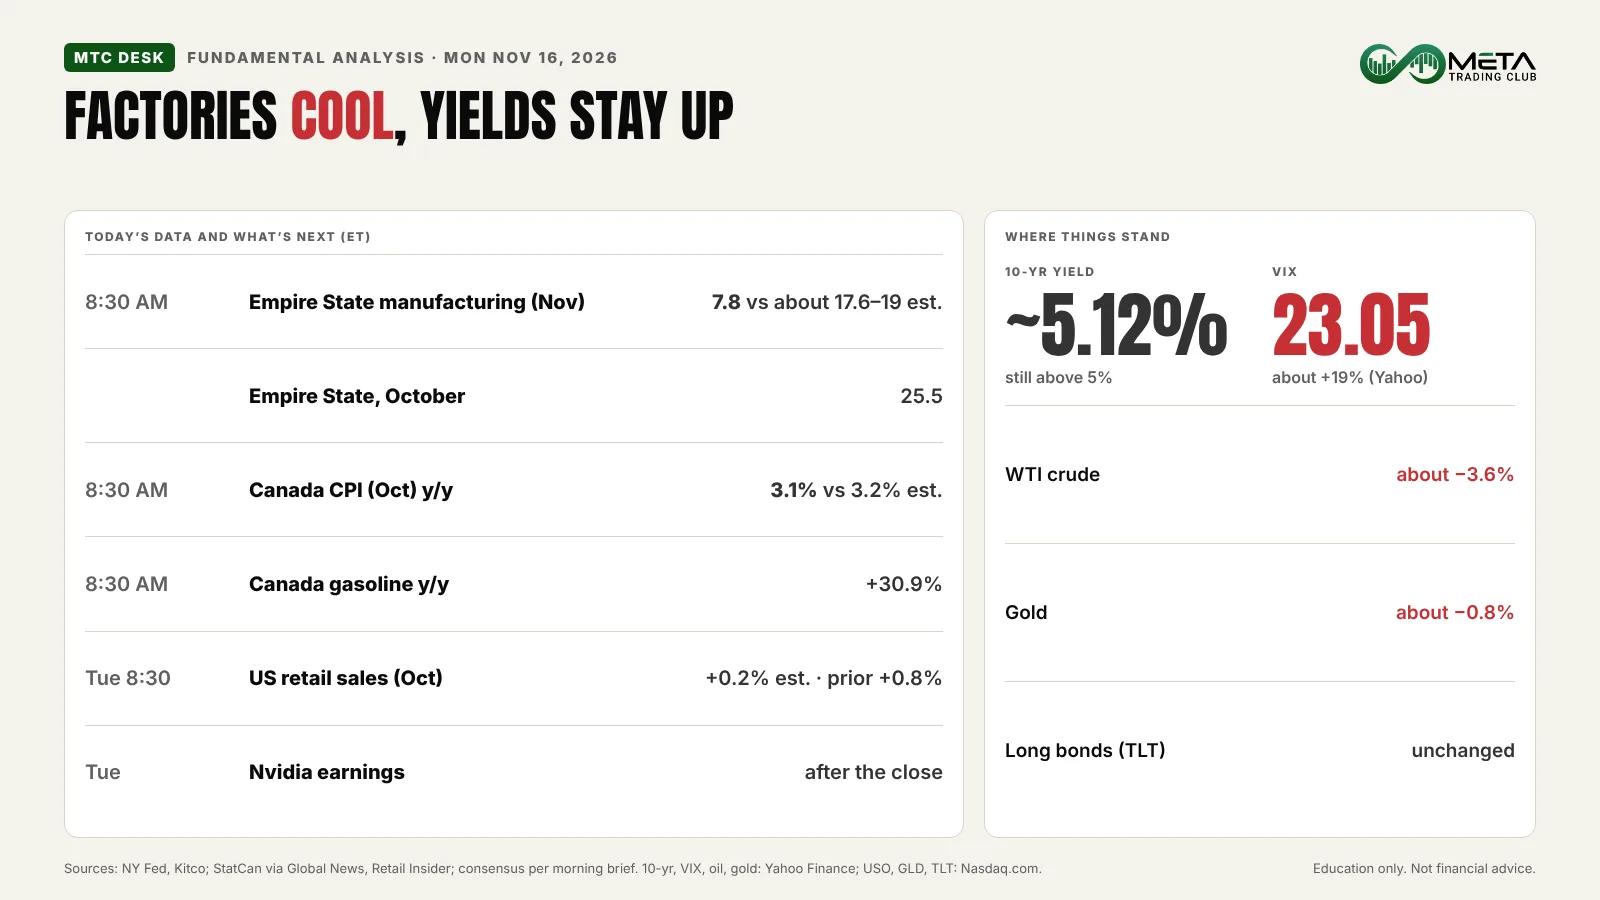
The Empire State index fell to 7.8 from 25.5, well below forecasts (NY Fed; Kitco): New York factories are still growing, but much more slowly. Canada’s inflation held at 3.1%, a touch below the 3.2% forecast, with gasoline up 30.9% from a year ago (StatCan via Global News and Retail Insider). It is the last CPI before the Bank of Canada decides on December 9.
After the Bell: AECOM Beats
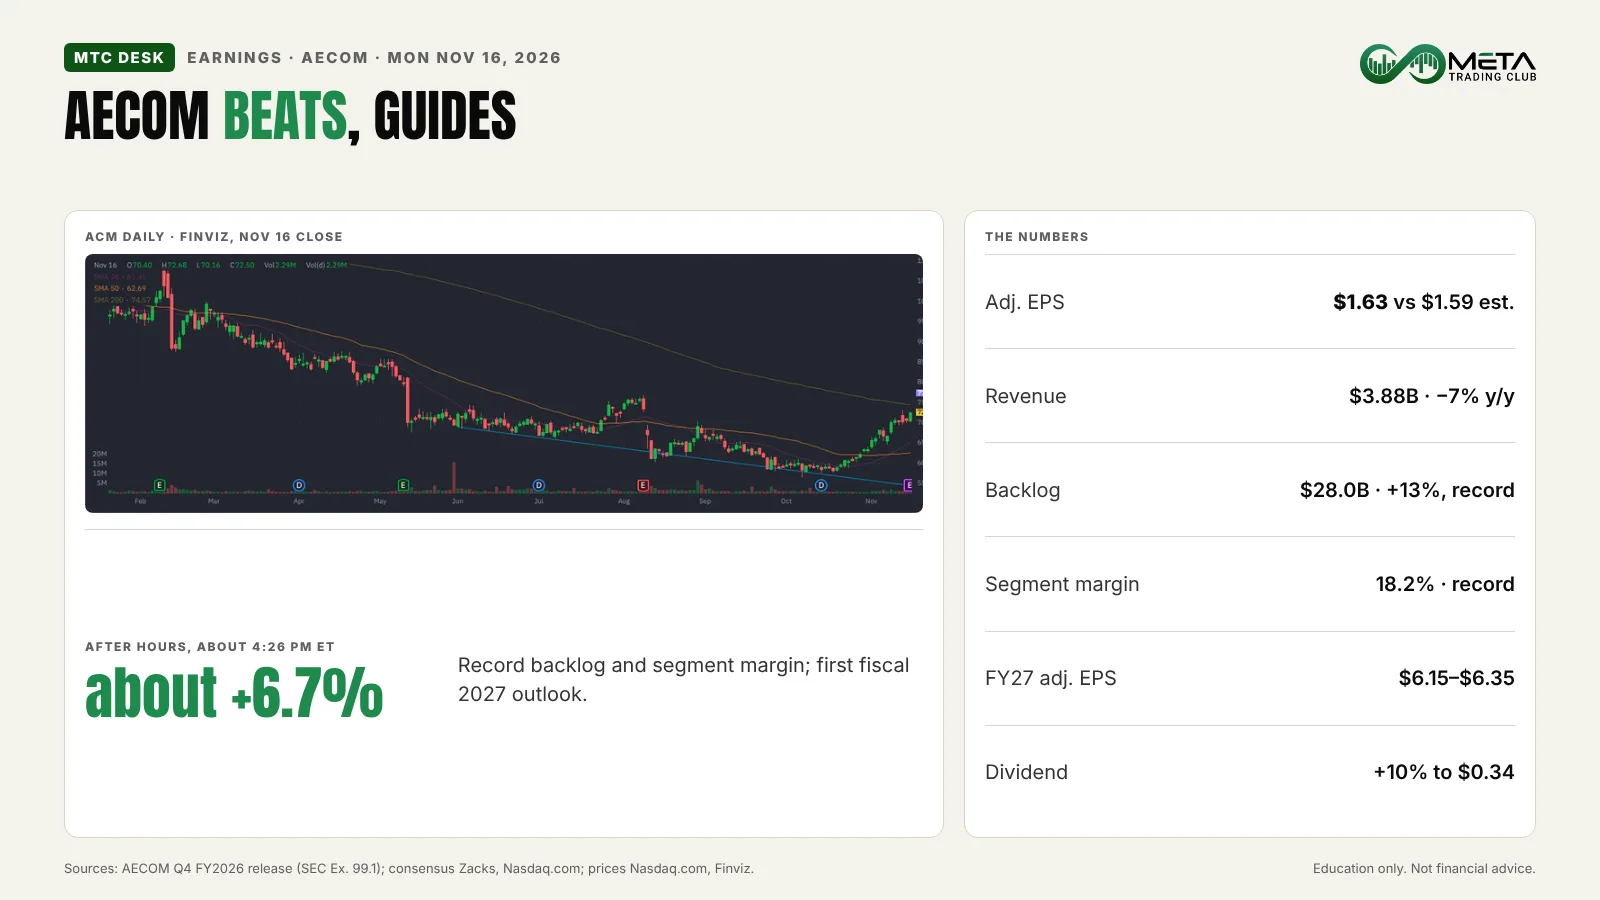
AECOM (ACM) rose about 6.7% at about 4:26 PM ET (Nasdaq.com; Finviz). Adjusted EPS was $1.63 against $1.59 expected (Zacks), backlog hit a record $28.0 billion (+13%), and segment margins set a record at 18.2%. Revenue fell 7% to $3.88 billion. It guided fiscal 2027 adjusted EPS to $6.15–$6.35 and raised its dividend 10% (company release). Nvidia was about 0.4% higher at about 4:23 PM ET.
Setup Review and What to Watch Next
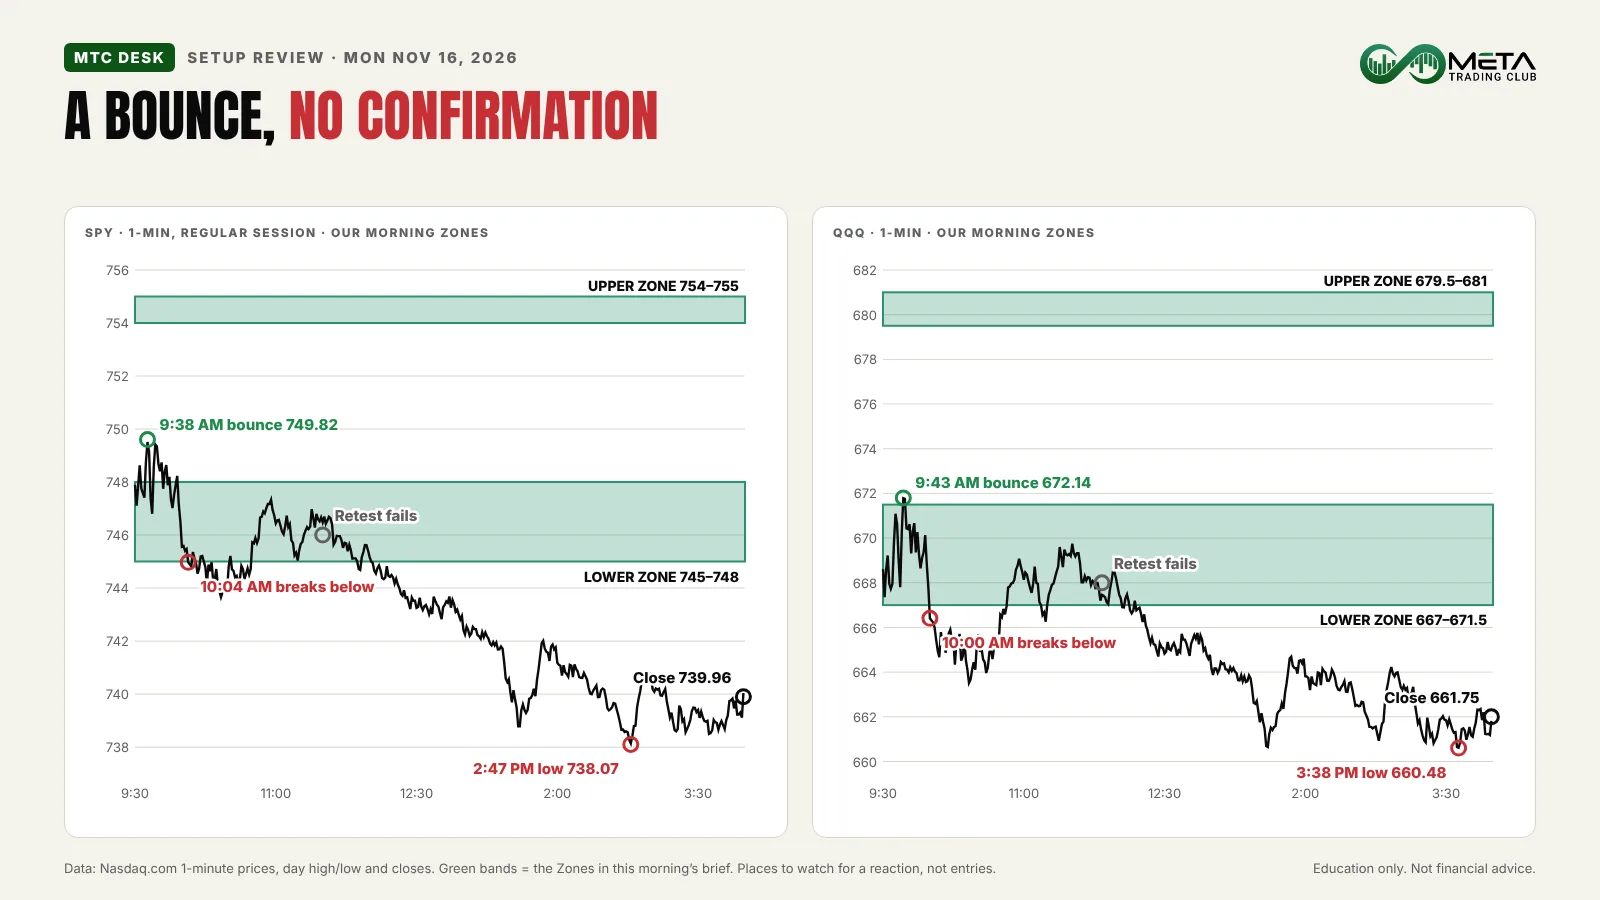
How our morning Zones did. In our premarket brief, SPY’s Lower Zone was 745–748. SPY opened about 747.89, inside it, and bounced to 749.82 by about 9:38 AM. That was a reaction, but it never confirmed. SPY broke below the Zone at about 10:04 AM, came back to about 745–746 until about noon, failed there and slid to 738.07 at about 2:47 PM, closing at 739.96. QQQ did the same around its 667–671.5 Zone: a bounce to 672.14, a break at about 10:00 AM, a failed retest near 668, and a low of 660.48 at about 3:38 PM. The Upper Zones were never tested. Honest grade: reaction yes, confirmation no. Once broken, the Zones became the place sellers stepped back in.
Tuesday’s Zones to watch for a reaction: SPY 745–747.5 (today’s broken Zone) and 733–735.5 (the November 5–6 closes), and QQQ 666.5–668.5 and 654–656. Our guide to using premarket data to prepare for the day shows how we build these Zones.
Tuesday: US retail sales for October at 8:30 AM ET (+0.2% expected, prior +0.8%), Home Depot before the open and Nvidia after the close (results about 4:20 PM, call 5:00 PM ET). Risks: a big move in either direction on Nvidia’s numbers, the 10-year staying above 5%, and more news on Nvidia’s leadership.
FAQ
Chip stocks fell a day before Nvidia’s earnings as investors grew cautious on chipmaker valuations and AI spending (Motley Fool). Micron fell 7.62%, Intel 7.07%, AMD 5.58% and Nvidia 4.12%, and the chip ETF (SMH) lost 5.11% (Nasdaq.com). Yahoo Finance also pointed to tighter US limits on overseas access to advanced chips.
Nvidia reports its quarterly results on Tuesday, November 17, 2026, after the market close, with results expected about 4:20 PM ET and the call at 5:00 PM ET. It is the company’s first report since Jensen Huang stepped down as CEO.
The Nasdaq Composite fell 2.49% to 24,509.76, the S&P 500 1.92% to 7,416.59 and the Dow 739.38 points, or 1.41%, to 51,608.17 (Yahoo Finance; Motley Fool). Only two of 11 S&P 500 sectors rose, and the VIX jumped about 19% to 23.05.
AECOM rose about 6.7% after hours at about 4:26 PM ET after reporting adjusted EPS of $1.63 against $1.59 expected, a record $28.0 billion backlog and a record segment margin. It guided fiscal 2027 adjusted EPS to $6.15–$6.35 and raised its dividend 10% (company release; Zacks).
Sources: Yahoo Finance; Motley Fool; Schaeffer’s Investment Research; Nasdaq.com official closes, day ranges and after-hours quotes; Finviz charts; AECOM Q4 fiscal 2026 release (SEC 8-K); Zacks; NY Fed; Kitco; Statistics Canada via Global News and Retail Insider. After-hours and commodity levels are approximate and carry their time. Featured image: AI-edited from an NVIDIA newsroom press photo of its headquarters.
Education only. Not financial advice.