Thursday, September 17, 2026 · 4:30 PM ET · MTC Market Close
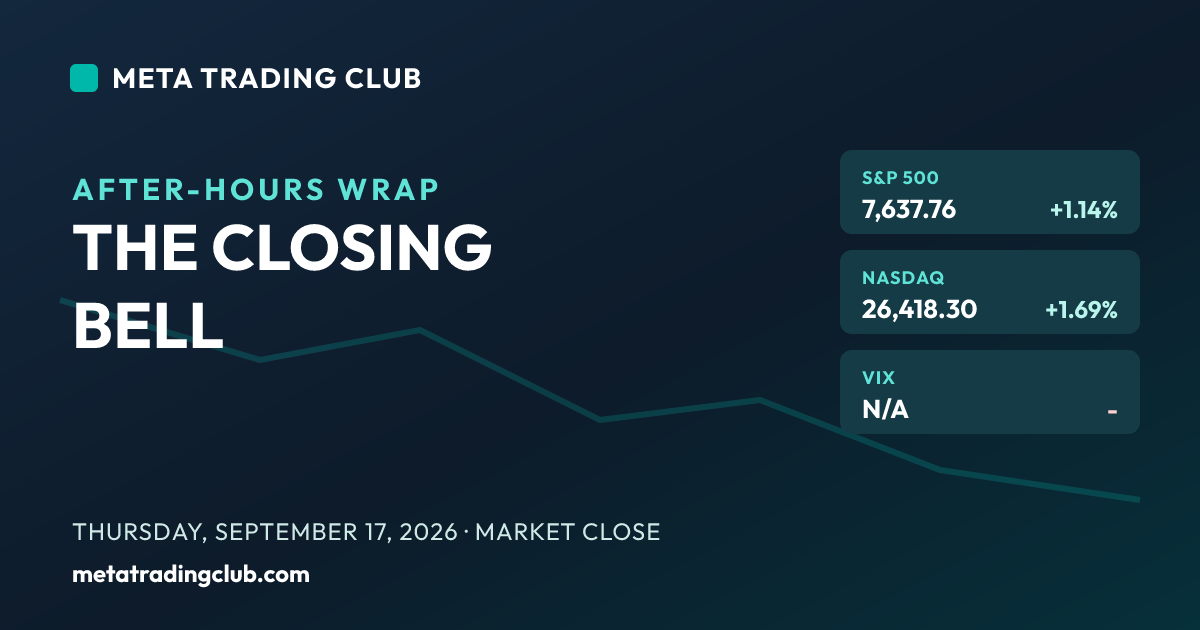
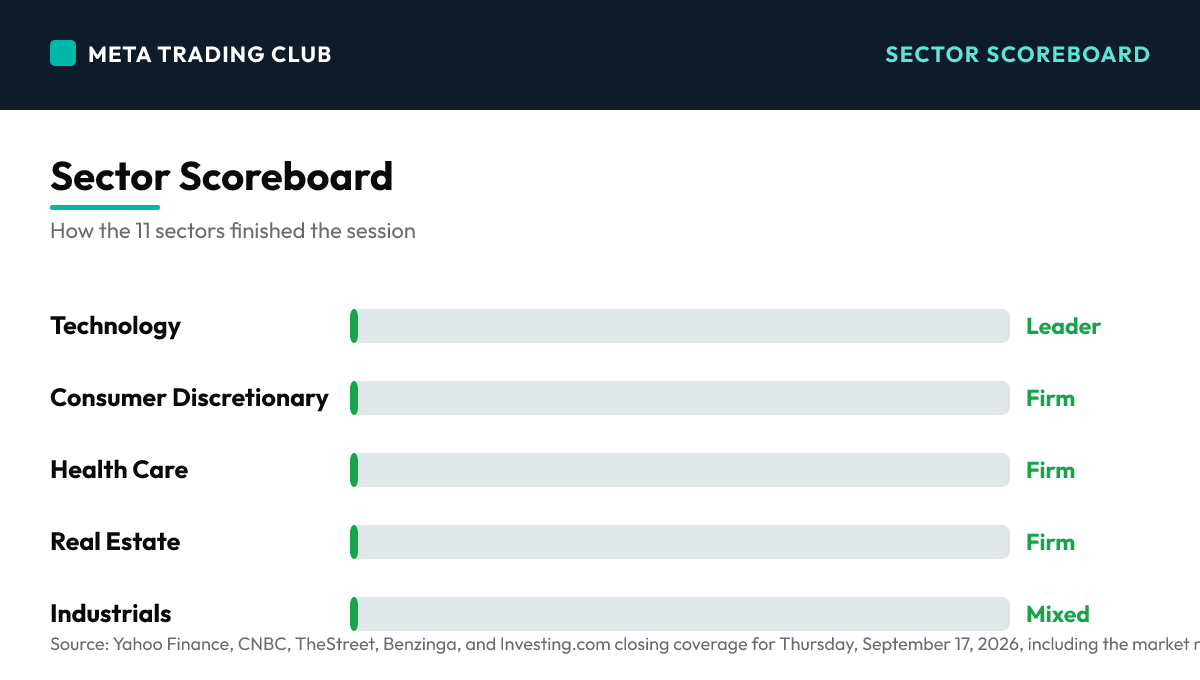
The stock market today did exactly what the bears warned it might not: it bought the dip the bond market handed it. One day after a hawkish Fed hike sank stocks and pushed the 10-year yield back above 5%, the two things that caused the selloff both relented. Treasury yields eased off their 2007 highs, snapping an eight-day rising streak, and oil slipped back under $101 as Saudi Arabia routed extra crude through Oman. That was all a beaten-up tape needed. The Nasdaq led, jumping 1.69% to 26,418.30, the S&P 500 rose 1.14% to 7,637.76, and the Dow added 316 points, or 0.61%, to 51,778.04. Small caps rejoined the party, with the Russell 2000 up about 1.1%, and breadth flipped clean, with seven of eleven sectors green and technology out front, up more than 2%. The engine names were specific and loud: Generac exploded roughly 21% on an Amazon data-center generator deal, Moderna jumped about 9% on positive cancer-vaccine data with Merck, and the AI-hardware complex, Hewlett Packard Enterprise and Intel, ran 7% each. Here is the tension into tomorrow. The rebound is real, but it stalled right under the line that framed the entire selloff: 7,700. Price closed at 7,637.76, just below the level the September 11 bounce failed to reclaim on the way down. Two witnesses also stayed home, financials finished red and the 10-year is still pinned near 5%, so the rate story is not resolved, it just paused. This is a relief rally until price proves otherwise, and the proof is 7,700. Reclaim it and the post-Fed flush was a shakeout; fail it and lose 7,600, and the tape is right back on 7,500. No alignment between a bounce and a reclaim, so no trade until price takes the level.
The Closing Bell
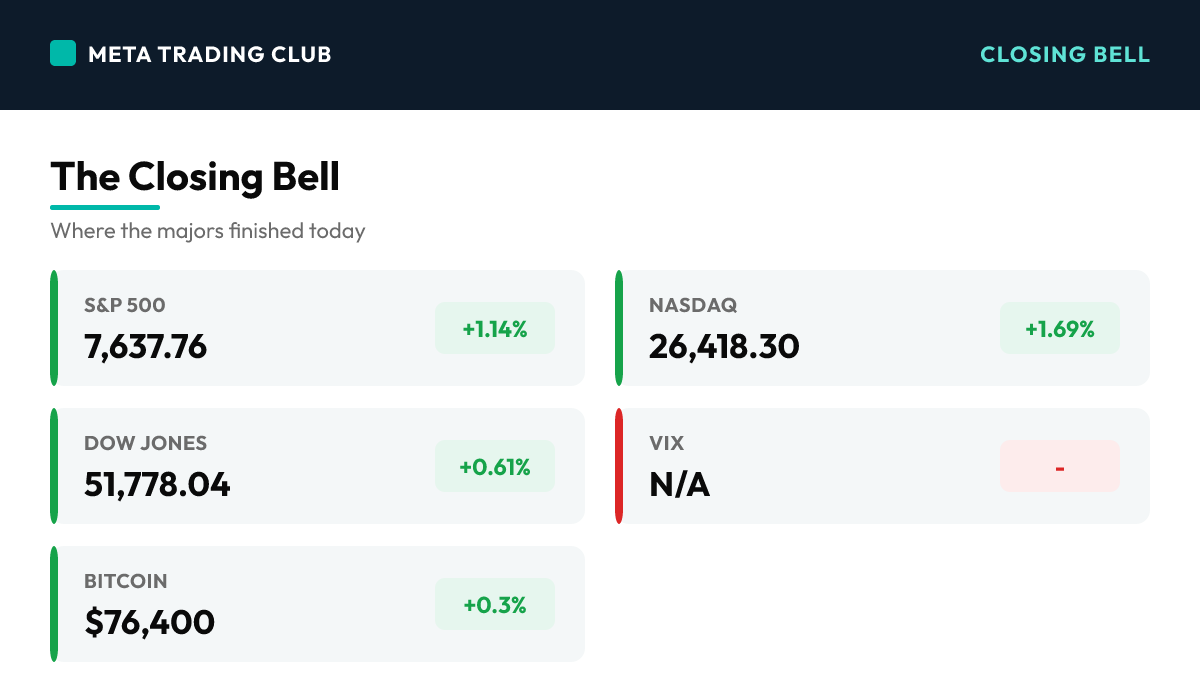
| Instrument | Close | Change | Note |
|---|---|---|---|
| S&P 500 | 7,637.76 | +1.14% | Rebounded 85.95 points as yields and oil eased, reclaiming the 7,600 shelf it lost during Wednesday’s hawkish-Fed flush and closing at 7,637.76. The number that matters is what it stopped under: 7,700, the level the September 11 bounce failed to reclaim on the way down. Price is now wedged between 7,600 reclaimed support and 7,700 overhead resistance, and the first clean move relative to 7,700 decides whether this is a real bottom or a bounce into supply. Hold 7,600 and reclaim 7,700 and the post-Fed reversal was a shakeout; fail 7,700 and the tape is back testing 7,500. |
| Nasdaq | 26,418.30 | +1.69% | The day’s leader, up 439.88 points as the rate-sensitive growth tape got the most relief from easing yields. Technology led all sectors, up more than 2%, carried by a loud mix of single names: Generac on an Amazon deal, Hewlett Packard Enterprise and Intel on the AI-hardware trade, and the broader mega-cap growth complex. When the group that fell hardest into a hike leads the bounce out of it, that is the market repricing the rate scare, not resolving it. The leadership was real but concentrated in the AI and data-center theme. |
| Dow Jones | 51,778.04 | +0.61% | The laggard of the three majors, up 316 points but held back by the very group that anchored Wednesday’s selloff. Financials finished red even on a strong tape, a sign the banks are still pricing a Fed that just forecast another hike and a 10-year that only eased rather than broke. A green Dow with red financials is a rally the rate-sensitive core has not fully signed off on, and it is one of the two reasons to treat today’s bounce as unconfirmed. |
| Russell 2000 | — | +1.1% | Rejoined the tape after lagging all week, up about 1.1% as the modest pullback in yields gave the most rate-sensitive index room to breathe. Small caps had been the cleanest tell on the bond market’s grip, so a Russell that finally participates is a real breadth improvement. But it took an eight-day yield streak snapping to get there, and with the 10-year still near 5% the group’s relief is only as durable as the pause in rates. Exact closing level approximate into the settle. |
| VIX | — | – | Fear eased as stocks rebounded and the reversal from Wednesday found footing, though an exact settle was not confirmed in the closing window. The tell today was not the level of the VIX but the shape of the tape: a broad, seven-sector-green advance with small caps participating is the opposite of the narrow, defensive character of the selloff. Level unconfirmed into the settle; treat the breadth, not a headline VIX print, as the read. |
| 10-Year Yield | 4.96% | -5 bp | The single most important number on the page eased from its 2007 high, snapping an eight-day rising streak, and this is the whole reason stocks could rally. But note the word: eased, not broke. The 10-year is still pinned near 5%, and the Fed that just forecast another hike has not changed its message. A yield that slips a few basis points off a two-decade high is relief, not a resolution, and until it decisively breaks down the higher-for-longer risk that started this whole slide is only paused. Level approximate into the settle. |
| 2-Year Yield | 4.68% | -4 bp | Eased alongside the 10-year as the market took a breath after Wednesday’s hawkish repricing. The 2-year is the purest read on the expected policy path, and a small step down says traders trimmed the odds of the Fed moving even faster, not that they abandoned the hiking view. This is the bond market exhaling, not reversing. With the dot plot still pointing to one more hike in 2026, the 2-year has a floor under it. Level approximate into the settle. |
| WTI Crude | $101.18 | -1.2% | Extended its slide, closing back near $101 as reports of additional Saudi crude routed through Oman and a faster restart of the East-West pipeline eased fears of a larger Middle East supply disruption. Falling oil was one of the two pillars under today’s rally, because the inflation driving this entire stretch has been an energy and Iran-war story. Crude coming off the boil takes pressure off the Fed’s problem, but it remains above $100 and headline-driven with the conflict still live. Level approximate into the settle. |
| Gold | $4,404 | +0.4% | Firmed as the softer-yield backdrop and a still-live inflation and geopolitical picture kept the safe-haven bid intact after a choppy post-Fed session. Gold has been the quiet hedge on a market caught between hot inflation and war risk, and it held its ground even as risk appetite returned to equities. When both stocks and gold can rise on the same day, it is a market hedging the rebound rather than fully trusting it. Level approximate into the settle. |
| Bitcoin | $76,400 | +0.3% | Steadied above $76,000, tracking the improved risk tone as equities rebounded and the SEC opened a regulatory pathway for tokenized U.S. stocks. Bitcoin traded like the high-beta risk asset it is, firming with the tape but without conviction, still working off the drag from the Senate’s failure to advance the CLARITY Act earlier in the week. A stabilization, not a breakout. Level approximate into the settle. |
Today’s Charts
Daily candlestick charts with 20/50/200-day moving averages — the index majors, the day’s biggest mover on each side, and the leading sector ETF.

Charts: Finviz (daily). Levels and overlays update through the next session.
Sector Scoreboard
What Drove The Day
This was a mirror image of Wednesday, and it turned on the same two variables that caused the damage. The hawkish Fed hike sent yields back above 5% and stocks lower on September 16; on September 17 both yields and oil reversed, and the beaten-up tape rebounded hard. The 10-year eased off its 2007 high, snapping an eight-day rising streak, and WTI crude slipped back near $101 as Saudi supply routed through Oman calmed war-premium fears. That was the green light. The Nasdaq led, up 1.69% to 26,418.30, as the rate-sensitive growth names that fell hardest bounced the most; the S&P 500 rose 1.14% to 7,637.76; and the Dow added 316 points, or 0.61%, to 51,778.04. Breadth flipped decisively, with seven of eleven sectors green, technology out front up more than 2%, and the Russell 2000 finally participating, up about 1.1% after lagging all week. The leadership was loud and specific: Generac exploded roughly 21% after announcing a long-term supply deal with Amazon to provide backup generators for its data centers; Moderna jumped about 9% on positive Phase 3 cancer-vaccine data with Merck; and the AI-hardware trade, Hewlett Packard Enterprise and Intel, ran about 7% each. But two things kept the rally honest. Financials finished red even on a strong tape, the same rate-sensitive group that anchored Wednesday’s selloff, and the 10-year, while lower, is still pinned near 5% with a Fed that has not backed off its message. And price stalled right at the line that framed the entire move: the S&P closed at 7,637.76, having reclaimed 7,600 but stopping just under 7,700, the exact level last week’s failed bounce could not reclaim. The rebound is real. The reclaim is not done.
MAJOR HEADLINES AND CATALYSTS
Top Market-Moving Stories
- YIELDS AND OIL BOTH EASED, AND STOCKS RALLIED (Day) – The two variables that caused Wednesday’s selloff reversed together. The 10-year Treasury yield eased off its 2007 high, snapping an eight-day rising streak, and WTI crude slipped back near $101 as Saudi Arabia routed extra supply through Oman. That combination gave a beaten-up tape the green light: the Nasdaq jumped 1.69%, the S&P 500 rose 1.14% to 7,637.76, and breadth flipped to seven of eleven sectors green with small caps finally participating.
- GENERAC EXPLODED ON AN AMAZON DATA-CENTER DEAL (Day) – Generac skyrocketed about 21% after announcing a long-term supply agreement with Amazon to provide industrial backup generators for its data centers, with initial deliveries totaling $2.4 billion in 2027-2028 and potential payments up to $8 billion. It was the day’s standout single-name move and a clean read on the scale of AI and data-center capex spending still flowing through the market.
- THE RATE-SENSITIVE CORE DID NOT FULLY CONFIRM (Day) – Two witnesses stayed home. Financials finished red even on a broadly green day, the same group that anchored Wednesday’s selloff, and the 10-year, while lower, is still pinned near 5%. A rally led by growth and cyclicals but not endorsed by the banks, on a yield that eased rather than broke, is a relief bounce that has not yet resolved the higher-for-longer question the Fed reopened.
- THE REBOUND STALLED RIGHT UNDER 7,700 (Day) – The S&P reclaimed the 7,600 shelf it lost Wednesday but closed at 7,637.76, stopping just below 7,700, the exact level the September 11 bounce failed to reclaim on the way down. Price is now pinned between reclaimed support and overhead resistance, and 7,700 is the single line that decides whether this is a real bottom or a bounce into supply heading into Friday.
AFTER-HOURS EARNINGS SPOTLIGHT
FedEx Beats, Lennar Misses After the Bell
- FEDEX JUMPED ON A CLEAN BEAT (AH) – FedEx posted better-than-expected results for the first quarter of fiscal 2026 after the close and guided full-year revenue up 4% to 6%, sending shares about 5.5% higher to $238.91 in the after-hours session. As the classic freight-and-economy bellwether, a FedEx beat with constructive guidance is a real-time read that the shipping economy is holding up, and it gives the tape a growth-positive headline to carry into Friday.
- LENNAR MISSED AS HOUSING STAYS UNDER PRESSURE (AH) – Homebuilder Lennar posted weaker-than-expected third-quarter results after the bell, with adjusted earnings of $2.00 a share missing the $2.10 estimate and revenue of $8.81 billion falling short of the $8.99 billion consensus. Shares fell about 3.2% to $128.62 after hours. With the 10-year still near 5%, the miss is a reminder that a mortgage-rate-sensitive corner of the economy is feeling the higher-for-longer pressure the Fed just reinforced.
- THE DAY’S DRAG WAS COMPANY-SPECIFIC (Day) – Fluence Energy cratered about 17% after cutting its full-year outlook on contract-manufacturing delays, CoreWeave fell about 5% on a $3 billion convertible debt offering, and Copart slipped about 3% on an HSBC downgrade. The weakness was idiosyncratic rather than macro, single-name stories on a day the broad tape rallied, which is the opposite of Wednesday’s rate-driven, everything-down selloff.
WHAT IT SETS UP FOR TOMORROW
Does the Bounce Reclaim 7,700 on Quad-Witching Friday?
- 7,700 IS THE LINE THAT DECIDES IT (Tomorrow) – Friday is the follow-through test. The S&P closed at 7,637.76, having reclaimed 7,600 but stalling under 7,700, the level that framed the entire selloff. Reclaim 7,700 and hold it and the post-Fed flush was a shakeout and the trend resumes; fail there and lose 7,600 and the tape is right back on 7,500. The first clean move relative to 7,700 sets the tone, and it lands on a quad-witching expiration that can amplify the move.
- QUAD-WITCHING AND THE BOJ ADD NOISE (Tomorrow) – Friday, September 18 is a quarterly quad-witching options expiration, which tends to bring elevated volume and mechanical, flow-driven swings that can mask the real signal. Layer in the Bank of Japan’s policy decision from its September 17-18 meeting and lingering U.S. data, and the tape has plenty of cross-currents. On an expiration day, the discipline is to trust the level over the intraday noise.
Winners & Losers
Winners
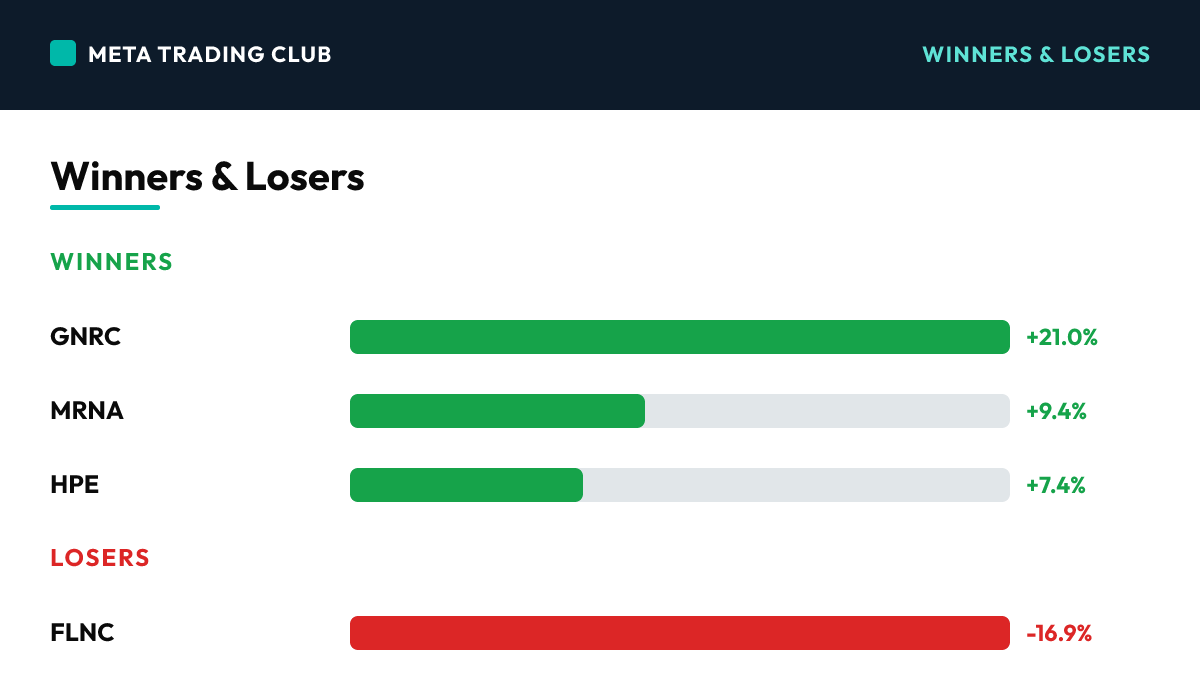
| GNRC | +21.0% | Generac skyrocketed after announcing a long-term supply agreement with Amazon to provide industrial backup generators for its data centers, with initial deliveries of $2.4 billion in 2027-2028 and potential payments up to $8 billion. The day’s standout move and a clean read on the scale of AI and data-center capex still flowing through the market. | |
| MRNA | +9.4% | Moderna jumped as investors kept reacting to positive Phase 3 results with Merck for its personalized mRNA cancer vaccine, intismeran autogene. A clean, company-specific biotech catalyst that gave health care a leader independent of the rate story and stood out on a broadly green day. | |
| HPE | +7.4% | Hewlett Packard Enterprise rose on continued investor interest in AI hardware and data-center infrastructure spending. Part of the narrow but loud AI-hardware leadership, alongside Intel, that helped power the Nasdaq’s 1.69% gain as easing yields lifted the rate-sensitive growth complex. |
Losers
| FLNC | -16.9% | Fluence Energy cratered after the battery energy-storage company cut its full-year outlook, citing delays at its contract manufacturing facility. The day’s ugliest move and a company-specific story rather than a macro one, a guidance cut that stood out precisely because the broad tape rallied around it. | |
| CRWV | -4.7% | CoreWeave dropped after the cloud-computing provider announced plans to raise $3 billion through a convertible debt offering. Dilution and balance-sheet concerns weighed on the AI-infrastructure name even as the broader AI-hardware theme, HPE and Intel, led the market higher. | |
| CPRT | -3.0% | Copart slipped after HSBC downgraded the online vehicle-auction company to Hold from Buy and set a $36 price target, citing challenges in its insurance business and slowing growth. A single analyst-driven decline on a day the broad market advanced. |
What It Sets Up For Tomorrow
Levels Into Tomorrow
- S&P 500 7,700 – THE LINE THAT DECIDES IT. Price closed at 7,637.76, having reclaimed 7,600 but stopping just below 7,700, the exact level the September 11 bounce failed to reclaim on the way down. This is the single most important number on the page. Reclaim 7,700 and hold it on Friday and the hawkish-Fed reversal gets confirmed as a shakeout, with the trend turning back up; fail there and the rebound is a bounce into supply. The first clean move relative to this line decides whether the bulls or the bears own the week’s close.
- S&P 500 7,600 – THE RECLAIMED SHELF. The level lost during Wednesday’s flush and reclaimed today, now the first support beneath price. As long as the S&P holds above 7,600, the bulls keep control of the bounce and the argument that the post-Fed selloff front-loaded the bad news stays intact. Lose 7,600 and the reclaim fails, opening the door back to 7,500, the line that held on the first post-Fed session. This is the level that separates a healthy pause from a failed rebound.
- S&P 500 7,500 – THE FLOOR THAT HELD. The round number that held on the first post-Fed session and launched today’s bounce. If Friday’s quad-witching noise and a still-elevated 10-year drag price back through 7,600, 7,500 is the line the whole recovery rests on. Hold it a second time and the base is real; lose it and the failed bounce from last week plus a failed reclaim this week sets up a larger move lower toward 7,400. This is the bear’s re-entry level if the rebound unravels.
Bull case: The rate scare is unwinding and the bounce is the start of the recovery. The two things that caused the selloff, rising yields and rising oil, both reversed today: the 10-year snapped an eight-day climb and crude fell back under $101. Breadth confirmed the move, with seven of eleven sectors green, the Russell 2000 finally participating, and leadership from the highest-quality growth and AI-hardware names. FedEx’s after-hours beat says the real economy is holding up. If Friday reclaims 7,700 and holds it, even through quad-witching noise, the argument is that the market flushed all the hawkish-Fed fear in a single Wednesday session and today began pricing the relief. Above 7,700 the post-Fed reversal becomes a shakeout and the path reopens toward the highs.
Bear case: This is a relief bounce into resistance, and the rate story is only paused. The 10-year eased but is still pinned near 5%, the Fed still forecasts another hike, and financials, the rate-sensitive core, finished red even on a strong tape, refusing to confirm the rally. Price stalled exactly at 7,700, the level last week’s failed bounce could not reclaim, which is textbook lower-high behavior. Lennar’s after-hours miss shows the higher-for-longer pressure is already biting the rate-sensitive parts of the economy. If Friday fails at 7,700 and loses 7,600, the bounce is confirmed as a bounce, and with quad-witching flows able to accelerate the move, the tape heads back to retest 7,500, where a second failure opens 7,400.
Risks Into Tomorrow
- A bounce is not a reclaim until price takes the level — Today’s rally was real, broad, and led by quality, and it still stopped dead at 7,700, the exact line last week’s failed bounce could not reclaim. This is the trap that catches traders every relief rally: they confuse a strong up day with a resolved trend. The tape rebounded because yields and oil eased, but the level tells you whether that rebound means anything. Price reclaimed 7,600 and stalled under 7,700, which is textbook behavior for a bounce into overhead supply. The discipline is to let the level confirm the story: above 7,700 the shakeout thesis is valid and you can trust the recovery; below it, you are trading a bounce that has not proven itself, and the burden of proof stays on the bulls.
- Watch what refuses to confirm, not just what rallies — It is easy to see the Nasdaq up 1.69% and declare the scare over. The information was in what did not participate. Financials, the rate-sensitive core that led Wednesday’s selloff, finished red even on a broadly green day, and the 10-year eased but stayed pinned near 5%. Those are the two witnesses that stayed home, and they are telling you the higher-for-longer question is paused, not answered. The skill is to hunt for the non-confirmation on a strong day the same way you hunt for the leader on a weak one. When the group most tied to the actual problem sits out the celebration, respect the message: the market is rallying while quietly hedging, and a rally the rate core will not endorse is a rally on probation.
- Respect the noise you can predict, like quad-witching — Friday is a quarterly quad-witching expiration, and that is a known variable, not a surprise. Traders repeatedly get run over on expiration days because they read mechanical, flow-driven swings as real signal and chase them. The move through a level at 10:00 AM on quad-witching can fully reverse by 2:00 PM as expiring positions unwind, which is exactly why anchoring to the level instead of the tick matters more on these days, not less. The plan into Friday is simple: define 7,700 as the reclaim line and 7,600 as the shelf, and require a clean, sustained move, not an expiration-driven spike, before acting. When you know the noise is coming, you do not have to be its victim. No alignment between a flow-driven wick and a confirmed break means no trade.
Frequently Asked Questions
How did the S&P 500 close today?
On Thursday, September 17, 2026, the S&P 500 closed at 7,637.76 (+1.14%), with the VIX at N/A. The stock market today did exactly what the bears warned it might not: it bought the dip the bond market handed it.
What drove the market today?
YIELDS AND OIL BOTH EASED, AND STOCKS RALLIED (Day) – The two variables that caused Wednesday’s selloff reversed together. The 10-year Treasury yield eased off its 2007 high, snapping an eight-day rising streak, and WTI crude slipped back near $101 as Saudi Arabia routed extra supply through Oman. That combination gave a beaten-up tape the green light: the Nasdaq jumped 1.69%, the S&P 500 rose 1.14% to 7,637.76, and breadth flipped to seven of eleven sectors green with small caps finally participating.
What levels matter for tomorrow?
S&P 500 7,700 – THE LINE THAT DECIDES IT. Price closed at 7,637.76, having reclaimed 7,600 but stopping just below 7,700, the exact level the September 11 bounce failed to reclaim on the way down. This is the single most important number on the page. Reclaim 7,700 and hold it on Friday and the hawkish-Fed reversal gets confirmed as a shakeout, with the trend turning back up; fail there and the rebound is a bounce into supply. The first clean move relative to this line decides whether the bulls or the bears own the week’s close. S&P 500 7,600 – THE RECLAIMED SHELF. The level lost during Wednesday’s flush and reclaimed today, now the first support beneath price. As long as the S&P holds above 7,600, the bulls keep control of the bounce and the argument that the post-Fed selloff front-loaded the bad news stays intact. Lose 7,600 and the reclaim fails, opening the door back to 7,500, the line that held on the first post-Fed session. This is the level that separates a healthy pause from a failed rebound. S&P 500 7,500 – THE FLOOR THAT HELD. The round number that held on the first post-Fed session and launched today’s bounce. If Friday’s quad-witching noise and a still-elevated 10-year drag price back through 7,600, 7,500 is the line the whole recovery rests on. Hold it a second time and the base is real; lose it and the failed bounce from last week plus a failed reclaim this week sets up a larger move lower toward 7,400. This is the bear’s re-entry level if the rebound unravels.
How does Meta Trading Club prepare for the next session?
We wrap every session and carry the read forward through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
New to this? Start with the free training.
Learn how we read the market before you risk a dollar — our free education library and ebook break down the fundamentals step by step.
Free education → Get the free ebookThe session’s over. The prep isn’t.
This is how MTC members close each day — wrap what happened, mark the levels, and carry one clean read into tomorrow. If you want to build that habit and qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process. It’s application-based — see if it’s a fit.
Explore the MTC Incubator → Apply nowSources: Yahoo Finance, CNBC, TheStreet, Benzinga, and Investing.com closing coverage for Thursday, September 17, 2026, including the market rebound a day after the FOMC rate hike, Treasury, commodity and crypto market data, sector performance and single-stock moves, and FedEx and Lennar after-hours earnings. Some cross-asset levels (Russell 2000, VIX, 10-year and 2-year yields, gold and bitcoin) approximate into the settle; the VIX close was unconfirmed in the closing window.. For educational purposes only. Not financial advice.