Thursday, September 17, 2026 · 8:45 AM ET · MTC Market Intelligence
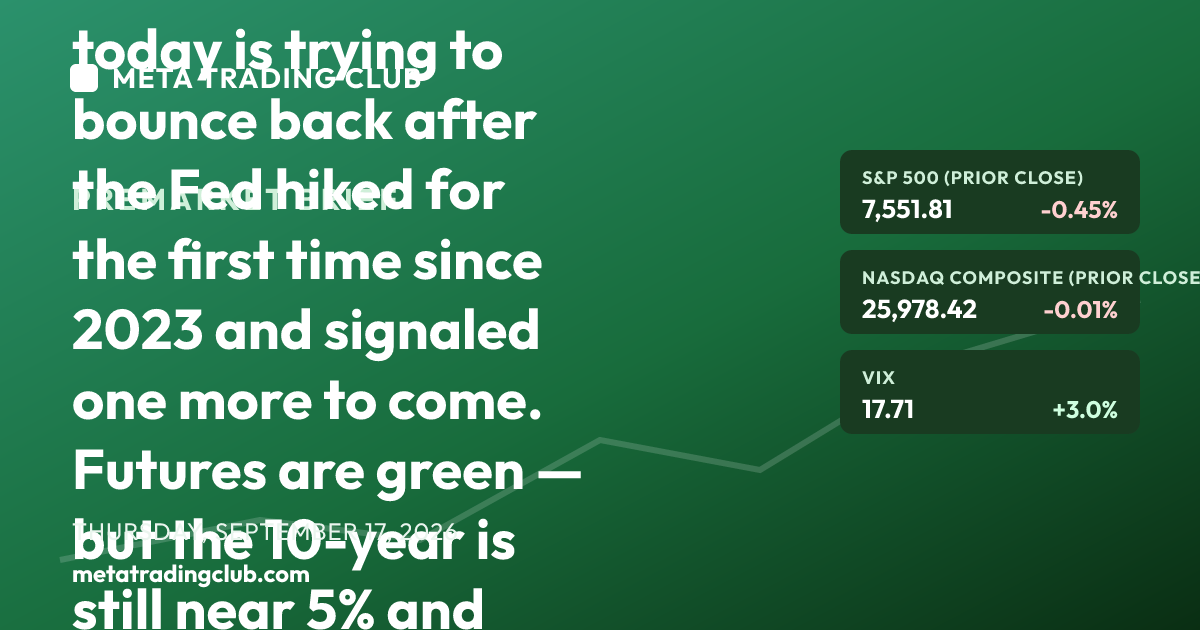
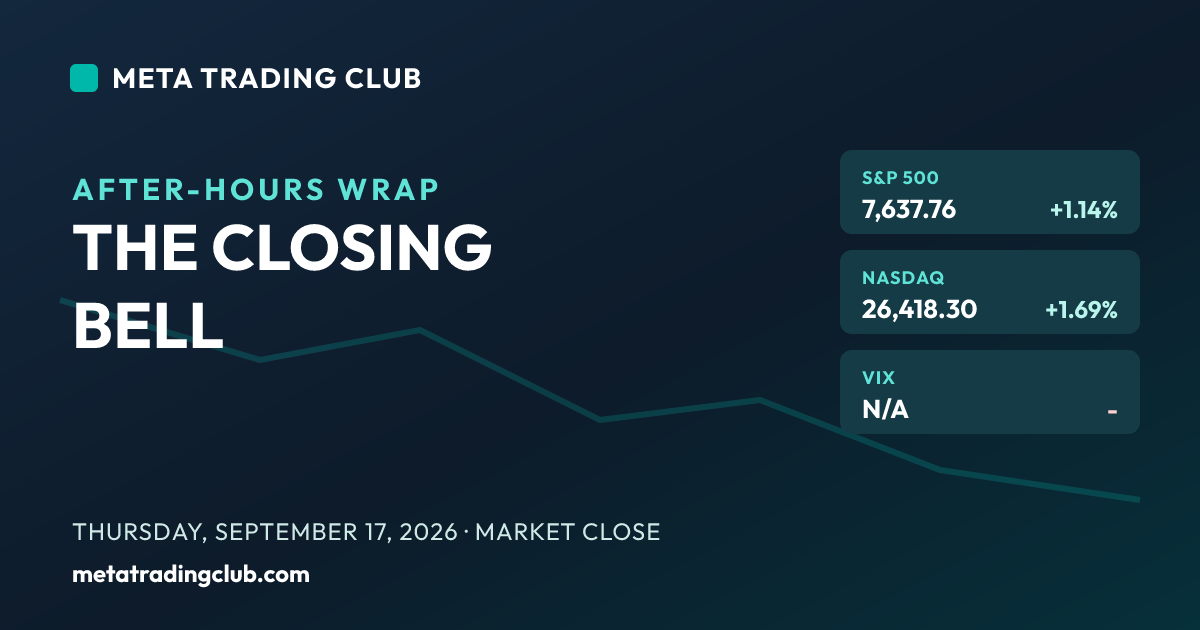
The stock market today is trying to bounce off the Fed. Wednesday the FOMC did what almost no one thought it would a few months ago — it hiked. New Fed Chair Kevin Warsh’s committee voted 12-0 to lift rates 25bp to 3.75%-4.00%, the first increase since 2023, and the dot plot penciled in one more before year-end. Stocks didn’t like the message underneath the move: Warsh called inflation sticky and said ‘nothing suggests anything is slowing down in the economy,’ and the tape sold off into the close. The Dow dropped 631 points, or 1.21%, to 51,461.90 with Goldman Sachs leading financials lower; the S&P slipped 0.45% to 7,551.81; the Nasdaq held flat at 25,978.42 as semis absorbed the hit better than the banks. This morning the tape is trying to relieve: S&P futures +0.3%, Nasdaq-100 +0.5%, Dow +0.2%, with Treasuries paring losses as the market reads Warsh’s inflation resolve as at least a known quantity. But look at the backdrop before you trust the bounce — the 10-year is still sitting at 4.998%, right under 5% and the highest since 2023, WTI is holding $102, and the Fed just told you another hike is coming. That’s the exact setup where the morning after a hawkish Fed produces a relief pop that fades. Here’s the trap most traders will walk into today: they’ll read the green futures as the all-clear and chase the first candle. The move isn’t the bounce — it’s whether the bounce holds a level. So the job is simple. Mark 7,585 above and 7,500 below, let SPX prove which way it wants to go, and don’t confuse a relief pop with a reversal. No alignment, no trade.
Market Snapshot
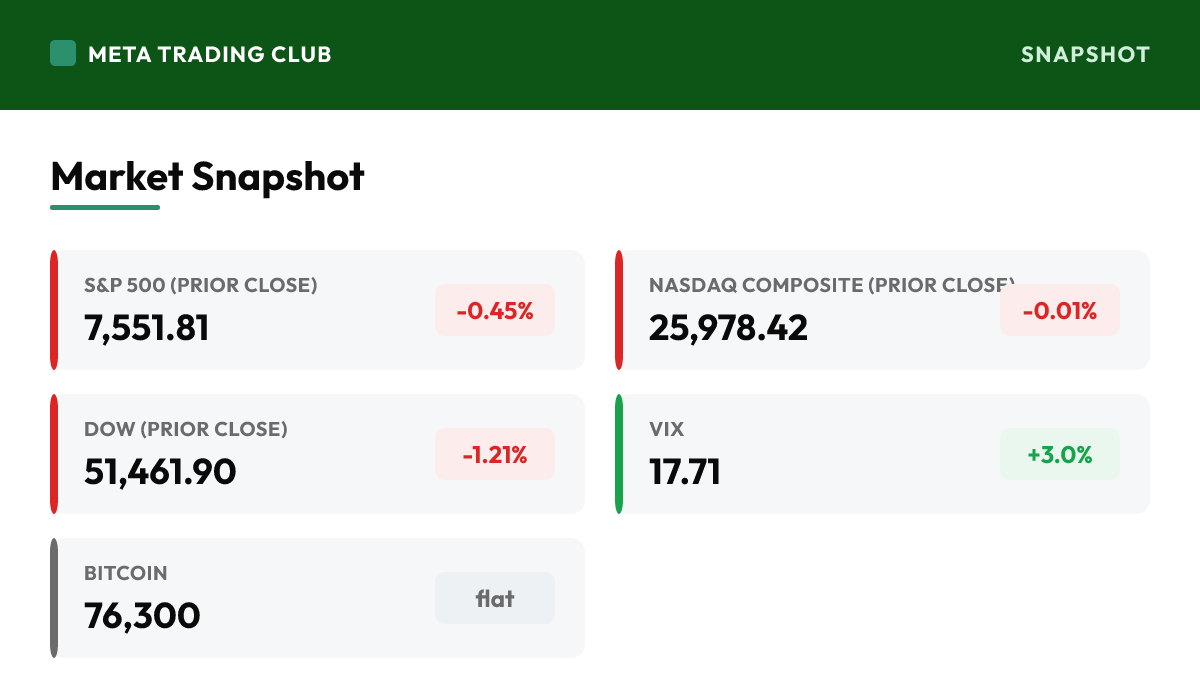
| Instrument | Level | Change | Note |
|---|---|---|---|
| S&P 500 (prior close) | 7,551.81 | -0.45% | Fell 0.45% Wednesday to 7,551.81 as Warsh’s hawkish press conference pulled the tape off its intraday highs. That close is the pivot every reaction swings around today. The index gave back gains once the message landed — proof the market cares more about the path than the single hike it already expected. |
| Nasdaq Composite (prior close) | 25,978.42 | -0.01% | Essentially flat Wednesday at 25,978.42, the clear relative winner as semis and AI names absorbed the Fed better than rate-sensitive financials. If this bounce has legs, tech is where the leadership shows up first — but a 5% 10-year keeps a ceiling on long-duration growth no matter how green the open looks. |
| Dow (prior close) | 51,461.90 | -1.21% | Dropped 631.21 points, or 1.21%, Wednesday to 51,461.90, the worst of the majors, with Goldman Sachs leading financials lower. Banks and cyclicals took the brunt of the hawkish read. Watch whether the financials that got hit hardest stabilize this morning — that’s the tell on whether the bounce is real or cosmetic. |
| S&P 500 Futures | — | +0.3% | Up 0.3% as the tape tries to relieve the post-Fed selling. Don’t read the all-clear into it — green futures the morning after a hawkish hike are exactly the setup that produces a relief pop that fades. The signal isn’t the pop, it’s whether SPX can reclaim and hold 7,585 once the cash market opens. |
| Dow Futures | — | +0.2% | Up 0.2%, the laggard of the three as financials try to steady after leading the drop. The most rate-sensitive index has the most to prove today — a bounce that leaves the banks behind is a bounce on borrowed time. Watch Goldman and the money-center names for the real read. |
| Nasdaq-100 Futures | — | +0.5% | Up 0.5%, leading the premarket as semis and AI stay the resilient corner. This is where any genuine bounce announces itself first. But treat tech strength as fragile until the 10-year actually rolls off 5% — growth is the highest-beta name to the rate path, up and down. |
| VIX | 17.71 | +3.0% | Up about 3% near 17.71 even with futures green — the fear gauge is not buying the bounce yet. That’s a market bracing, not relaxing. Elevated vol into a relief pop is a caution flag: it says the two-way risk is still live and the reaction to the Fed isn’t finished playing out. |
| WTI Crude | 102.10 | -0.3% | Down 0.3% but still holding $102, with the inflation-and-yield loop firmly intact. Crude this high is the whole reason the Fed is tightening — until oil cools meaningfully, the rate ceiling over stocks stays in place. A modest pullback here doesn’t change the regime; it just eases the pressure at the margin. |
| 10-Yr Yield | 4.998% | higher | Sitting at 4.998%, just under 5% and the highest since 2023 — the single most important number on the screen. A near-5% 10-year is the ceiling on every rally. The bounce only earns trust if this yield starts coming in; if it presses back over 5%, the relief pop has a short shelf life. |
| Bitcoin | 76,300 | flat | Holding near $76,300, barely moved through the Fed as crypto-linked equities (Coinbase, Circle, Robinhood) sold off on the hike. Bitcoin’s steadiness while its equity proxies got hit is a small tell that the selling was rate-driven, not risk-collapse. Treat it as consolidation, not a trend, with yields at cycle highs. |
Charts to Watch
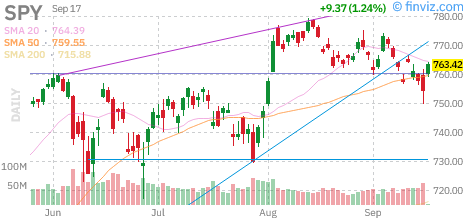
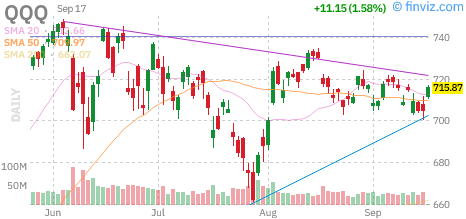
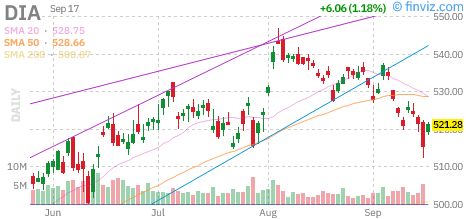
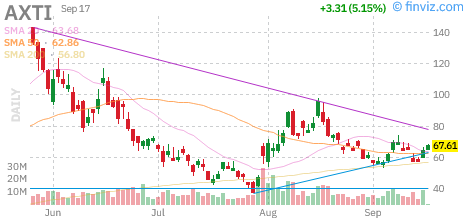
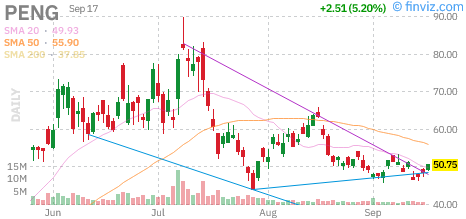
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
Overnight & Global Markets
Wednesday delivered the hawkish first hike and stocks faded the message: the Dow fell 631.21 points, or 1.21%, to 51,461.90 with Goldman Sachs leading financials lower, the S&P 500 slipped 0.45% to 7,551.81 after giving back intraday gains during Warsh’s press conference, and the Nasdaq Composite finished essentially flat at 25,978.42 as semis absorbed the blow better than banks. The FOMC voted 12-0 to raise rates 25bp to 3.75%-4.00%, the first increase since 2023, and the dot plot signaled one more hike this year. This morning the tape is trying to bounce — S&P futures +0.3%, Nasdaq-100 +0.5%, Dow +0.2% — with Treasuries paring losses as the market digests Warsh’s inflation resolve. But the backdrop is unchanged and hostile: the 10-year is at 4.998%, just under 5% and a multi-year high, WTI is holding $102, and the Fed just told the market another hike is coming. The setup is a textbook morning-after relief pop into a tightening regime. This morning is about letting the level confirm, not chasing the green.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The Fed hiked and the market is still digesting the message. In a unanimous 12-0 vote, Chair Kevin Warsh’s FOMC raised the target range 25bp to 3.75%-4.00%, the first increase since July 2023, and the Summary of Economic Projections showed officials expect one more hike before year-end. The decision itself was largely priced; what moved the tape was Warsh’s tone. Calling inflation sticky and saying nothing suggests the economy is slowing, he framed this as removing ‘a dose of accommodation,’ not a one-and-done. That’s why stocks faded into the close and why this morning’s bounce has to prove itself.
- The reason the Fed is tightening is still sitting on the screen: the 10-year Treasury yield is at 4.998%, just under 5% and its highest since 2023, and WTI crude is holding $102. Elevated energy keeps inflation sticky and the bond market is leaning into a hawkish Fed, not fading it. A near-5% 10-year is the ceiling on every rally — until that yield actually rolls over, equity upside stays capped no matter how green the premarket looks.
- Stocks are trying to relieve the post-Fed selloff, with futures pointing to a modest rebound as Treasuries pare losses. But the VIX is up ~3% near 17.71 even with futures green — the fear gauge isn’t buying it yet. That divergence is the story of the morning: a market that wants to bounce sitting on top of a backdrop that hasn’t changed. The mistake would be to read the green as the all-clear. The tape is telling you the reaction to the Fed isn’t finished.
Stock-Specific
- AI and semis remain the tape’s cleanest relative strength. AXT Inc. (AXTI) is higher again premarket on the broader AI-semiconductor recovery bid, and Penguin Solutions (PENG) is among the top gainers after showcasing a new 11TB MemoryAI KV Cache Server and an AI-infrastructure partnership at the AI Infra Summit 2026. The AI-capex theme is the one narrative still drawing money the morning after a hawkish Fed — but it’s narrow leadership, a bid rather than a broad-market foundation.
- Crypto-linked equities are the group to watch after Wednesday’s damage. Coinbase (COIN), Circle (CRCL) and Robinhood (HOOD) led a broad selloff in publicly listed crypto stocks as the hike hit high-multiple, rate-sensitive names — even as Bitcoin itself held near $76,300 and barely moved. That split is the lesson: the selling was about rates, not a collapse in crypto. Watch whether these names stabilize with the tape or keep bleeding as the 10-year sits near 5%.
- On the downside, Sea Limited (SE) remains under pressure premarket on a stack of its own issues — high-profile insider share sales by top executives disclosed in recent SEC filings, on top of the general drag a 5% 10-year puts on expensive growth. It’s a clean, single-name story, not a market tell, but it’s a textbook example of the vulnerability the whole high-multiple complex carries into a hawkish rate regime.
Global and Macro
- The rates and energy markets are still driving the regime. The 10-year just under 5% and WTI over $100 are a self-reinforcing loop: higher oil lifts inflation expectations, which lifts yields, which pressures stocks and keeps the Fed hawkish. Wednesday’s hike was the policy response to that loop, and the dot plot says there’s one more coming. Until oil cools or yields roll over, the backdrop stays hostile to risk regardless of any single morning’s bounce.
- The variable that matters now is whether the market believes Warsh’s ‘one more hike’ or fades it. The bond market is voting with a near-5% 10-year — it’s taking the Fed at its word. That’s the key thing to track today: if yields press back over 5%, this relief pop is living on borrowed time; if they start to come in, the bounce has a foundation. Let the 2-year and 10-year, not the equity headline, guide your read of the reaction.
TECHNICAL ANALYSIS
S&P 500 Key Levels
- The S&P closed Wednesday at 7,551.81, and that level is the axis this morning rotates around. On the upside, 7,585 is the first hurdle — reclaim and hold it and the bounce has legs toward 7,620 and then 7,660, telling you the market can look past the hawkish hike. But this is a relief pop until price proves otherwise: don’t chase the premarket green toward it, make SPX take and hold the level after the open before you trust it.
- First support is 7,530, then the line that matters: 7,500. Lose 7,500 and the post-Fed selling resumes toward 7,460 and a deeper risk-off leg as the 10-year presses back toward 5%. Above 7,530 the tape stays balanced and the bounce is intact; below 7,500 the relief pop has failed and the hawkish read is back in control. Mark 7,585 above and 7,500 below — between them is noise, outside them is the trade.
Sector and Sentiment
- The leadership tell is semis versus financials. Tech held flat through the Fed while the Dow lost 1.21% on bank weakness, and Nasdaq-100 futures lead this morning. For the bounce to be real, you want to see the financials that got hit hardest — Goldman and the money-center names — stabilize and participate. A rally carried only by semis while banks lag is a narrow, fragile bounce, not a broad reversal.
- The VIX up ~3% near 17.71 into green futures is the sentiment caution flag. The fear gauge rising while the tape tries to bounce says the market is bracing, not relaxing — the two-way risk from the Fed is still live. Practically, that means respect the possibility of a fast reversal, don’t confuse a relief pop for an all-clear, and let a level hold before you lean on the long side.
TODAY’S ECONOMIC CALENDAR
Key Releases (ET)
- With the Fed behind us, the data turns to the labor and housing read. Weekly initial jobless claims and housing starts are on the calendar for this morning. Claims are the timeliest gauge of whether the labor market is softening — and after Warsh explicitly said nothing looks like it’s slowing down, any surprise here gets extra attention as a check on the Fed’s ‘more hikes’ framing. Housing starts matter given a near-5% 10-year is squarely aimed at rate-sensitive demand.
- The bigger variable than any single print today is the bond market’s verdict on the Fed. Watch the 2-year and 10-year yields in real time — they’ll tell you whether the market is taking Warsh at his word or starting to fade the ‘one more hike’ path. Let the rates reaction, not the first equity headline, guide your read of the day. A relief pop in stocks with yields still pinned near 5% is a fragile bounce, not a turn.
Earnings Today
- The week is running a mini earnings season, with consumer and delivery names in focus — General Mills, Darden and Nike are all on the docket this week, and FedEx is a key report investors are watching as a global-demand bellwether. Darden (DRI) is the notable consumer read around today’s session: on a day the Fed is tightening into sticky inflation, a restaurant operator’s pricing and traffic commentary is a timely gauge of how the consumer is holding up under higher-for-longer rates.
- Treat earnings as texture, not the main event today. The tape is still trading the Fed’s message and the path of yields, not single-name prints. Where an earnings reaction matters is as a read on the macro question underneath everything — is the consumer and end demand slowing enough to justify a pause, or is Warsh right that nothing is slowing down? Listen to the guidance for that answer, not just the headline number.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,585 — the upside proof. This is the first hurdle above Wednesday’s 7,551.81 close. Reclaim it AND hold it after the open and the bounce has legs — buyers looking past the hawkish hike, with 7,620 and then 7,660 back in play. But this only counts once the cash market takes the level; the premarket green doesn’t. Don’t chase the pop toward it — make price prove it can hold above before you trust the long side.
- SPX 7,551 / 7,530 — the pivot and the balance line. 7,551.81 is Wednesday’s close and the axis the morning rotates around; 7,530 is the first support under it. Hold this zone and the bounce stays intact and two-way, ready to resolve higher. This is the ‘let it prove itself’ band — the tape lives here early, and the real signal is which side it leaves on. Patience beats prediction inside this range.
- SPX 7,500 — the invalidation line. Lose it and the relief pop has failed: the post-Fed selling resumes toward 7,460 and a deeper risk-off leg as the 10-year presses back toward 5%. Below 7,500 the hawkish read is back in control and the job flips to capital preservation. This is the number that separates a real bounce from a dead-cat pop — mark it, and respect it if it goes.
Bull case: The market decides the hawkish hike was the clearing event and yields start to come in off the 5% highs. SPX reclaims 7,585, the financials that led the drop stabilize and participate, and semis keep their leadership — the bounce broadens beyond tech and pushes toward 7,620-7,660. In this scenario, Wednesday’s selloff was an overreaction to Warsh’s tone rather than the fundamentals, the ‘one more hike’ is treated as manageable, and the relief pop turns into a genuine recovery once the rates pressure eases.
Bear case: The relief pop fades. The 10-year presses back over 5%, the VIX keeps climbing, and the market decides Warsh means it about another hike and sticky inflation. Financials keep bleeding, crypto-linked and high-beta growth roll over again, and SPX loses 7,530 and then 7,500 into a deeper risk-off leg toward 7,460. In this scenario the green open was a classic morning-after head-fake, the tightening regime is unchanged, and the path of least resistance stays lower until yields or oil finally cool.
Premarket Movers
Gainers
| AXTI | AXT Inc. | higher on the AI-semiconductor recovery bid | Firmer again premarket as the AI-semiconductor complex holds its bid the morning after the Fed. It’s a beta play on the one theme with real leadership right now — AI compute and memory demand — rather than a company-specific catalyst. Treat it as a read on risk appetite inside the semis trade: if the AI bid holds through the open, names like this hold with it, and it’s a tell the bounce has a leader. |
| PENG | Penguin Solutions | up on new AI-infrastructure product and partnership | Among the top gainers after showcasing a new 11TB MemoryAI KV Cache Server and an AI-infrastructure partnership at the AI Infra Summit 2026. This is a clean, catalyst-driven move tied to the AI-capex story that keeps drawing money even into a hawkish rate backdrop. A single-name story, but a useful confirmation that the AI-infrastructure theme is still the market’s preferred place to hide. |
Laggards
| SE | Sea Limited | lower on insider share sales | Under pressure premarket after high-profile insider share sales by top executives — including senior officers — disclosed in recent SEC filings, on top of the drag a near-5% 10-year puts on high-multiple growth. It’s a textbook example of what this rate regime does to expensive growth names: the exact vulnerability the whole high-multiple complex carries into a Fed that just promised one more hike. A single-name story, not a market tell. |
Risks Into the Open
- Primary risk: chasing the relief pop. Green futures the morning after a hawkish hike are the classic setup for a bounce that fades — the VIX rising into it near 17.71 is the tell that the market isn’t relaxed. The mistake today is reading the green as the all-clear and buying the first candle. Wait for SPX to reclaim and hold 7,585 with the rates reaction confirming; a pop that can’t hold a level is a fade, not a reversal.
- The backdrop hasn’t changed and it’s hostile. The 10-year is at 4.998%, oil is holding $102, and the Fed just signaled one more hike. That’s the same inflation-and-yield loop that forced Wednesday’s move, still fully intact. Even a strong-looking bounce is happening inside a tightening regime — treat any rally that isn’t confirmed by yields actually coming in off 5% as relief inside a hostile tape, not a turn in the trend.
- Watch the leadership quality, not just the index. The bounce is being led by semis while financials — the group that led Wednesday’s drop — are the question mark. A rally carried by a narrow AI-infrastructure bid while banks and high-beta names lag is fragile. The confirmation you want is broad participation: if Goldman and the money-center names stabilize and join, the bounce is real; if they don’t, it’s cosmetic and vulnerable to a fast reversal.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Thursday, September 17, 2026, S&P 500 futures are at 7,551.81 (-0.45%), with the VIX near 17.71. The stock market today is trying to bounce off the Fed. Wednesday the FOMC did what almost no one thought it would a few months ago — it hiked. New Fed Chair Kevin Warsh’s committee voted 12-0 to lift rates 25bp to 3.75%-4.00%, the first increase since 2023, and the dot plot penciled in one more before year-end. Stocks didn’t like the message underneath the move: Warsh called inflation sticky and said ‘nothing suggests anything is slowing down in the economy,’ and the tape sold off into the close. The Dow dropped 631 points, or 1.21%, to 51,461.90 with Goldman Sachs leading financials lower; the S&P slipped 0.45% to 7,551.81; the Nasdaq held flat at 25,978.42 as semis absorbed the hit better than the banks. This morning the tape is trying to relieve: S&P futures +0.3%, Nasdaq-100 +0.5%, Dow +0.2%, with Treasuries paring losses as the market reads Warsh’s inflation resolve as at least a known quantity. But look at the backdrop before you trust the bounce — the 10-year is still sitting at 4.998%, right under 5% and the highest since 2023, WTI is holding $102, and the Fed just told you another hike is coming. That’s the exact setup where the morning after a hawkish Fed produces a relief pop that fades. Here’s the trap most traders will walk into today: they’ll read the green futures as the all-clear and chase the first candle. The move isn’t the bounce — it’s whether the bounce holds a level. So the job is simple. Mark 7,585 above and 7,500 below, let SPX prove which way it wants to go, and don’t confuse a relief pop with a reversal. No alignment, no trade.
What is the biggest catalyst for the market today?
The Fed hiked and the market is still digesting the message. In a unanimous 12-0 vote, Chair Kevin Warsh’s FOMC raised the target range 25bp to 3.75%-4.00%, the first increase since July 2023, and the Summary of Economic Projections showed officials expect one more hike before year-end. The decision itself was largely priced; what moved the tape was Warsh’s tone. Calling inflation sticky and saying nothing suggests the economy is slowing, he framed this as removing ‘a dose of accommodation,’ not a one-and-done. That’s why stocks faded into the close and why this morning’s bounce has to prove itself.
What key levels should traders watch today?
SPX 7,585 — the upside proof. This is the first hurdle above Wednesday’s 7,551.81 close. Reclaim it AND hold it after the open and the bounce has legs — buyers looking past the hawkish hike, with 7,620 and then 7,660 back in play. But this only counts once the cash market takes the level; the premarket green doesn’t. Don’t chase the pop toward it — make price prove it can hold above before you trust the long side. SPX 7,551 / 7,530 — the pivot and the balance line. 7,551.81 is Wednesday’s close and the axis the morning rotates around; 7,530 is the first support under it. Hold this zone and the bounce stays intact and two-way, ready to resolve higher. This is the ‘let it prove itself’ band — the tape lives here early, and the real signal is which side it leaves on. Patience beats prediction inside this range. SPX 7,500 — the invalidation line. Lose it and the relief pop has failed: the post-Fed selling resumes toward 7,460 and a deeper risk-off leg as the 10-year presses back toward 5%. Below 7,500 the hawkish read is back in control and the job flips to capital preservation. This is the number that separates a real bounce from a dead-cat pop — mark it, and respect it if it goes.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – September 17, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.