Tuesday, October 6, 2026 · 4:30 PM ET · MTC Market Close
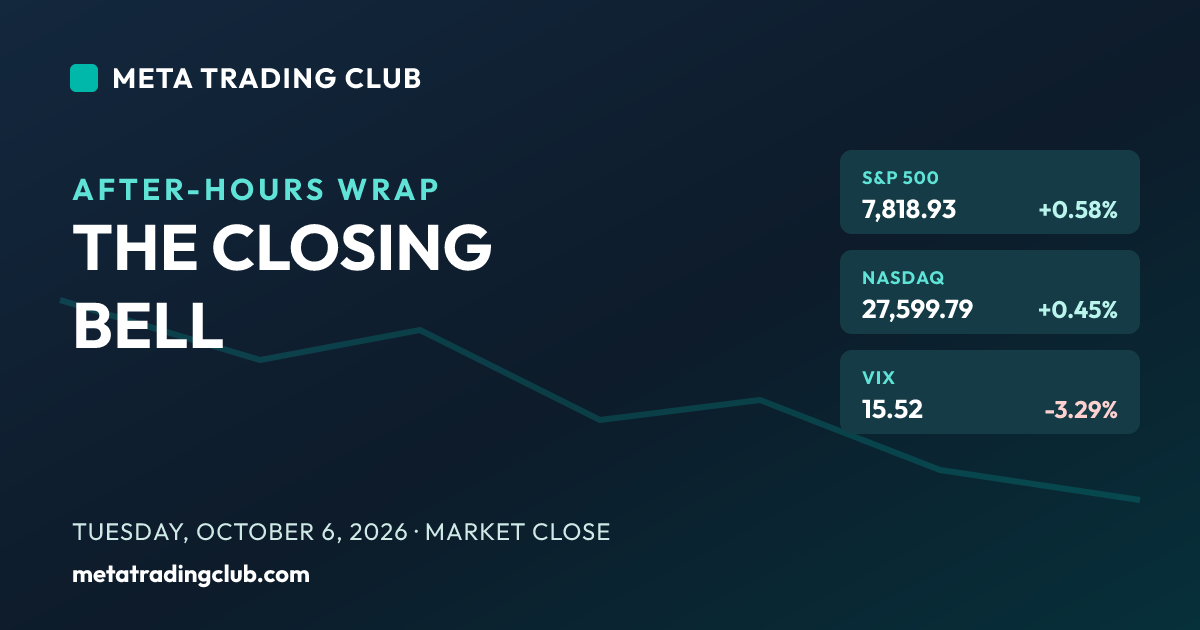
The big story in the stock market today: the S&P 500 printed its first-ever close above 7,800 on Tuesday, a fresh record that finally cleared the August high it had been chasing. The index rose 0.58% to 7,818.93, the Nasdaq added 0.45% to its own record at 27,599.79, and the Dow climbed 0.49% to 51,521.90. Cooling Treasury yields and easing oil did the heavy lifting: the 10-year backed off its 2002-era highs to settle near 5.275%, and crude pulled in from war-driven levels, letting the market focus on the one thing still working, AI and power-infrastructure earnings. Constellation Energy jumped more than 12% on a 20-year nuclear supply deal with Google, lighting up the independent power producers, while Nvidia pushed toward a $6 trillion market cap and AMD hit a record. But look one layer down and the tape was narrower than the headline. The Russell 2000 was the only major index to close red, down 0.57%, and healthcare and biotech got hammered, with the biotech ETF off more than 3%. So you get three records up top and a small-cap, healthcare rout underneath, the market rotating hard into the AI-and-nuclear theme rather than lifting everything. That leaves one line in charge of Wednesday: 7,800. Hold it and the breakout above the old August record is real. Lose it and today looks like a one-day false record. With ADP employment data due at 8:15 AM ET, the open has a catalyst.
The Closing Bell
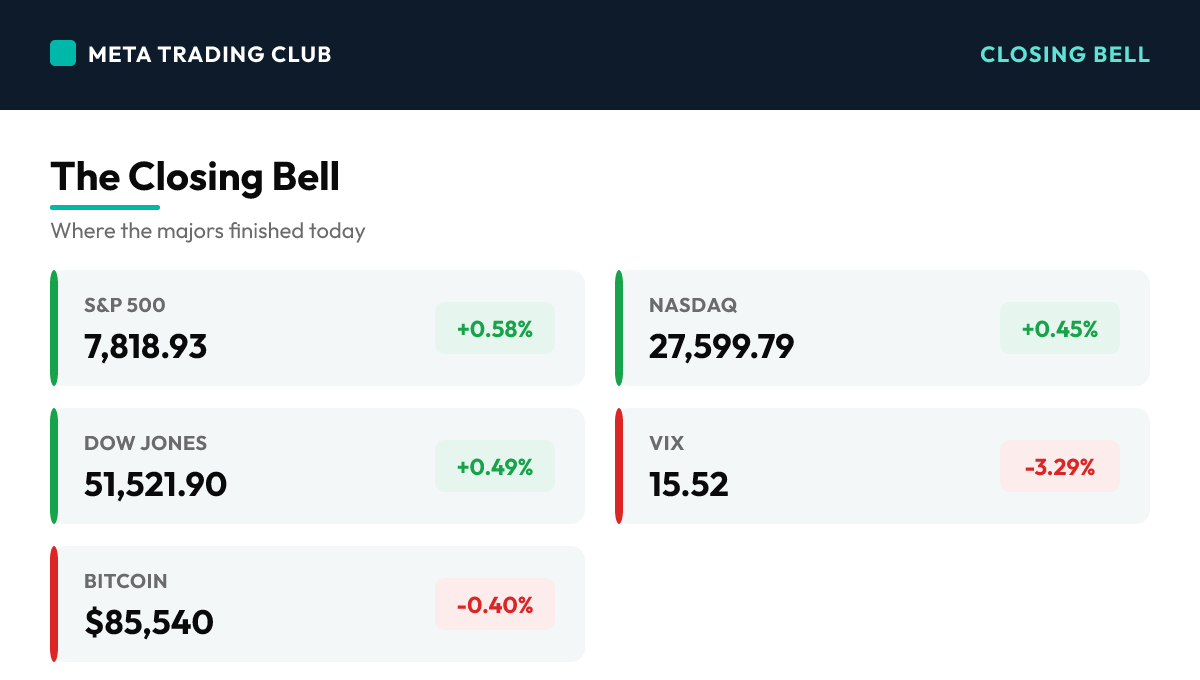
| Instrument | Close | Change | Note |
|---|---|---|---|
| S&P 500 | 7,818.93 | +0.58% | Added about 45 points to close at 7,818.93, its first finish ever above 7,800 and a fresh record that cleared the August high at 7,816.70 it had been stalling under for weeks. The breakout was helped by cooling yields and easing oil rather than a broad surge, with roughly 386 of the 500 names higher but the leadership concentrated in AI and power. That makes 7,800 the line that matters now: hold it and the old ceiling becomes a floor, lose it and price slips back under the August record and today reads as a false breakout. With ADP data at 8:15 AM ET, Wednesday has a catalyst to force the test. |
| Nasdaq | 27,599.79 | +0.45% | Rose about 122 points to a fresh record close of 27,599.79, extending Monday’s all-time high as the AI complex stayed firmly in control. Nvidia pushed toward a $6 trillion market cap and AMD hit a record, carrying the index even as the move was tightly themed. A second straight record is strength worth respecting, but the narrow leadership, chips and power rather than the full tape, is the same caution that has shadowed this entire run. The record is real; the breadth behind it is the question. |
| Dow Jones | 51,521.90 | +0.49% | Climbed about 253 points to 51,521.90, keeping pace with the broad tape as the blue chips joined the green day. On a session where the three large-cap majors all finished higher together, the Dow pulling its weight is a healthier sign than the mega-cap-only days earlier in the run. The gain was steady rather than spectacular, and it left all three big indexes in record or near-record territory into the close. |
| Russell 2000 | 2,830.97 | -0.57% | The lone holdout, down about 16 points to 2,830.97 and the only major index to close red. The weakness was concentrated in healthcare, where only a small fraction of the index’s health names advanced, dragging the small-cap gauge lower even as large caps set records. A red Russell on a record day for the S&P is the clearest tell of how selective today’s strength was: the money went to large-cap AI and power, not down the cap scale. Small caps did not confirm the breakout. |
| VIX | 15.52 | -3.29% | Eased about 3.3% to 15.52, a calm reading that fit the grind-higher tone of the session. Unlike Monday, when the fear gauge rose on a green day, Tuesday saw volatility fall as stocks climbed, the more normal pairing and a modest point in the bulls’ favor. A VIX in the mid-15s says the market is not pricing stress into the record, though a reading this low also leaves little cushion if the small-cap and healthcare cracks start to spread. |
| 10-Year Yield | 5.275% | -3.6 bps | Backed off to 5.275%, down about 4 basis points after touching levels last seen in 2002 above 5.3% earlier in the week. The retreat across the curve, with the front end falling hardest, was a direct tailwind for the record: lower yields ease the valuation pressure on the long-duration AI names that lead this tape. Still, a 10-year near 5.3% is restrictive by any measure, so the relief is a step down from extreme, not a green light. The rate ceiling is lower today, not gone. |
| WTI Crude | $89.62 | ~flat | Settled near $89.62, roughly flat on the day but well off the war-driven highs it had been pressing, after G7 nations announced the release of 100 million barrels of reserves over four months. The pullback in crude from recent peaks was one of the quiet reasons stocks could rally: cheaper oil eases the inflation and margin worry that had been capping the tape. Energy stayed off the leaderboard as a result, but a calmer crude price was a net positive for the broader market. |
| Gold | $4,187.60 | +0.74% | Firmed about $31 to near $4,187.60, up 0.74%, continuing to find a steady bid as a hedge even on a risk-on equity day. With the 10-year still near multi-decade highs and geopolitical risk around the Strait of Hormuz lingering, gold’s firmness reflects ongoing demand for a store of value against an uncertain backdrop. The metal quietly did its job while the spotlight went to the AI and power trade. Level approximate into the settle. |
| Bitcoin | $85,540 | -0.40% | Slipped about 0.4% to near $85,540, drifting slightly lower while equities set records. The mild pullback kept crypto on the opposite side of the stock tape again, a small reminder that the day’s risk appetite was concentrated in large-cap AI and power equities rather than spread across the full risk complex. Level approximate into the settle. |
Today’s Charts
Daily candlestick charts with 20/50/200-day moving averages — the index majors, the day’s biggest mover on each side, and the leading sector ETF.

Charts: Finviz (daily). Levels and overlays update through the next session.
Sector Scoreboard
What Drove The Day
This was the breakout the market had been waiting on, with an asterisk. The S&P 500 closed at 7,818.93, its first finish ever above 7,800 and a clean break of the August record it had failed to clear for weeks, while the Nasdaq extended its own record and the Dow added 0.49%. The fuel was macro relief: the 10-year yield backed off its 2002-era highs to 5.275%, crude eased from war-driven levels after a G7 reserve release, and the VIX fell to 15.52. That combination let the market lean into the one theme still delivering, AI and power infrastructure, with Constellation Energy up more than 12% on a 20-year nuclear deal with Google, Nvidia pushing toward a $6 trillion valuation, and AMD printing a record. But the tape was narrower than three records suggest. The Russell 2000 closed red, the only major index lower, and healthcare and biotech were routed, with the biotech ETF off more than 3%. So the breakout is real at the large-cap index level and unconfirmed below it. The S&P closed about 19 points above the old 7,816 record, which turns Wednesday into a clean binary: hold 7,800 and the breakout stands, lose it and the record fades back under resistance with ADP data at 8:15 AM ET as the likely trigger.
MAJOR HEADLINES AND CATALYSTS
Top Market-Moving Stories
- S&P 500 CLEARS 7,800 FOR THE FIRST TIME (Day) – The S&P 500 closed at 7,818.93, up 0.58%, its first finish ever above 7,800 and a clean break of the August record high at 7,816.70 it had been stalling under. Cooling Treasury yields and easing oil powered the move, with the Nasdaq and Dow also higher. The breakout is the real deal at the index level, which turns 7,800 into the line that decides whether it holds or fades.
- CONSTELLATION-GOOGLE NUCLEAR DEAL LIGHTS UP POWER (Day) – Constellation Energy jumped more than 12% after announcing a 20-year nuclear power purchase agreement with Google to bring 890 megawatts of new capacity onto the grid, committing over $4.3 billion to the build-out. The deal reframed independent power producers as the infrastructure play on the AI boom and sent the uranium complex up more than 5%. Power is the new leg of the AI trade.
- NVIDIA NEARS $6 TRILLION, AMD HITS A RECORD (Day) – Nvidia rose about 1.1% toward a roughly $5.84 trillion market cap, closing in on a $6 trillion valuation no company has reached, helped by a $150 billion buyback authorization. AMD rallied more than 4% to a record above $658 as Citi lifted its target to $800. The AI chip leaders stayed firmly in charge of the tape, the engine behind the Nasdaq’s second straight record.
- SMALL CAPS AND HEALTHCARE DIVERGE (Day) – The Russell 2000 closed down 0.57%, the only major index in the red, dragged by a healthcare rout that left the biotech ETF off more than 3%. Moderna fell over 6% and Illumina nearly 6%. On a record day for the S&P, a red small-cap index and a hammered healthcare sector are the clearest signs that today’s strength was a narrow rotation into AI and power, not a broad lift.
AFTER-HOURS EARNINGS SPOTLIGHT
A Light Post-Close Slate
- NO MAJOR S&P NAMES AFTER THE BELL (AH) – Tuesday’s post-close earnings slate was light, with no index-moving S&P 500 reports hitting the tape after 4:05 PM ET. That leaves the day’s breakout above 7,800 and the small-cap divergence as the full story, and keeps attention on the technical setup and tomorrow’s data rather than a fresh earnings catalyst into Wednesday.
- FACTSET SEES ~30% EARNINGS GROWTH AHEAD (AH) – A less-discussed support under this rally is the earnings backdrop: FactSet estimates for the upcoming season have been revised up toward nearly 30% growth, following roughly 50% growth in Q2. Concentrated in the AI names, that profit growth is part of why the tape can push to records against a 5.3% 10-year. It is the fundamental leg beneath an otherwise technically stretched move.
WHAT IT SETS UP FOR WEDNESDAY
One Line, One Data Print
- 7,800 IS THE LINE THAT MATTERS (AH) – The S&P closed at 7,818.93, about 19 points above the old August record at 7,816.70. That flips the former ceiling into support. Hold 7,800 on Wednesday and the breakout is confirmed, with blue sky above the prior record. Lose it and price slips back under resistance, turning today’s historic close into a false breakout. The first clean move relative to 7,800 at the open tells you which it is.
- ADP EMPLOYMENT AT 8:15 AM IS THE CATALYST (AH) – Unlike Monday’s headline-free tape, Wednesday opens with the ADP employment report at 8:15 AM ET, a read on private hiring and a precursor to the official jobs data. A soft number would reinforce the cooling-yield story that fueled today’s breakout. A hot print could push yields back toward their 2002 highs and pressure the long-duration AI leadership that is carrying this record.
Winners & Losers
Winners
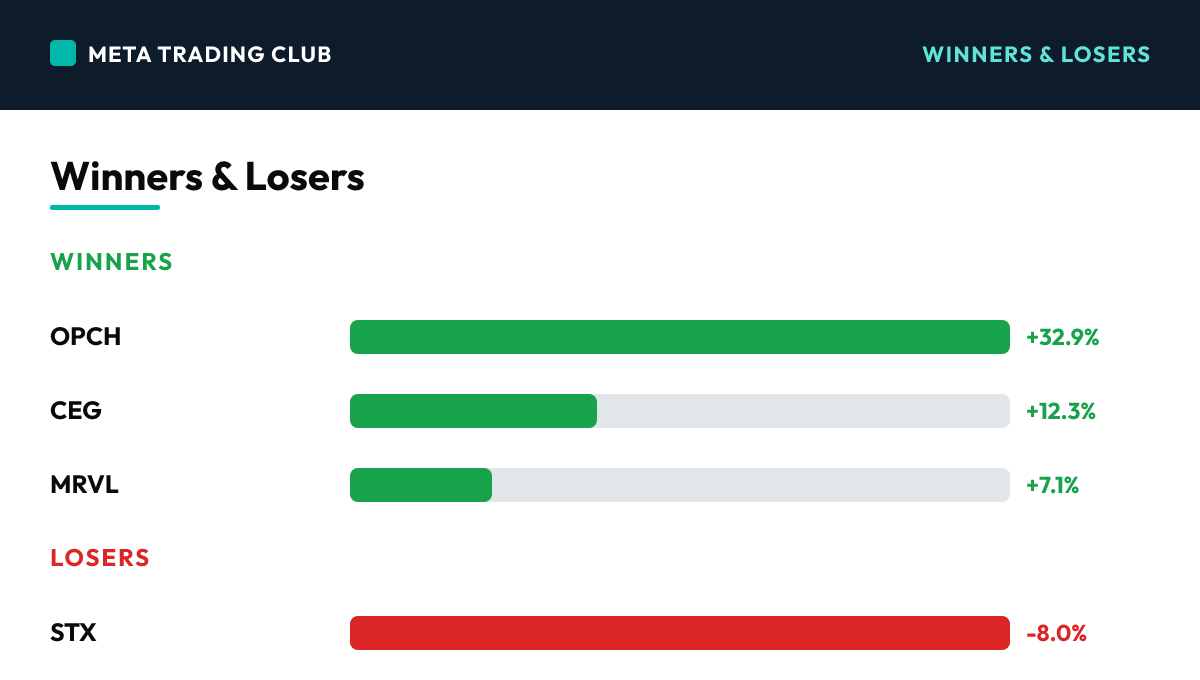
| OPCH | +32.9% | Option Care Health was the day’s standout large-cap gainer, surging about 32.9% after a report that McKesson and private equity firm Clayton Dubilier & Rice are closing in on a buyout worth more than $5 billion including debt. The home-infusion provider’s jump was an M&A story rather than a market-wide signal, but it topped the leaderboard and was a rare bright spot in an otherwise battered healthcare tape. When a sector is getting routed, a takeout bid is one of the few things that still lifts a name. | |
| CEG | +12.3% | Constellation Energy rose about 12.3% after announcing a 20-year nuclear power purchase agreement with Google to bring 890 megawatts of new capacity onto the grid, committing over $4.3 billion to the build-out. The deal was the catalyst of the day, reframing nuclear and independent power producers as the infrastructure play on the AI boom and lifting the entire utilities and uranium complex. It is the clearest sign yet that the AI trade is expanding beyond chips into the power that feeds them. | |
| MRVL | +7.1% | Marvell Technology gained about 7.1% after dramatically raising its long-term revenue targets and offering bullish forecasts for AI infrastructure at its Investor Day. The move fit the day’s dominant theme, with the AI and semiconductor complex staying firmly in the lead. A sharp jump on upgraded guidance shows the market is still willing to pay up for credible AI-infrastructure growth stories, even with the broader tape narrowing. |
Losers
| STX | -8.0% | Seagate Technology tumbled about 8.0%, the worst of the large-cap decliners, amid ongoing concerns about a potential expansion of Toshiba’s hard-disk-drive capacity. The storage names stayed under pressure even as AI compute names set records, continuing the split inside technology where the money chases AI and compute and leaves storage behind. A near-8% drop in a chip-adjacent name on a record day underscores how selective the sector’s strength really is. | |
| WDC | -6.9% | Western Digital fell about 6.9% alongside Seagate on the same Toshiba capacity worries, confirming the storage and memory group as a clear loser inside technology. The pair falling together while AI chips and power names flew is the divergence of the session: the strength concentrated in the AI winners and left the commodity-storage corner behind. A record on the chip leaders can mask steep losses in the names that are out of favor. | |
| MRNA | -6.1% | Moderna dropped about 6.1% on profit-taking after the stock hit a fresh 52-week high, part of the broader healthcare and biotech rout that dragged the Russell 2000 into the red. The pullback came even as the biopharma prepares to rejoin the Nasdaq-100 before Friday’s open, a reminder that a strong story can still see sharp giveback when a whole sector turns. Healthcare was the day’s clear soft spot under the record. |
What It Sets Up For Tomorrow
Levels Into Tomorrow
- S&P 500 7,800 – THE LINE THAT DECIDES IT. Price closed at 7,818.93, just above the round 7,800 level and the old August record at 7,816.70. This is the single most important level on the page. Hold 7,800 and the breakout above the prior record is confirmed, turning a multi-week ceiling into a floor and opening blue sky. Lose it, especially if small caps and healthcare keep cracking, and the market is telling you the record was a one-day overshoot. The first clean move relative to 7,800 at Wednesday’s open tells you whether the breakout is real.
- S&P 500 7,850 – THE NEXT TARGET IF IT HOLDS. With the August record cleared, the path above is open and 7,850 is the first logical objective on continuation. A push toward and through it on steady yields would confirm the breakout has legs and that the macro relief, lower rates and calmer oil, is translating into durable upside rather than a single record print. This is the level that proves today was the start of a new leg, not the end of the old range.
- S&P 500 7,750 – THE SHELF BELOW. The first real support if 7,800 gives way. A loss of 7,750 would confirm that the breakout failed and that the red Russell and routed healthcare were the honest signals under the record. This is where a false breakout turns into a genuine pullback, and where the rate-sensitive and lower-quality names would likely lead the move lower. Below it, the prior range comes back into play.
Bull case: The breakout is real and it finally has macro help. The S&P cleared 7,800 and the August record for the first time, the Nasdaq and Dow joined, and it happened as the 10-year backed off its 2002-era highs, crude eased, and the VIX fell to 15.52. The AI trade keeps delivering, with Nvidia nearing $6 trillion and the Constellation-Google deal opening a whole new power-infrastructure leg, and FactSet sees nearly 30% earnings growth ahead. If yields stay calm on Wednesday’s ADP print, the S&P holds 7,800, the old ceiling becomes support, and the path opens toward 7,850 and beyond. In this read, the small-cap softness is rotation into the leaders, not a warning.
Bear case: A record on a red Russell is a record to question. While the S&P set an all-time high, the small-cap index closed lower, healthcare was routed, and the biotech ETF fell more than 3%. That is a narrow, rotation-driven breakout, not a broad one, and narrow breakouts are the ones that fail. A 10-year still near 5.3% leaves little room for error, and a hot ADP print Wednesday could send yields back toward their highs and hit the long-duration AI leadership that is carrying everything. If breadth does not improve and the S&P loses 7,800, today’s historic close becomes a false breakout and the move back toward 7,750 starts with the healthcare and small-cap cracks leading.
Risks Into Tomorrow
- A record on a red Russell is a breakout that still needs proof — The S&P 500 closed above 7,800 for the first time ever today, a genuine record and a clean break of a level it had failed to clear for weeks. But the Russell 2000, the small-cap index, closed red, the only major index lower on the day, and healthcare was routed underneath it. That single divergence reframes the whole session. A breakout is supposed to be the market voting with conviction, and when the biggest names make history while an entire index and sector go the other way, the vote is split. That does not make the record fake. The large-cap breakout is real and it finally cleared resistance. But it does make it a narrow breakout, driven by rotation into AI and power rather than a broad lift across the market, and narrow breakouts are the ones most likely to fail. The discipline is to treat a record on poor breadth as a reason to demand confirmation, not as a signal to chase. If the small caps and healthcare stabilize and 7,800 holds, the breakout earns its stripes. If they keep cracking and 7,800 gives way, today’s historic close becomes a false breakout. The level, not the headline, settles it. No alignment between the record and its internals means you wait for the breadth to catch up.
- When the ceiling becomes the floor, respect the retest — For weeks the S&P could not close above its August record at 7,816. Today it finally did, finishing at 7,818.93. That matters, because in trading, an old ceiling that gets broken is supposed to flip into a new floor. But the flip is not confirmed on the breakout day itself. It is confirmed on the retest, when price comes back down to the old resistance level and the market decides whether it now holds as support. That retest is exactly what 7,800 represents into Wednesday. The mistake traders make is treating the breakout close as the finish line and piling in at the highs. The better approach is to understand that the most reliable part of a breakout is often the pullback that holds the broken level, not the initial pop through it. If the S&P comes back to 7,800 and buyers step in, you have your confirmation and a defined risk point right below. If it slices back through and can’t reclaim, the breakout failed and you have your answer just as clearly. Either way, the level does the work. You do not need to predict which it will be. You mark 7,800, you let price come to it, and you let the reaction tell you whether the record was the start of something or a one-day overshoot. That is what it means to trade the level instead of the headline.
- Falling yields gave you the breakout, so watch the yields — Today’s record did not happen in a vacuum. The single biggest reason the S&P could finally clear 7,800 was that the 10-year Treasury yield backed off its 2002-era highs above 5.3% to settle near 5.275%, and crude eased from its war-driven levels. Lower yields relieve the valuation pressure on the long-duration AI names that lead this tape, and that relief was the fuel. The lesson is that when a move is driven by a specific macro input, you keep your eye on that input, because it will also be what takes the move away. The breakout leaned on falling rates, so rising rates are the most direct threat to it. That is why Wednesday’s ADP employment report at 8:15 AM ET matters more than a light earnings slate. A soft hiring number extends the cooling-yield story and gives the record room to run. A hot number snaps yields back toward their highs and hits the leadership hardest, and the S&P could be back under 7,800 before most traders have finished their coffee. The discipline is to know what your move depends on and to watch that thing like a hawk. A breakout built on falling yields is only as safe as the next yield print. You let the bond market and the level, not your hope, decide whether you are in. No alignment until the rates and the price agree.
Frequently Asked Questions
How did the S&P 500 close today?
On Tuesday, October 6, 2026, the S&P 500 closed at 7,818.93 (+0.58%), with the VIX at 15.52. The big story in the stock market today: the S&P 500 printed its first-ever close above 7,800 on Tuesday, a fresh record that finally cleared the August high it had been chasing.
What drove the market today?
S&P 500 CLEARS 7,800 FOR THE FIRST TIME (Day) – The S&P 500 closed at 7,818.93, up 0.58%, its first finish ever above 7,800 and a clean break of the August record high at 7,816.70 it had been stalling under. Cooling Treasury yields and easing oil powered the move, with the Nasdaq and Dow also higher. The breakout is the real deal at the index level, which turns 7,800 into the line that decides whether it holds or fades.
What levels matter for tomorrow?
S&P 500 7,800 – THE LINE THAT DECIDES IT. Price closed at 7,818.93, just above the round 7,800 level and the old August record at 7,816.70. This is the single most important level on the page. Hold 7,800 and the breakout above the prior record is confirmed, turning a multi-week ceiling into a floor and opening blue sky. Lose it, especially if small caps and healthcare keep cracking, and the market is telling you the record was a one-day overshoot. The first clean move relative to 7,800 at Wednesday’s open tells you whether the breakout is real. S&P 500 7,850 – THE NEXT TARGET IF IT HOLDS. With the August record cleared, the path above is open and 7,850 is the first logical objective on continuation. A push toward and through it on steady yields would confirm the breakout has legs and that the macro relief, lower rates and calmer oil, is translating into durable upside rather than a single record print. This is the level that proves today was the start of a new leg, not the end of the old range. S&P 500 7,750 – THE SHELF BELOW. The first real support if 7,800 gives way. A loss of 7,750 would confirm that the breakout failed and that the red Russell and routed healthcare were the honest signals under the record. This is where a false breakout turns into a genuine pullback, and where the rate-sensitive and lower-quality names would likely lead the move lower. Below it, the prior range comes back into play.
How does Meta Trading Club prepare for the next session?
We wrap every session and carry the read forward through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
New to this? Start with the free training.
Learn how we read the market before you risk a dollar — our free education library and ebook break down the fundamentals step by step.
Free education → Get the free ebookThe session’s over. The prep isn’t.
This is how MTC members close each day — wrap what happened, mark the levels, and carry one clean read into tomorrow. If you want to build that habit and qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process. It’s application-based — see if it’s a fit.
Explore the MTC Incubator → Apply nowSources: Yahoo Finance, CNBC, TheStreet, Benzinga and Investing.com closing coverage for October 6, 2026.. For educational purposes only. Not financial advice.