Tuesday, October 6, 2026 · 8:45 AM ET · MTC Market Intelligence
The stock market today opens on a record and a warning at the same time. The Nasdaq Composite closed Monday at 27,477.31, up 1.05%, a fresh all-time high, with the S&P 500 up 0.66% to 7,773.95 and the Dow up 0.18% to 51,267.90 — the rally still running on a soft September jobs report (+29,000) that cut the odds of another Fed hike. This morning futures lean modestly higher: Dow futures up about 0.33%, S&P 500 futures up 0.21%, and Nasdaq-100 futures up roughly 0.25%, with the AI-chip complex (AMD, Nvidia, Broadcom) leading premarket. But look under the record. The 10-year Treasury yield is sitting near 5.27%, close to a 24-year high, and oil is holding firm with Brent above $100 after Iran kept its seven conditions for reopening the Strait of Hormuz — WTI near $89.62. And the VIX is down near 15.31, a calm, almost complacent reading stacked on top of real macro pressure. That is the whole lesson of this tape: a record close tells you where price has been, not where it’s going, and a market this quiet with yields this high is strength built on thin ice. The calendar is light — August trade balance at 8:30 AM ET (a deficit near $102 billion expected) and Fed speakers Williams, Bowman and Logan carry the day, with no CPI and no payrolls this week. So this is a reaction day. SPX 7,800 is the record-high wall, 7,774 is Monday’s close and the axis, and 7,720 is the shelf that keeps a pullback orderly. Don’t buy the headline — let the level hold first. No alignment, no trade.
Market Snapshot
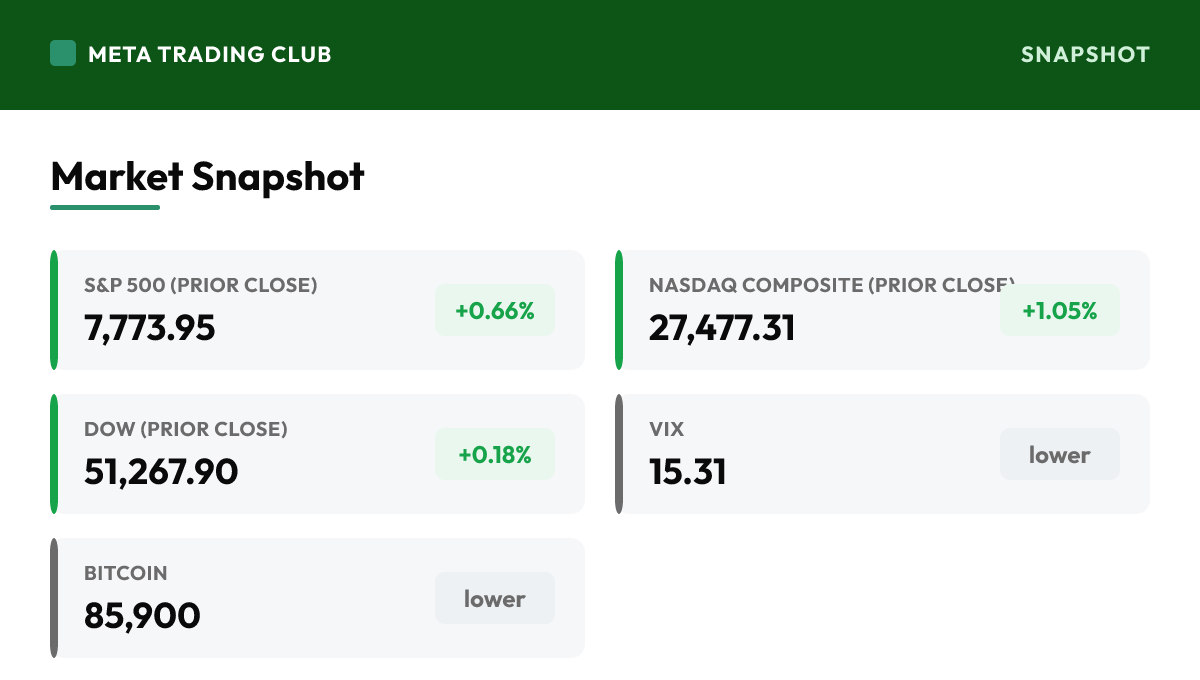
| Instrument | Level | Change | Note |
|---|---|---|---|
| S&P 500 (prior close) | 7,773.95 | +0.66% | Closed Monday at 7,773.95, up 0.66%, extending the jobs-driven rally and leaving the index less than 1% from a record high. That’s a strong close, but it’s sitting on top of a 10-year near 5.27% — exactly the pressure that’s supposed to cap a near-record tape. This morning S&P 500 futures are up about 0.21%, a modestly higher open. The axis is 7,774: hold and build above it and the record-high test stays alive; fade back through it and the rising-yield worry is starting to show. Trade the reaction at the level, not the premarket tick. |
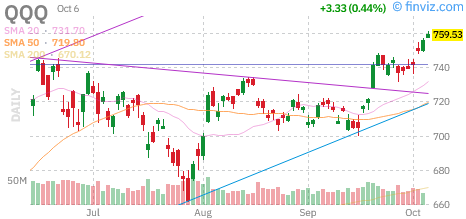
| Nasdaq Composite (prior close) | 27,477.31 | +1.05% | Printed a fresh record close Monday at 27,477.31, up 1.05%, as megacap tech and the AI-chip complex led the tape to new highs. This morning Nasdaq-100 futures are up around 0.25% with AMD, Nvidia and Broadcom bid premarket. But tech is also the highest-duration corner of the market, so a 10-year pinned near 24-year highs is the first thing that can pull it back. That’s the tension: tech leads when the rate-cut hope is the story and gives back first when the bond market reasserts. Lead or lag off the open tells you which force owns the session. |
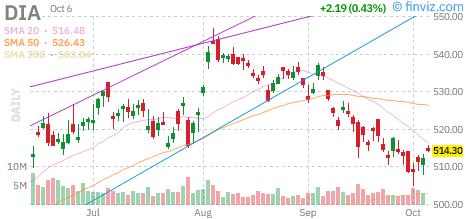
| Dow (prior close) | 51,267.90 | +0.18% | Closed Monday at 51,267.90, up 0.18% or about 91 points — the blue chips tagging along on the softer-jobs rally without leading it. This morning Dow futures are the firmest major, up about 0.33%. The value-heavy, rate-sensitive index is the one most exposed to a 10-year near 5.27%, so watch whether the Dow can hold its gains or whether rising yields pull it lower. Broad participation across the Dow, Nasdaq and small caps keeps the record-high story credible; a narrow, tech-only tape is the first warning sign. |
| S&P 500 Futures | — | +0.21% | Up about 0.21% this morning, pointing to a modestly higher open after Monday’s push and the Nasdaq’s record close. It’s a drift higher, not a thrust — the market is leaning toward the highs with yields and oil both elevated. Don’t over-read a small green premarket. The signal today is how cash trades the 7,774 axis after the open and whether it can press 7,800: hold and build and the record-high test is live; stall and fade back and the rising-yield worry is finally showing up in price. |
| Nasdaq-100 Futures | — | +0.25% | Up about 0.25%, firm with the AI-chip complex leading premarket. High-multiple tech is the leadership when the rate-cut story runs and the first to wobble when the bond market tightens the screws. Watch the Nasdaq as the cleanest tell on which force is winning: if the chips keep the bid and tech leads off the open, the dovish read still owns the tape; if it rolls over while the 10-year climbs, the rate pressure is the real driver of the day. |
| Russell 2000 Futures | — | +0.15% | Up about 0.15%, holding steady with the broader risk-on tone. Small caps are the most rate-sensitive group there is, so a Russell holding firm while the 10-year sits near 5.27% is a quiet sign the market isn’t yet pricing a yield-driven breakdown. Use the Russell as a breadth tell: if small caps join a push to new highs, participation is broad and the move is healthier; if they lag or roll over while yields climb, the rally is narrowing and leaning entirely on megacap tech. |
| VIX | 15.31 | lower | Easing about 6.6% toward 15.31 this morning, a low, calm reading as the options market prices very little fear into a tape sitting at records. That’s the detail worth sitting with: a VIX near 15 stacked on top of a 10-year near 24-year highs and oil above $100 is conditional calm — comfortable until it isn’t. Low volatility is not low risk; it’s the market pricing none. Treat it as a tell, not an all-clear: the quiet can break fast if the 10-year pushes higher or a headline hits. |
| WTI Crude | 89.62 | firm | Holding near $89.62 this morning with Brent still above $100 after Iran kept its seven conditions for fully reopening the Strait of Hormuz. Elevated oil is one half of the pressure sitting on this tape — it feeds the inflation worry that keeps the 10-year high. Track crude as a macro swing factor: a sustained push back toward and above $100 keeps upward pressure on yields and the inflation story, while a real roll-over would take some heat off the bond market and give stocks more room to test new highs. |
| 10-Yr Yield | 5.27% | higher | Near 5.27% this morning, sitting close to a 24-year high and the single most important number on the screen today. This is the force that should be capping a record-setting stock market, and the fact that stocks keep making new highs anyway is the whole story of this tape. Mohamed El-Erian warned this weekend about the ‘structural repricing’ in bonds spilling into credit and spread risk. Watch the 10-year more closely than any single stock: keep climbing and it eventually caps the rally; back off and it hands stocks room to run. |
| Bitcoin | 85,900 | lower | Easing about 0.7% near $85,900 as the highest-beta risk asset drifts slightly while equities sit at records. Crypto holding in the mid-$80Ks with yields near 24-year highs is a modestly constructive risk tell — the speculative end of the curve isn’t flinching. Treat Bitcoin as a sentiment gauge today: if it firms alongside equities, risk appetite is intact and the dovish read has support; if it rolls over intraday, it’s often the first place a broader risk-off shows up before it reaches the index. |
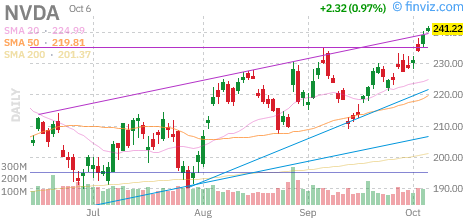
Charts to Watch
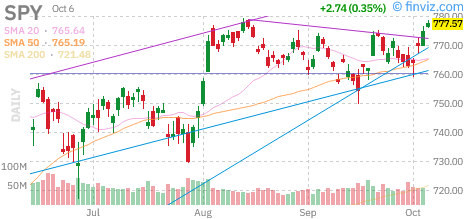
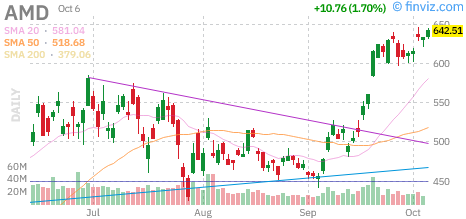
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
Overnight & Global Markets
Monday closed on a record. The Nasdaq Composite jumped 1.05% to 27,477.31, an all-time high, with the S&P 500 up 0.66% to 7,773.95 and the Dow up 0.18% to 51,267.90, the rally still carried by a soft September jobs report (+29,000 payrolls) that trimmed the odds of another Fed hike. That leaves the S&P less than 1% from its own record. The problem is what the record is sitting on: the 10-year Treasury yield near 5.27%, close to a 24-year high, and oil holding firm with Brent above $100 after Iran kept its seven conditions for reopening the Strait of Hormuz. Two forces still pulling opposite ways — a dovish Fed story lifting stocks, a bond-and-oil backdrop that should be dragging them down. This morning the risk-on side has a slight edge: Dow futures up about 0.33%, S&P 500 futures up 0.21%, and Nasdaq-100 futures up 0.25%, led by the AI chips. And the VIX is down near 15.31 — calm, almost complacent. The calendar is light: August trade balance at 8:30 AM ET (a deficit near $102 billion expected) and Fed speakers Williams, Bowman and Logan, with no CPI and no payrolls this week. That puts the weight on the reaction, not a fresh catalyst. The lesson of a record close is that it tells you where price has been, not where it’s going. Mark 7,800 as the record-high wall, 7,774 as Monday’s close and the axis, and 7,720 as the shelf. Don’t buy the headline — let the level hold first.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The whole tape runs through one contradiction: the Nasdaq just printed a record close (27,477.31, +1.05%) and the S&P 500 sits under 1% from its own record, while the 10-year Treasury yield is near 5.27%, close to a 24-year high. Monday’s push extended a rally built on a weak September jobs report (+29,000 payrolls) that cut the odds of another Fed hike — CME FedWatch has been pricing only about a one-in-five chance of an October move. That dovish read is what’s kept stocks bid. But a yield near 24-year highs is exactly the kind of pressure that historically caps a record market, and this morning the tape is leaning higher anyway: Dow futures +0.33%, S&P 500 +0.21%, Nasdaq-100 +0.25%, led by the AI chips.
- Geopolitics is the second force on the tape. Iran kept its seven conditions for fully reopening the Strait of Hormuz, holding a firm line despite mediated proposals, and Brent crude is holding above $100 with WTI near $89.62. Tehran has also warned of a stronger military response to any U.S. strikes amid reports of additional American troop deployments. Elevated oil feeds straight into the inflation-and-yield loop that’s keeping the 10-year high, so the Hormuz story and the bond market are really the same risk wearing two hats. Watch crude and the 10-year together — they’re the macro engine under today’s session.
- The calendar is light, which puts the weight on the reaction. August trade balance lands at 8:30 AM ET, with a deficit near $102 billion expected versus $88.6 billion prior, and the day’s real signal is Fed commentary — Williams, Bowman and Logan all speak, with Logan at a Global Perspectives event this evening. There’s no CPI and no payrolls this week, so Fed speakers and Treasury auctions carry the weight instead of fresh data. Penguin Solutions (PENG) is the notable earnings name today, but there’s no heavyweight print to swing the tape. Today is about how price digests the record against a 24-year-high yield — not about a new catalyst.
Stock-Specific
- The AI-chip complex is the leadership story premarket. AMD, Nvidia (NVDA) and Broadcom (AVGO) are all bid this morning, carrying forward the capex-driven semis trade that drove Monday’s Nasdaq record. This isn’t a single-name catalyst — it’s the market’s highest-conviction theme reasserting itself at the highs. Trade the chips on their own levels and respect that they’re also the most rate-sensitive leadership there is: a 10-year that pushes higher hits this group first. Lead off the open and the record-high test stays alive; roll over and it’s the cleanest sign the yield pressure is biting.
- Nike (NKE) is the standout decliner, falling sharply premarket after a fiscal Q1 report that cut full-year guidance — management now sees a high-single-digit revenue decline for fiscal 2027, driven by a 26% revenue drop in Greater China and persistent weakness in the core Sportswear and Jordan brands. It’s a clean, company-specific catalyst and a real read on the consumer and China exposure, not a market-direction signal. Trade it on its own levels; a guidance-cut gap can keep bleeding or stabilize once the sellers clear. Isolate it from the broad-tape read.
- Two more single-name movers worth isolating: Liquidia (LQDA) is falling after a U.S. District Court ruled its flagship drug Yutrepia infringes two valid patent claims held by United Therapeutics — a binary legal catalyst that resets the stock’s risk. Cheniere Energy (LNG) is softer on investor concern over non-cash derivative losses and the volatility tied to Middle East tensions. Both are self-contained stories with their own drivers. Trade them on their own levels rather than treating them as reads on where the index is headed today.
Global and Macro
- The bond market is the macro story everything else bends around. The 10-year near 5.27% — close to a 24-year high — is the force that should be capping a record stock market, and the fact that it hasn’t yet is what makes this tape unusual. Mohamed El-Erian warned this weekend that fixed-income volatility is being driven by a ‘long-term structural repricing’ from heavy supply and weaker traditional demand, and that interest-rate risk is starting to spill into credit and spread risk as high-yield spreads widen. The belief that surging risk-free rates can stay isolated from stocks, he said, is ‘now visibly under pressure.’ Watch the 10-year as the real driver of every risk asset today.
- Here’s the resilience backdrop worth holding in mind. The market has, in one strategist’s words, ‘had every reason to sell off and it hasn’t’ — yields at 24-year highs, oil near $100, narrowing breadth — and the path of least resistance has stayed higher. That doesn’t cancel the risk; it frames it. The lesson for today is not to assume the record is a green light and chase it, nor to assume the long-called pullback has finally arrived just because the macro looks heavy. A record close tells you where price has been. Let price confirm where it’s going before you trade it in either direction.
TECHNICAL ANALYSIS
S&P 500 Key Levels
- The S&P closed Monday at 7,773.95, less than 1% from a record high, and futures point to a modestly higher open. The level that matters on the upside is 7,800 — the record-high wall. A push through and a hold above it on real trade, with breadth from the Dow and small caps rather than tech alone, is the market saying it can break to new highs even against a 24-year-high yield. That’s a powerful signal if it comes. But don’t anticipate it: let cash reclaim and hold the level before you trust the breakout, because a near-record tape stalling in front of resistance with yields elevated is exactly where failed breakouts happen.
- First support is 7,774 — Monday’s close and the axis the session pivots on. Hold above it and the record-high test stays alive. Below that, 7,720 is the shelf that keeps a pullback orderly — roughly Friday’s close and the first real floor. Lose 7,720 and fail to reclaim it and the rising-yield pressure is finally showing up in price, opening the tape toward the next leg lower. Mark 7,800 above and 7,720 below: inside that range is the market deciding; outside it is the real signal. Trade the edges, not the middle.
Sector and Sentiment
- The leadership read this morning is the key tell. The AI-chip complex is leading and small caps are holding firm — a broad-ish risk-on tone that, if it sticks, is what a credible push to new highs looks like. For a breakout to be real you want breadth: the Dow, small caps and cyclicals participating, not just megacap tech carrying the tape. If the chips lead green off the open and drag everything up, the dovish read is still in control; if the rally narrows to a handful of names while yields climb, that’s the first sign the move is running out of fuel. Watch who’s along for the ride, not just how far it goes.
- The VIX easing toward 15.31 says the options market is pricing almost no fear into a tape sitting at records against real macro pressure. That combination — low volatility over a 24-year-high yield and a $100 oil price — is the definition of conditional calm: comfortable until it isn’t. Practically, respect that the quiet can break fast if the 10-year pushes higher or a Hormuz headline hits, keep the yield on your screen as the real driver, and let SPX prove its levels on the reaction before you commit to either side. Low volatility is not low risk — it’s the market pricing none.
TODAY’S ECONOMIC CALENDAR
Key Releases (ET)
- It’s a light data day with one scheduled release and a run of Fed speakers. August trade balance lands at 8:30 AM ET, expected to widen to a deficit near $102 billion from $88.6 billion prior — a second-tier number that rarely moves the tape on its own but feeds the growth-and-tariff narrative. The real signal today is Fed commentary: Williams, Bowman and Logan all speak, with Logan at a Global Perspectives event this evening. With no CPI and no payrolls this week, every word from the Fed and every Treasury auction carries more weight than usual for the bond market and, by extension, for stocks.
- Beyond today, the week builds toward Wednesday. The September FOMC meeting minutes land Wednesday at 2:00 PM ET and are the marquee event — the market will read them for how divided the committee is on another hike against a 24-year-high yield. Weekly jobless claims come Thursday and University of Michigan consumer sentiment Friday, with more Fed speakers throughout. For today, with no major catalyst to rescue or break the move, trade the reaction and the levels — and let the week’s bigger events, especially the minutes, come to you rather than front-running them.
Earnings Today
- Penguin Solutions (PENG) is the notable name reporting today, with Rosenblatt reaffirming a Buy and an $80 target into the print on beat-and-raise expectations — a clean single-stock event to trade on its own levels rather than a read on the broad tape. Beyond that it’s a quiet earnings day before Q3 season kicks off in earnest in mid-October. With no heavyweight print to swing the session, the macro tug-of-war between a dovish Fed and a 24-year-high yield owns the tape, and the single names — the chips higher, Nike lower — are texture, not direction.
- Look ahead, not just at today. The heart of Q3 season arrives mid-October with the big banks and the megacap names, and those prints will be the first real test of whether high yields and elevated oil are starting to bite corporate results. Nike’s guidance cut this morning — a high-single-digit revenue decline driven by China — is an early data point on the consumer worth filing away. For today, trade the reaction and the SPX levels; use the week-ahead FOMC minutes and the start of earnings season as the reasons to keep risk measured rather than overcommitting early.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,800 — the record-high wall. The level just above Monday’s 7,774 close and the resistance the market has to clear to print a fresh S&P record. A push through AND a hold above it on real trade, with breadth from the Dow and small caps rather than tech alone, is the tape saying it can break out even against a 24-year-high yield — a powerful signal, and the door opens higher if it holds. But don’t anticipate the breakout. Make price take and hold 7,800 after the open before you trust the long side; a record tape stalling at resistance with yields elevated is exactly where failed breakouts live.
- SPX 7,774 — the axis. Monday’s record close and the pivot the whole session turns on. Hold above it and the record-high test stays alive; this is the ‘let it prove itself’ zone where a market weighing a dovish Fed against a 24-year-high yield tends to chop. The real signal is which side SPX leaves this level on once the open settles and the Fed speakers hit the tape. Inside the range is noise; the move that follows is the trade. Patience beats forcing a position while the tape is still deciding which macro force it wants to trade.
- SPX 7,720 — the shelf that keeps a pullback orderly. The first real floor below the axis, roughly Friday’s close. Hold it and a dip is just a dip inside an uptrend. Lose 7,720 and fail to reclaim it and the rising-yield pressure is finally showing up in price — the market is starting to trade the 5.27% 10-year as the thing that caps the rally, and the tape opens toward the next leg lower. Below 7,720 the job shifts to capital preservation. Mark it, and respect it if it goes.
Bull case: The market keeps doing what it’s done for weeks: shrugging off the macro pressure. The 10-year holds or backs off 5.27%, the AI-chip leadership stays bid, and SPX clears 7,800 to confirm a fresh record. Breadth broadens — the Dow, small caps and cyclicals join rather than megacap tech carrying it alone — and the dip-buyers stay in control. In this scenario the resilience that’s defined the tape wins again: the dovish-Fed read keeps its grip, the record extends, and the market proves once more that the path of least resistance is higher, even with yields near a 24-year high and oil above $100.
Bear case: The bond market finally wins. The 10-year pushes further above 5.27%, a Fed speaker leans hawkish, or a Hormuz headline lifts oil — and the rate pressure everyone’s been warning about shows up in price at last. SPX fails at 7,800, fades back through 7,774, and loses 7,720 as the AI chips — the longest-duration, most rate-exposed leadership — roll over first. El-Erian’s warning about rate risk spilling into credit starts to look prescient, the VIX snaps off its complacent lows, and the pullback strategists have called for weeks finally arrives. A failed record-high test on rising yields is a clean short setup.
Premarket Movers
Gainers
| AMD | Advanced Micro Devices | higher premarket with the AI-chip complex leading after Monday’s Nasdaq record | Bid premarket alongside Nvidia and Broadcom as the AI-chip complex carries forward the capex-driven semis trade that drove Monday’s Nasdaq record close. This is the market’s highest-conviction theme reasserting itself at the highs rather than a single-name catalyst. Trade AMD on its own levels and respect that chips are also the most rate-sensitive leadership there is — a 10-year that pushes higher hits this group first. Lead off the open and the record-high test stays alive; roll over and it’s the cleanest sign the yield pressure is starting to bite. |
| NVDA | Nvidia | higher premarket, extending record-chasing AI leadership | Higher premarket, extending the record-chasing leadership that has anchored the Nasdaq’s push to new highs on accelerating hyperscaler AI capex. Nvidia is the bellwether for the entire AI trade, so its tape is a read on risk appetite across the market, not just one stock. Trade it on its own levels and watch it as a sentiment gauge: strength here keeps the dovish, risk-on read in control, while a rollover in the AI leader with yields near 24-year highs would be an early warning that the rate pressure is reaching the market’s favorite names. |
| AVGO | Broadcom | higher premarket as semis lead the AI-capex theme | Bid premarket with the rest of the AI-chip complex as the semiconductor group leads on the hyperscaler capex story. Broadcom’s networking and custom-silicon exposure makes it a core beneficiary of the AI-infrastructure buildout, and its premarket strength is part of the same leadership read as AMD and Nvidia. Trade it on its own levels and treat the complex as one tell: broad chip strength off the open supports the record-high test; a group that fades while the 10-year climbs is the first sign the rate pressure is pulling the leadership apart. |
Laggards
| NKE | Nike | falling sharply premarket after a fiscal Q1 report and a full-year guidance cut | Down sharply premarket after a fiscal Q1 report that cut full-year guidance — management now sees a high-single-digit revenue decline for fiscal 2027, driven by a 26% revenue drop in Greater China and persistent weakness in the core Sportswear and Jordan brands. It’s a clean, company-specific catalyst and a real read on the consumer and China exposure, not a market-direction signal. Trade it on its own levels; a guidance-cut gap can keep bleeding or stabilize once the forced sellers clear. Isolate it from the broad-tape read. |
| LQDA | Liquidia | falling after a court ruled its drug Yutrepia infringes United Therapeutics patents | Falling premarket after a U.S. District Court ruled that Liquidia’s flagship drug Yutrepia infringes two valid patent claims held by United Therapeutics — a binary legal catalyst that resets the stock’s entire risk profile. This is the kind of court-driven move that can gap and keep moving as the market reprices the product’s path to market. Trade it on its own levels and understand the driver: legal outcomes are discrete events, not fundamentals that drift, so the reaction can be sharp and slow to stabilize. A self-contained story independent of the broad tape. |
| LNG | Cheniere Energy | softer on non-cash derivative losses and Middle East volatility | Softer premarket on investor concern over significant non-cash derivative losses and the heightened volatility tied to escalating Middle East tensions. It’s a nuanced story — non-cash marks don’t change the cash business, but they rattle sentiment, and an LNG exporter is directly exposed to the same Hormuz-driven energy volatility moving the macro tape. Trade it on its own levels and separate the accounting noise from the operating story. A single-name move with its own drivers, worth isolating from the index read today. |
Risks Into the Open
- Primary risk: treating the record as a green light and chasing it. The Nasdaq’s all-time close and a green premarket feel like permission to buy, but a record tells you where price has been, not where it’s going — and this one is sitting on a 10-year near 24-year highs, oil above $100 and a VIX near 15. Chasing strength at resistance is how traders get trapped at the top of a range. Let SPX actually clear and hold 7,800 before you trust the breakout, and let it lose 7,720 and fail to reclaim before you trade the downside. The reaction at the level is the signal, not the headline or the premarket tick.
- The structural risk is the bond market, and it’s the one that matters most. The 10-year near 5.27% is close to a 24-year high, and El-Erian’s warning this weekend was specific: the ‘structural repricing’ in Treasuries is starting to spill into credit and spread risk, with high-yield spreads widening. The belief that surging risk-free rates can stay isolated from stocks is, in his words, ‘now visibly under pressure.’ If a Fed speaker leans hawkish or the 10-year pushes higher, that’s the scenario where the rate pressure finally reaches equities. Keep the yield on your screen as the real driver of every risk asset today.
- The complacency risk is the quiet itself. A VIX near 15 stacked on a 24-year-high yield and $100 oil is conditional calm — the market pricing almost no risk right before it may have to. Add the unresolved Hormuz standoff, where Iran is holding seven conditions and warning of a military response to any U.S. strikes, and you have a tape that can reprice in minutes. It’s not today’s base case, but it’s the headline risk that catches complacent longs flat-footed. Keep crude and the VIX on your screen alongside the 10-year, size appropriately, and don’t confuse a calm tape with a safe one.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Tuesday, October 6, 2026, S&P 500 futures are at 7,773.95 (+0.66%), with the VIX near 15.31. The stock market today opens on a record and a warning at the same time. The Nasdaq Composite closed Monday at 27,477.31, up 1.05%, a fresh all-time high, with the S&P 500 up 0.66% to 7,773.95 and the Dow up 0.18% to 51,267.90 — the rally still running on a soft September jobs report (+29,000) that cut the odds of another Fed hike. This morning futures lean modestly higher: Dow futures up about 0.33%, S&P 500 futures up 0.21%, and Nasdaq-100 futures up roughly 0.25%, with the AI-chip complex (AMD, Nvidia, Broadcom) leading premarket. But look under the record. The 10-year Treasury yield is sitting near 5.27%, close to a 24-year high, and oil is holding firm with Brent above $100 after Iran kept its seven conditions for reopening the Strait of Hormuz — WTI near $89.62. And the VIX is down near 15.31, a calm, almost complacent reading stacked on top of real macro pressure. That is the whole lesson of this tape: a record close tells you where price has been, not where it’s going, and a market this quiet with yields this high is strength built on thin ice. The calendar is light — August trade balance at 8:30 AM ET (a deficit near $102 billion expected) and Fed speakers Williams, Bowman and Logan carry the day, with no CPI and no payrolls this week. So this is a reaction day. SPX 7,800 is the record-high wall, 7,774 is Monday’s close and the axis, and 7,720 is the shelf that keeps a pullback orderly. Don’t buy the headline — let the level hold first. No alignment, no trade.
What is the biggest catalyst for the market today?
The whole tape runs through one contradiction: the Nasdaq just printed a record close (27,477.31, +1.05%) and the S&P 500 sits under 1% from its own record, while the 10-year Treasury yield is near 5.27%, close to a 24-year high. Monday’s push extended a rally built on a weak September jobs report (+29,000 payrolls) that cut the odds of another Fed hike — CME FedWatch has been pricing only about a one-in-five chance of an October move. That dovish read is what’s kept stocks bid. But a yield near 24-year highs is exactly the kind of pressure that historically caps a record market, and this morning the tape is leaning higher anyway: Dow futures +0.33%, S&P 500 +0.21%, Nasdaq-100 +0.25%, led by the AI chips.
What key levels should traders watch today?
SPX 7,800 — the record-high wall. The level just above Monday’s 7,774 close and the resistance the market has to clear to print a fresh S&P record. A push through AND a hold above it on real trade, with breadth from the Dow and small caps rather than tech alone, is the tape saying it can break out even against a 24-year-high yield — a powerful signal, and the door opens higher if it holds. But don’t anticipate the breakout. Make price take and hold 7,800 after the open before you trust the long side; a record tape stalling at resistance with yields elevated is exactly where failed breakouts live. SPX 7,774 — the axis. Monday’s record close and the pivot the whole session turns on. Hold above it and the record-high test stays alive; this is the ‘let it prove itself’ zone where a market weighing a dovish Fed against a 24-year-high yield tends to chop. The real signal is which side SPX leaves this level on once the open settles and the Fed speakers hit the tape. Inside the range is noise; the move that follows is the trade. Patience beats forcing a position while the tape is still deciding which macro force it wants to trade. SPX 7,720 — the shelf that keeps a pullback orderly. The first real floor below the axis, roughly Friday’s close. Hold it and a dip is just a dip inside an uptrend. Lose 7,720 and fail to reclaim it and the rising-yield pressure is finally showing up in price — the market is starting to trade the 5.27% 10-year as the thing that caps the rally, and the tape opens toward the next leg lower. Below 7,720 the job shifts to capital preservation. Mark it, and respect it if it goes.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – October 6, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.