Wednesday, October 28, 2026 · 4:30 PM ET · MTC Market Close
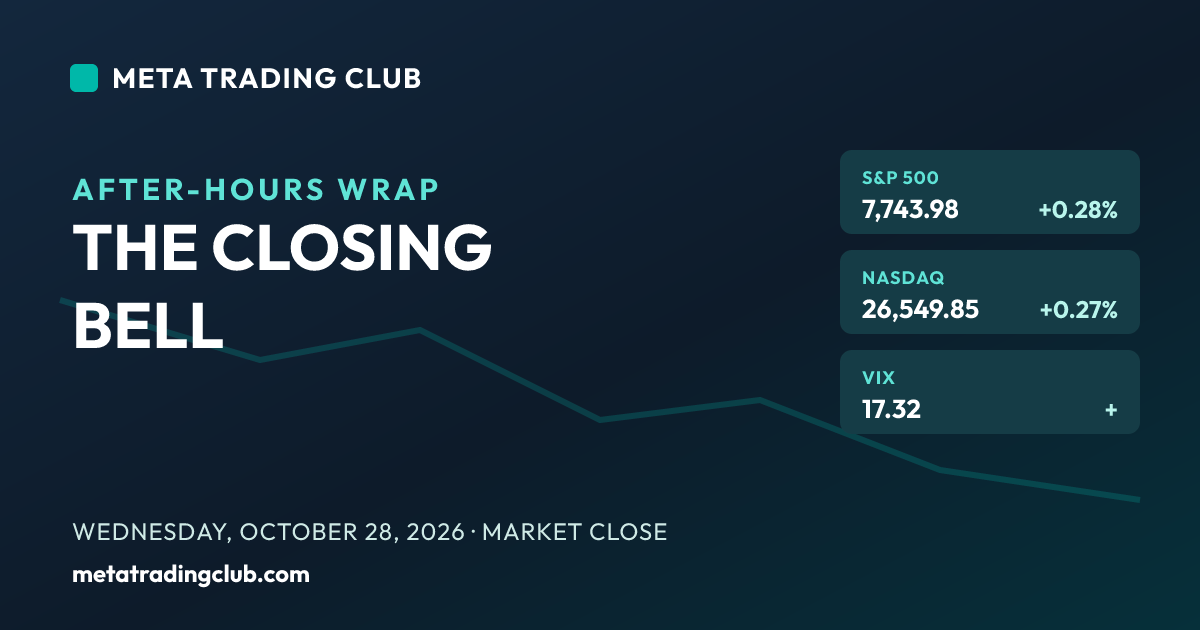
Here’s the stock market today in one line: the index closed green and the tape underneath it did not. The S&P 500 added 0.28% to 7,743.98, the Nasdaq rose 0.27% to 26,549.85, and the Dow gained 0.19% to 52,475.10 after the Federal Reserve held rates steady in a split 10-2 vote, but six of the eleven S&P sectors finished red. That is the whole read of the day: a modest green headline sitting on top of narrow breadth, carried almost entirely by one group. Semiconductors did the heavy lifting, with the PHLX Semiconductor index up about 3.6% and the SOXX ETF up 3.9%, as the AI trade was rejuvenated and data-center names like Vertiv ripped higher on blowout orders. Take the chips out of it and most of the market was heavy, pinned by a 10-year yield still camped near 5% and crude pushing past $101. The Fed hold was expected and did little; the two dissents told you the committee itself is split on the path from here. But the session was never really about the close. It was about what came after it. Alphabet and Microsoft both reported after the bell, and they split the AI-payoff question right down the middle. Microsoft beat, with EPS of $4.27 against $4.09 expected and revenue above estimates on firm cloud growth. Alphabet’s business was arguably stronger, with Google Cloud revenue up a staggering 103% year over year, yet the stock dropped roughly 9% in the after-hours because headline EPS of $2.12 missed on an $8.7 billion loss on equity securities and quarterly capex of $51.4 billion pushed free cash flow negative. That is the tension the whole market is now chewing on: the cloud growth is real, but the bill for it is enormous, and investors just started asking when the payoff shows up. The S&P closed at 7,743.98, with 7,700 the single shelf into Thursday. Hold it through the Alphabet hangover and a packed 8:30 AM data dump of Q3 GDP, PCE, and jobless claims, and this stays a narrow-but-intact rally. Lose it, and the capex question that hit Alphabet tonight becomes the entire tape’s problem, with Amazon’s own capex report landing after Thursday’s close.
The Closing Bell
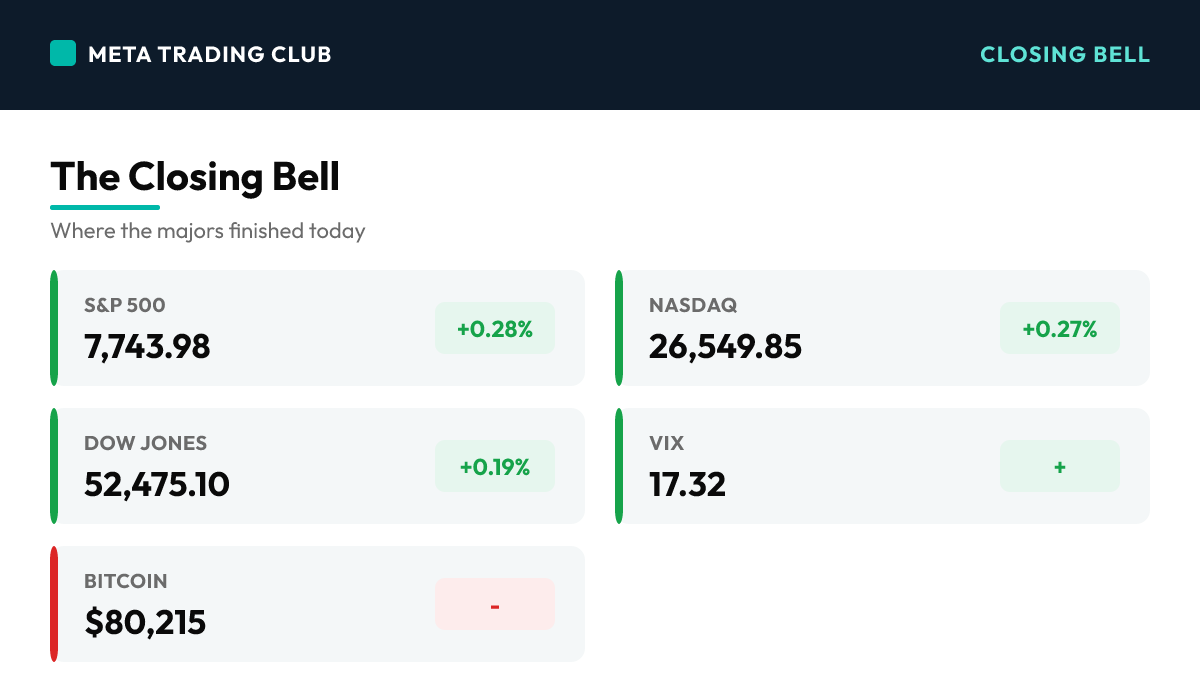
| Instrument | Close | Change | Note |
|---|---|---|---|
| S&P 500 | 7,743.98 | +0.28% | Added about 21 points to close at 7,743.98 after the Fed held rates steady in a 10-2 vote, but the green headline hides a narrow tape: six of the eleven sectors closed red and the gain was carried almost entirely by semiconductors. The index closed sitting just above the 7,700 shelf, and with Alphabet dropping hard after the bell, that makes 7,700 the single line that matters into Thursday. Hold it through the Alphabet hangover and the 8:30 AM data dump and this stays a narrow-but-intact rally; lose it and the AI-capex worry that hit Alphabet tonight goes broad. |
| Nasdaq | 26,549.85 | +0.27% | Rose about 72 points as the semiconductor group did the heavy lifting, with the PHLX Semiconductor index up roughly 3.6% on a rejuvenated AI trade. But the modest 0.27% gain, barely better than the Dow, is the tell: this was not a broad tech melt-up, it was a narrow, chip-led session. The real test for the index comes overnight, with Alphabet off about 9% after hours and Microsoft’s reaction still settling. The after-hours mega-cap tape, not today’s close, is what sets Thursday’s open. |
| Dow Jones | 52,475.10 | +0.19% | Gained about 98 points to a fresh high near 52,475. On a day the semis ripped, the Dow keeping pace with the Nasdaq tells you the leadership was narrow and the rest of the market was heavy. A rising 10-year yield near 5% and crude above $101 kept pressure on the rate-sensitive and cyclical corners, so the blue-chip index leaned on a handful of strong single names rather than broad participation. Solid, but not a sign of deep breadth. |
| Russell 2000 | 2,820.99 | + | Small caps finished firm near 2,820.99, holding up on the Fed hold and the absence of any hawkish surprise. With the committee leaving rates unchanged, the most rate-sensitive corner of the market got a reprieve rather than a fresh headwind. But with the 10-year still camped near 5%, the ceiling over small caps stays heavy, and the group needs yields to actually roll over, not just stop rising, to lead. Level into the close; a steady, not spectacular, session for the Russell. |
| VIX | 17.32 | + | The volatility gauge sat near 17.32, elevated but calm, as the market waited on the Fed and then braced for the after-hours mega-cap reports. A reading in the low 17s on a Fed day with Alphabet and Microsoft on deck says traders are hedged and alert, not fearful. The number to watch is whether the VIX pops overnight on the Alphabet drop and Thursday’s data dump, or whether it drifts back down as the market absorbs the news. For now it is pricing caution, not panic. Level approximate into the settle. |
| 10-Year Yield | 5.02% | + | Held near 5.02% as the Fed’s hold and the two dissents left the bond market without a clear new signal. A 10-year camped at 5% is the quiet weight on this entire market: it caps the rate-sensitive groups, pressures the highest-valued growth names, and is exactly why today’s rally was so narrow. Until this yield actually rolls over, the ceiling stays heavy, and Thursday’s Q3 GDP and PCE prints are the next data that can shove it either way. Level approximate into the settle. |
| WTI Crude | $101.17 | + | Pushed past $101 a barrel, with oil topping $102 intraday on supply tension before settling back. Firm crude above $100 is a direct feed into the inflation story and a tailwind for energy names, but it is also a headwind for the broader market because it keeps upward pressure on the yields that are already capping growth. On a day the Fed held and the semis carried the tape, crude near $101 is one more reason the backdrop stays tight into Thursday’s PCE. Level approximate into the settle. |
| Gold | $4,038.10 | – | Eased to about $4,038 an ounce as the Fed hold and a 10-year near 5% kept real yields firm and capped the metal. Gold holding the $4,000 handle after its huge run is constructive, but the lack of a fresh bid on a Fed day tells you the higher-for-longer rate backdrop is still doing the work of pinning it. A decisive break back above $4,100 would signal renewed safe-haven and inflation-hedge demand; for now it is consolidating. Level approximate into the settle. |
| Bitcoin | $80,215 | – | Held near $80,215, treading water just above the $80,000 line as the above-5% yield backdrop continues to cap the whole risk complex. Bitcoin’s inability to push higher on a Fed-hold day, when you might expect risk appetite to lift, is its own quiet tell that liquidity is still tight. Holding $80,000 is the near-term line; a break below it would say the rate pressure is finally bleeding into crypto in earnest. Level approximate into the settle. |
Today’s Charts
Daily candlestick charts with 20/50/200-day moving averages — the index majors, the day’s biggest mover on each side, and the leading sector ETF.

Charts: Finviz (daily). Levels and overlays update through the next session.
Sector Scoreboard
What Drove The Day
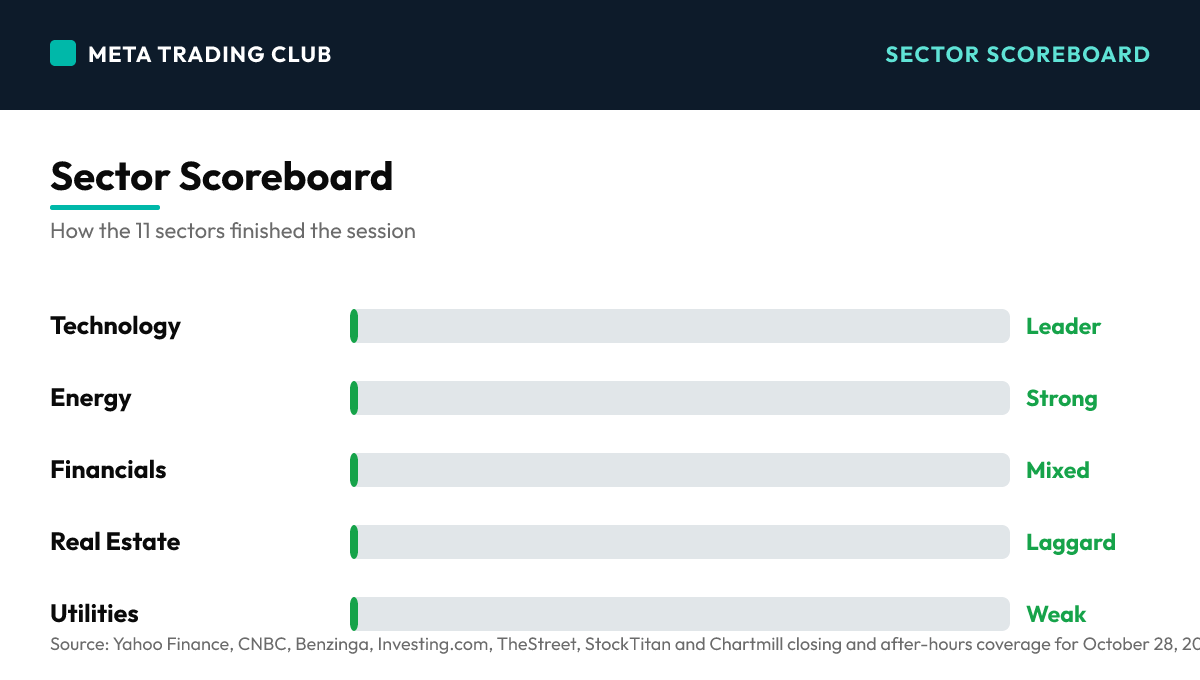
This was a narrow, chip-led green close wrapped around a Fed hold, with the real action saved for after the bell. The Fed left rates unchanged in a 10-2 vote at 2:00 PM ET, an expected decision whose only surprise was the two dissents confirming the committee is split on the path from here. Equities drifted higher into the close: the S&P 500 added 0.28% to 7,743.98, the Nasdaq rose 0.27% to 26,549.85, and the Dow gained 0.19% to 52,475.10. But breadth was poor, with six of eleven sectors finishing red. The entire gain was carried by semiconductors, with the PHLX Semiconductor index up about 3.6% and SOXX up 3.9% as the AI trade was rejuvenated. Vertiv ripped roughly 17% on a blowout quarter and a raised forecast, Pentair gained about 13%, and the data-center and chip complex led. On the other side, Enphase cratered about 17% on soft residential solar demand, Xylem fell about 14%, and F5 dropped more than 20%, a reminder of how punishing the tape is for any earnings miss. A 10-year yield near 5% and crude above $101 kept the rate-sensitive and cyclical groups heavy. Then the bell rang and the night began. Microsoft beat on EPS at $4.27 versus $4.09 and topped revenue estimates on firm cloud growth. Alphabet posted a monster Google Cloud number, up 103% year over year, but the stock fell about 9% after hours as headline EPS of $2.12 missed on an $8.7 billion equity-securities loss and $51.4 billion of quarterly capex pushed free cash flow negative. The S&P closed right above 7,700, turning Thursday’s open, after the Alphabet reaction and an 8:30 AM data dump of Q3 GDP, PCE, and jobless claims, into a clean binary rather than a signal on its own.
MAJOR HEADLINES AND CATALYSTS
Top Market-Moving Stories
- FED HOLDS RATES IN A SPLIT 10-2 VOTE (Day) – The headline event, and an expected one. The Federal Reserve left rates unchanged, but the two dissents are the real signal: the committee itself is divided on whether the next move is a cut or a hold, which keeps the 10-year yield camped near 5% and leaves the market without a clear new direction from policy. A hold with dissents is not a green light, it is a shrug, which is exactly why the day leaned on a single group rather than broad participation.
- THE AI AND SEMICONDUCTOR TRADE WAS REJUVENATED (Day) – The one group that carried the tape. The PHLX Semiconductor index jumped about 3.6% and SOXX rose 3.9% as money poured back into the AI complex, with data-center and power name Vertiv ripping roughly 17% on a blowout quarter and raised guidance. This is the engine of the whole green close, and it is also the exact trade now being stress-tested by the after-hours mega-cap reports. The chips led by day; whether the hyperscalers justify the spend is the question by night.
- ALPHABET FALLS 9% AFTER HOURS ON THE CAPEX BILL (After Hours) – The night’s biggest story. Alphabet posted a monster Google Cloud number, up 103% year over year, yet the stock dropped about 9% after the bell because headline EPS of $2.12 missed on an $8.7 billion loss on equity securities and quarterly capex of $51.4 billion pushed free cash flow negative. This is the AI-payoff question in one report: the growth is undeniably real, but the spending is enormous, and the market just started pricing the gap between the two.
- MICROSOFT BEAT, SPLITTING THE HYPERSCALER VERDICT (After Hours) – The other side of the mega-cap coin. Microsoft reported EPS of $4.27 against $4.09 expected and topped revenue estimates on firm cloud growth, a cleaner result than Alphabet’s. The split matters: on the same night, one hyperscaler was rewarded and the other was punished, which tells you the market is no longer giving the whole AI trade a blanket pass. It is now separating the names that are converting spend into profit from the ones still writing bigger checks.
AFTER-HOURS EARNINGS SPOTLIGHT
Post-Close Reports
- ALPHABET (GOOGL): CLOUD SOARS, STOCK SINKS (After Hours) – Google Cloud revenue rose about 103% year over year on AI infrastructure and TPU demand, an enormous number that should have been a clean win. Instead the stock fell roughly 9% after hours. Headline EPS came in at $2.12, dragged down by an $8.7 billion loss on equity securities, and quarterly capex of $51.4 billion pushed free cash flow negative. The read is blunt: the cloud growth is real, but the capital bill is now big enough that investors want to see the return, not just the revenue.
- MICROSOFT (MSFT): A CLEANER BEAT (After Hours) – Microsoft delivered EPS of $4.27 against $4.09 expected and beat on revenue, with cloud growth holding firm. On a night the market was openly skeptical of AI spending, Microsoft’s result was the steadier of the two mega-caps and showed the spend translating into profit more visibly than Alphabet’s did. The contrast between the two reports is the single most important thing to take into Thursday: the market is now grading hyperscalers on payoff, not just growth.
- THE REAL VERDICT COMES THURSDAY MORNING (After Hours) – With Alphabet down hard and Microsoft steadier, the overnight futures reaction to these two reports will set Thursday’s open, and it lands right on top of an 8:30 AM data dump of Q3 GDP, PCE, and jobless claims. That stacks the biggest earnings of the season against the biggest data of the week in a single session. The market closed on 7,700; where it opens Thursday depends on how it digests both at once.
WHAT IT SETS UP FOR THURSDAY
The Binary Into the Data and the Megacaps
- Q3 GDP, PCE, AND CLAIMS ALL HIT AT 8:30 AM ET (Day) – Thursday is a data dump. The first estimate of Q3 GDP is seen at about 3.0% versus 2.2% prior, September personal income and outlays carry the PCE inflation read the Fed watches most, and weekly jobless claims land near 195K. A strong GDP with cooling PCE is the goldilocks mix that supports the tape; a hot PCE paired with the Alphabet capex worry is the combination that can crack 7,700. This is the data that moves the 10-year, and the 10-year is what has been capping this market.
- AMAZON HEADLINES ANOTHER HUGE EARNINGS NIGHT (Day) – After Thursday’s close, Amazon reports alongside Intel, Starbucks, and Gilead, with Eli Lilly, Mastercard, Merck, and Caterpillar before the open. Amazon matters most because it carries the same capex question that just sank Alphabet, AWS growth against the cost of building it. If the market punished Alphabet for spending tonight, it will be watching Amazon’s capital plans just as closely tomorrow night. The AI-payoff theme does not resolve at today’s close; it runs straight through the rest of the week.
Winners & Losers
Winners
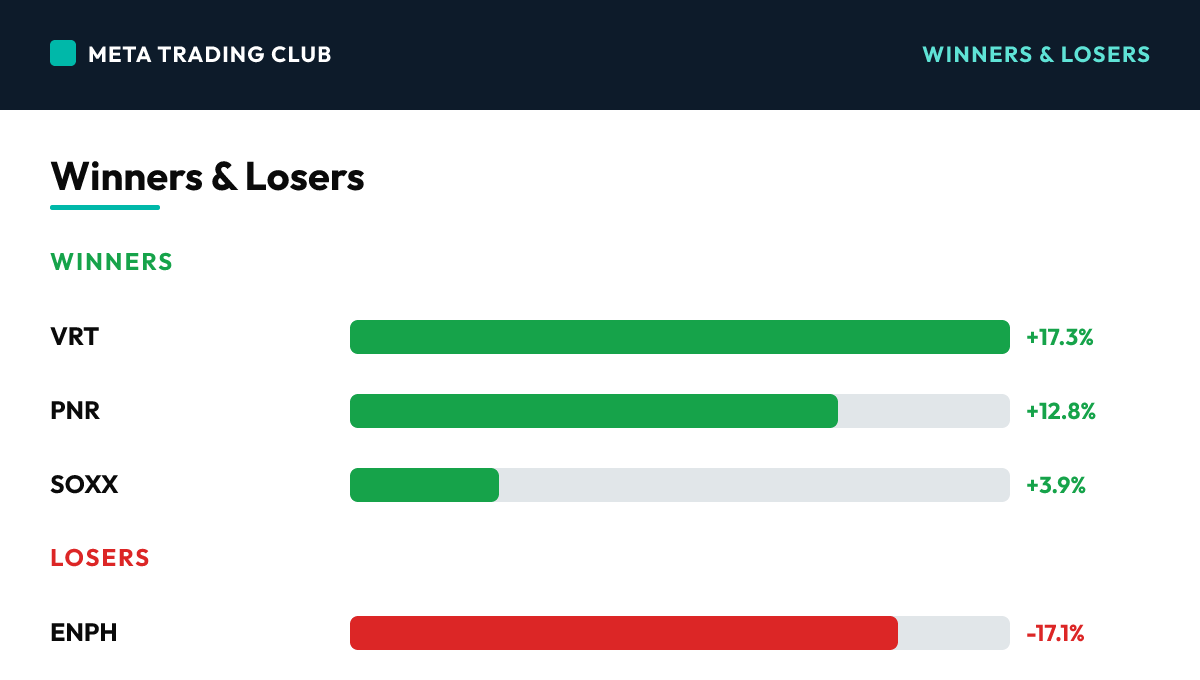
| VRT | +17.3% | Vertiv was the day’s standout gainer, up about 17% after a blowout third quarter: sales rose 61%, orders excluding acquisitions more than doubled, and the company raised its full-year sales forecast by $650 million. As a core data-center power and cooling supplier, Vertiv is a direct beneficiary of the AI infrastructure buildout, and its surge was a major reason the semiconductor and AI complex carried the tape. It is the picks-and-shovels side of the exact capex that is sinking Alphabet after hours, and tonight it paid off. | |
| PNR | +12.8% | Pentair gained about 13% to lead the broader S&P 500 board behind Vertiv, riding strong results in a session where any clean earnings beat was rewarded. On a narrow day where most of the market outside of chips was heavy, Pentair’s jump stood out as one of the few non-AI names with real upside momentum, showing that quality earnings still got paid even as the rate backdrop pressured the rest of the tape. | |
| SOXX | +3.9% | The iShares Semiconductor ETF rose about 3.9%, with the PHLX Semiconductor index up roughly 3.6%, as the AI trade was rejuvenated and money poured back into the chip complex. This group was the single engine of today’s green close. Its strength is the whole bull case and the whole risk at once: it led the tape higher by day, and it is the exact trade now being stress-tested by Alphabet’s after-hours capex miss. Whether it holds these gains Thursday is the key question for 7,700. |
Losers
| ENPH | -17.1% | Enphase Energy was the sharpest S&P 500 decliner, down about 17% after reporting third-quarter revenue of $293.3 million and flagging that US revenue grew less than expected on soft residential solar demand. In a rate-pressured consumer environment, weak end-demand is exactly the miss this unforgiving tape sells hard. On a green-index day, Enphase’s collapse is a vivid reminder that the breadth under the surface was poor and the market is showing no mercy to disappointments. | |
| FFIV | -20.6% | F5 was the single worst performer on the board, plunging more than 20% as its results and outlook disappointed a market that is pricing earnings misses brutally. A drop of this size in a single session underlines the day’s real story: outside the narrow semiconductor leadership, the tape was treacherous, and any company that stumbled got punished without hesitation. F5’s slide is the clearest sign of how thin the market’s patience has become. | |
| XYL | -14.2% | Xylem fell about 14% on a disappointing report, among the weakest names in the S&P 500. Like Enphase and F5, Xylem’s slide shows that the green headline masked a session where earnings misses were sold aggressively. The contrast between the AI winners ripping higher and the earnings losers getting crushed is the whole character of the day: a narrow, two-tier tape where the chips led and everything that stumbled was left behind. |
What It Sets Up For Tomorrow
Levels Into Tomorrow
- S&P 500 7,700 – THE LINE THAT DECIDES IT. Price closed at 7,743.98, sitting just above the 7,700 shelf. This is the single most important level on the page. Hold 7,700 through the overnight Alphabet reaction and Thursday’s 8:30 AM data dump and today’s narrow green close holds together, with the Microsoft beat and the semiconductor strength enough to absorb the Alphabet hangover. Lose 7,700, especially on a hot PCE or a deeper mega-cap slide, and the AI-capex worry that hit Alphabet tonight becomes the whole tape’s problem. The first clean move relative to 7,700 after the 8:30 print is the signal to trade, not the data headline itself.
- S&P 500 7,650 – THE SHELF BELOW. The next real support if 7,700 gives way. A loss of 7,650 would confirm the pullback has legs and open a path toward 7,600 and the larger gap-fill zone beneath it. This is the level that separates a narrow-but-healthy tape from a genuine rotation out of the AI trade. If Alphabet’s drop drags the futures and price slices through both 7,700 and 7,650 without a fight, respect it and stand aside rather than trying to catch it.
- S&P 500 7,780 – THE RECLAIM LEVEL. The first ceiling on any push higher. Today’s rally stalled near the highs, so a decisive move back above 7,780 on a strong GDP and a steadier mega-cap reaction would say the market is shrugging off the Alphabet capex scare and the semiconductor-led bid is broadening out. Until price clears that level with conviction, every rally is suspect and the tape stays narrow. Watch whether buyers can reclaim it on the first attempt Thursday, or whether it caps the move.
Bull case: The bull case is that today was a narrow but genuinely constructive session and the Alphabet drop is a one-name capex story, not a tape story. The Fed held with no hawkish surprise, Microsoft beat cleanly, the semiconductor group ripped on a rejuvenated AI trade, and Thursday’s GDP is seen running near 3.0%, a strong number for a resilient economy. If PCE comes in cool, yields ease back off 5%, and the oversold breadth under the surface starts to catch up, then holding 7,700 confirms the uptrend is intact and the leadership simply broadens from chips into the rest of the market. In that scenario, Alphabet’s spend gets forgiven as the cost of 103% cloud growth, and the dip is bought.
Bear case: The bear case is that the green index masked a weak tape and Alphabet just lit the fuse. Six of eleven sectors closed red, the whole gain rode one group, and the market’s single most important names are being punished for the capex that was supposed to be the story. If Thursday’s PCE runs hot, the 10-year pushes further above 5%, and Alphabet’s after-hours slide drags the futures, then the narrow breadth gives way fast, 7,700 breaks, and the index opens a path toward 7,650 and 7,600. With Amazon carrying the same capex question into Thursday night, the AI-payoff worry would not be a one-day event, it would be the theme of the week, and the record highs would start to look like a ceiling.
Risks Into Tomorrow
- A green index with red breadth is not strength, it is a narrow tape, so read the whole board — Today is a textbook lesson in why the index headline alone will fool you. The S&P closed up 0.28%, the Nasdaq up 0.27%, and the Dow up 0.19%, and a trader glancing only at those numbers would call it a quiet, healthy up day. But six of the eleven S&P sectors closed red, and the entire gain was carried by a single group: semiconductors, up about 3.6% on the index. Strip out the chips and most of the market, real estate, utilities, discretionary, was heavy, pinned by a 10-year yield near 5%. That is not broad strength, it is narrow leadership masking a tired tape. The lesson is to always read the breadth and the sector board, not just the index print. A green close built on one group is far more fragile than a green close with broad participation, because it only takes that one group rolling over to flip the whole tape. And that is exactly the risk tonight: the semiconductor and AI trade that carried the day is the same trade Alphabet just called into question after the bell. When the leadership is this concentrated, the health of the market and the health of one group become the same thing, and that is a setup that demands caution, not confidence, no matter how green the headline looks.
- The market just stopped paying any price for AI growth, and that is the real shift — The single most important thing that happened today was not the Fed hold or the green close, it was Alphabet dropping 9% after hours on a report where Google Cloud grew 103%. Read that again: the business grew its cloud revenue by more than double, and the stock got sold hard. The reason was the capex, $51.4 billion in a single quarter, enough to push free cash flow negative, on top of an $8.7 billion securities loss that hit headline EPS. For two years the market gave the entire AI trade a blanket pass: spend whatever it takes, growth is all that matters. Tonight that changed. Microsoft beat and held up; Alphabet grew faster on cloud and got punished. The difference was not growth, it was the market’s willingness to keep funding the buildout without seeing the payoff. For a trader, this is a regime signal worth respecting. When the leaders of a trade start getting sold on good growth because the cost is too high, the easy phase of that trade is over. It does not mean the trade is dead, Vertiv ripping 17% on real AI orders says the infrastructure demand is genuine, but it does mean the market is now separating the names converting spend into profit from the ones still writing bigger checks. That discrimination, after years of indiscriminate buying, is the story to carry forward, and Amazon’s capex report Thursday night is the next test of it.
- You do not trade the earnings headline, you trade the reaction at your level — The temptation after a night like tonight is to form a hard opinion, Alphabet’s drop means the AI trade is breaking, or Microsoft’s beat means it is fine, and position for it ahead of Thursday. That is a trap. The overnight reaction can gap and reverse, the 8:30 AM data dump of GDP and PCE can override the earnings entirely, and the futures can tell a completely different story by the open than they do tonight. The disciplined approach is the one the MTC framework is built on: identify the level that matters, which today is clearly 7,700, and let price show you its hand after the open. If the S&P absorbs the Alphabet hangover, holds 7,700, and reclaims 7,780 on a cool PCE, that is a confirmed signal the dip is being bought and the narrow tape is broadening. If it slices through 7,700 and 7,650 on a hot number with the mega-caps dragging, that is a confirmed signal to stand aside. Either way, the trade comes from the reaction at the level, not from a prediction about what Alphabet’s capex means for the future. The market will tell you what it wants to do; your job is to wait for it to confirm before you commit a dollar of risk. No alignment yet into Thursday. No trade yet.
Frequently Asked Questions
How did the S&P 500 close today?
On Wednesday, October 28, 2026, the S&P 500 closed at 7,743.98 (+0.28%), with the VIX at 17.32. Here’s the stock market today in one line: the index closed green and the tape underneath it did not.
What drove the market today?
FED HOLDS RATES IN A SPLIT 10-2 VOTE (Day) – The headline event, and an expected one. The Federal Reserve left rates unchanged, but the two dissents are the real signal: the committee itself is divided on whether the next move is a cut or a hold, which keeps the 10-year yield camped near 5% and leaves the market without a clear new direction from policy. A hold with dissents is not a green light, it is a shrug, which is exactly why the day leaned on a single group rather than broad participation.
What levels matter for tomorrow?
S&P 500 7,700 – THE LINE THAT DECIDES IT. Price closed at 7,743.98, sitting just above the 7,700 shelf. This is the single most important level on the page. Hold 7,700 through the overnight Alphabet reaction and Thursday’s 8:30 AM data dump and today’s narrow green close holds together, with the Microsoft beat and the semiconductor strength enough to absorb the Alphabet hangover. Lose 7,700, especially on a hot PCE or a deeper mega-cap slide, and the AI-capex worry that hit Alphabet tonight becomes the whole tape’s problem. The first clean move relative to 7,700 after the 8:30 print is the signal to trade, not the data headline itself. S&P 500 7,650 – THE SHELF BELOW. The next real support if 7,700 gives way. A loss of 7,650 would confirm the pullback has legs and open a path toward 7,600 and the larger gap-fill zone beneath it. This is the level that separates a narrow-but-healthy tape from a genuine rotation out of the AI trade. If Alphabet’s drop drags the futures and price slices through both 7,700 and 7,650 without a fight, respect it and stand aside rather than trying to catch it. S&P 500 7,780 – THE RECLAIM LEVEL. The first ceiling on any push higher. Today’s rally stalled near the highs, so a decisive move back above 7,780 on a strong GDP and a steadier mega-cap reaction would say the market is shrugging off the Alphabet capex scare and the semiconductor-led bid is broadening out. Until price clears that level with conviction, every rally is suspect and the tape stays narrow. Watch whether buyers can reclaim it on the first attempt Thursday, or whether it caps the move.
How does Meta Trading Club prepare for the next session?
We wrap every session and carry the read forward through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
New to this? Start with the free training.
Learn how we read the market before you risk a dollar — our free education library and ebook break down the fundamentals step by step.
Free education → Get the free ebookThe session’s over. The prep isn’t.
This is how MTC members close each day — wrap what happened, mark the levels, and carry one clean read into tomorrow. If you want to build that habit and qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process. It’s application-based — see if it’s a fit.
Explore the MTC Incubator → Apply nowSources: Yahoo Finance, CNBC, Benzinga, Investing.com, TheStreet, StockTitan and Chartmill closing and after-hours coverage for October 28, 2026.. For educational purposes only. Not financial advice.