Wednesday, October 28, 2026 · 8:45 AM ET · MTC Market Intelligence
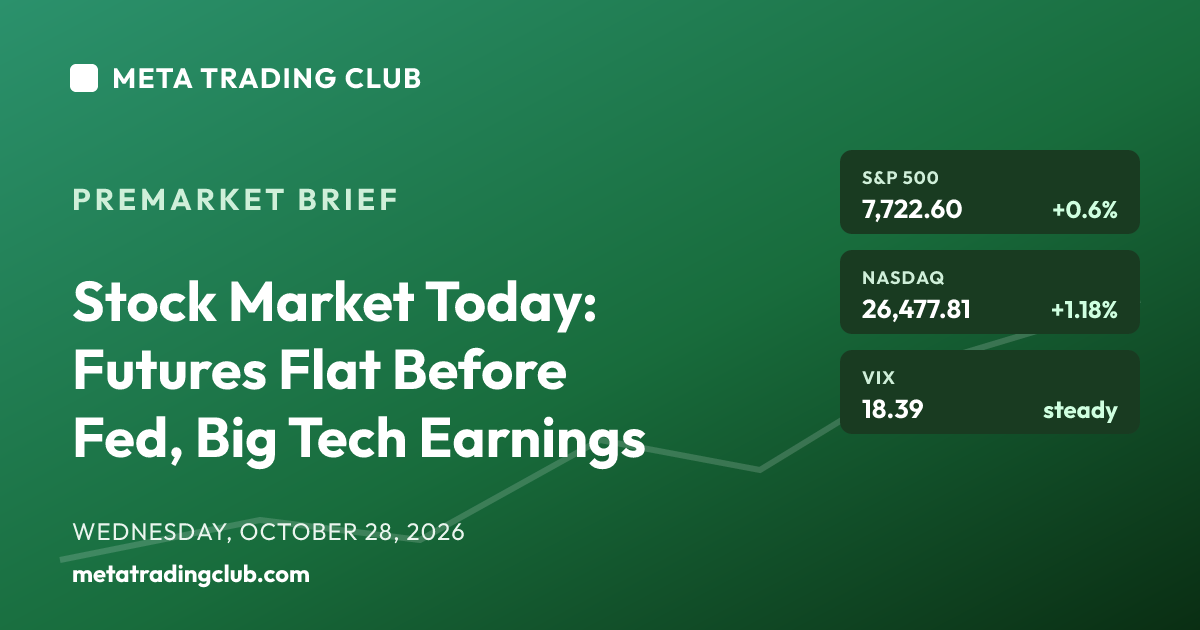
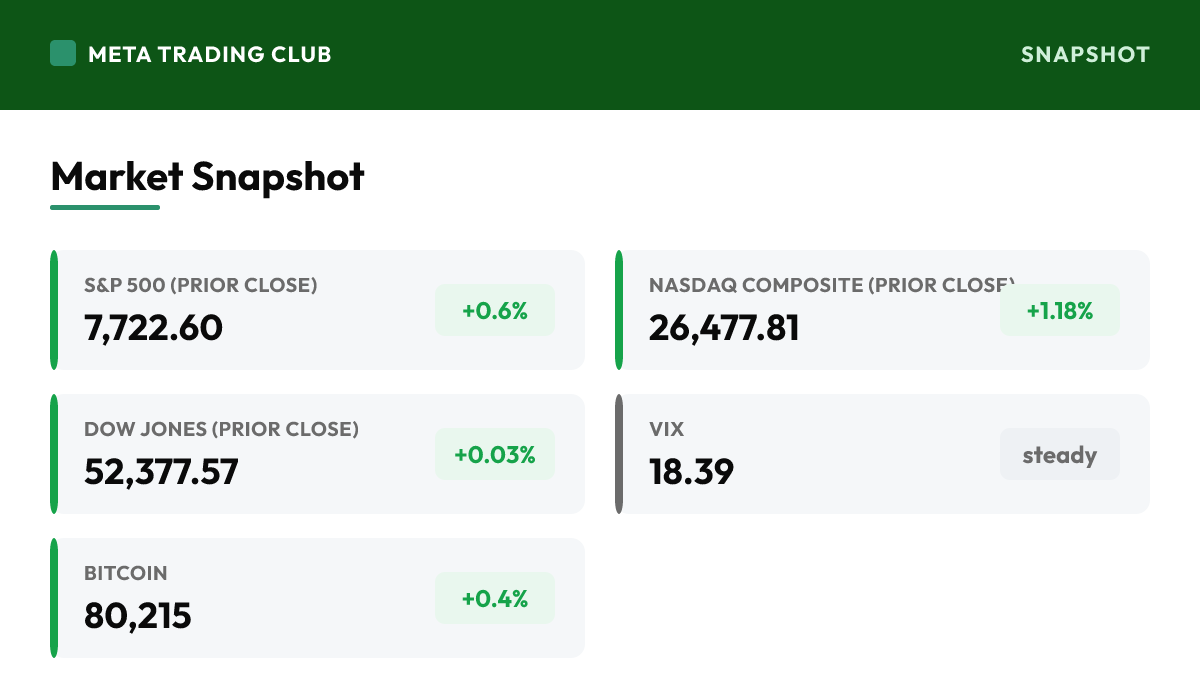
The stock market today is coiled, not calm — and the whole read is that nobody wants to commit size before two catalysts stacked on top of each other this afternoon. Tuesday closed strong: the S&P 500 added 0.6% to 7,722.60, the Nasdaq Composite jumped 1.18% to 26,477.81 on a chip-led rally, and the Dow edged up just 0.03% to 52,377.57. This morning the tape is mixed and flat: Nasdaq-100 futures lead, up about 0.3%, S&P 500 futures are barely green around +0.1%, and Dow futures slip about 0.2%. That split is the tell — tech holds the bid while blue chips cool, and the flatness isn’t peace, it’s the market holding its breath. The reason is the calendar: the Fed decision lands at 2:00 PM ET with Chair Kevin Warsh’s press conference at 2:30, and markets price roughly a 93% chance of a hold at 3.75%-4.00% — but the real question is December, where economists broadly expect another hike. Then, after the close, the two biggest earnings of the quarter hit at once: Microsoft (consensus EPS $4.72 on revenue $90.61B, call 5:30 PM) and Alphabet (consensus EPS $3.02 on revenue $127.69B, call 4:30 PM), with Ford also on the card. Azure and Google Cloud growth plus capex discipline are what the AI trade gets graded on tonight. Crude is the quiet caution — WTI is back near $101, up about 1.6%, keeping a floor under the inflation story while the 10-year sits right at 5.0%. Premarket, earnings winners lead: Vertiv is up about 16% on a strong beat and guide, SK Hynix is up about 7% on record memory results and a massive buyback, while Robinhood drops about 7% on a profit miss and Enphase sinks sharply. Mark SPX 7,770 as the reclaim that puts record highs back in play, 7,700 as the first support the bulls must defend, and 7,635 as the deeper floor. Don’t predict the Fed. Trade the reaction. No alignment, no trade.
Market Snapshot
| Instrument | Level | Change | Note |
|---|---|---|---|
| S&P 500 (prior close) | 7,722.60 | +0.6% | Rose 0.6% Tuesday to 7,722.60, back-to-back winning days that leave the index just under its record zone. This morning S&P 500 futures are barely green, up about 0.1% — not weakness, but hesitation. The level that matters is 7,770: the reclaim that puts record highs back in play. Above the close, 7,700 is the first support the bulls must defend if the Fed or earnings spook the tape. On a day with a 2 PM Fed decision and mega-cap earnings after the close, flat futures are the market refusing to pick a side before it’s forced to. Let the catalyst come to you. |
| Dow Jones (prior close) | 52,377.57 | +0.03% | Barely moved Tuesday, up just 15.99 points to 52,377.57 while tech did the heavy lifting. This morning Dow futures slip about 0.2%, and that is the split of the day: the bid is in tech, not blue chips, ahead of the Fed and the Microsoft-and-Alphabet prints that drive the Nasdaq. A Dow that cools while the Nasdaq holds green tells you where the risk appetite is concentrated — and where it isn’t. Watch whether blue chips firm up or keep drifting as the 2 PM decision approaches. |
| Nasdaq Composite (prior close) | 26,477.81 | +1.18% | The leader Tuesday, up 1.18% to 26,477.81 on a chip-led rally as memory names ripped on SK Hynix’s record results. This morning Nasdaq-100 futures lead again, up about 0.3%, but the group is walking into its own verdict: Microsoft and Alphabet report after the close tonight, and that’s when the AI trade actually gets graded on cloud growth and capex. The chips can hold the bid into the open, but futures don’t settle the question — the numbers do. This is the index with the most at stake today. |
| Russell 2000 (prior close) | — | N/A | Small caps are the risk-appetite gauge into the Fed. With the 10-year pinned right at 5.0% and markets pricing a hold today but a hike in December, the Russell’s heavy borrowing-cost burden stays front and center. Watch whether it can hold up as the decision approaches: a Russell that firms says the market is comfortable rates have mostly topped, while a Russell that lags says the December-hike risk is weighing on the most rate-sensitive corner of the tape. Treat it as the breadth tell underneath the mega-cap headlines. |
| VIX | 18.39 | steady | Sitting near 18.4, elevated but not panicked, as the tape waits on the Fed and the night’s earnings. That’s a holding-pattern read: the market isn’t calm, it’s braced. Expect the VIX to stay bid into the 2 PM decision and the after-close prints, then move hard on the reaction — a push back above 20 if Warsh sounds hawkish on December or if Microsoft or Alphabet disappoint, or a slide toward 16 if the Fed stays measured and the earnings cooperate. A high-teens VIX on a double-catalyst day says respect the whipsaw risk around 2 PM and the close. |
| WTI Crude | 101.54 | +1.6% | Back near $101, up about 1.6% and climbing, and that’s the quiet caution underneath an otherwise steady tape. Oil pushing toward triple digits keeps a floor under the inflation story at exactly the wrong moment — right as the Fed debates whether December needs another hike. Higher crude is a headwind for the rate picture and a reason futures aren’t leaning harder into risk this morning. It’s not the headline driver today, but it’s the cross-current that keeps the bid cautious. Watch whether crude holds above $100 or fades into the decision. |
| 10-Yr Treasury | 5.02% | steady | Holding right at 5.0%, a level that keeps the pressure on the most rate-sensitive growth and small-cap names into the Fed. With a hold priced for today but a December hike widely expected, the 10-year is the referee on how the tape reads Warsh’s tone at 2:30. A yield that stays anchored near 5.0% says the bond market already believes in more tightening; a move higher on hawkish commentary tightens the screws on the AI complex just as earnings land. Watch the 10-year as the real-time read on the December debate. |
| Bitcoin | 80,215 | +0.4% | Trading near $80,215, up about 0.4% and steady ahead of the open as risk appetite waits on the Fed. Crypto’s tone tracks the broader hesitation — firm but uncommitted into a day with two binary catalysts. A reclaim and hold back above $82K would say risk is leaning in ahead of the earnings; a slide under $80K would flag that the caution in oil and yields is bleeding into risk assets. Treat it as a steadying, wait-and-see read rather than a signal in either direction until the 2 PM decision clears. |
Charts to Watch
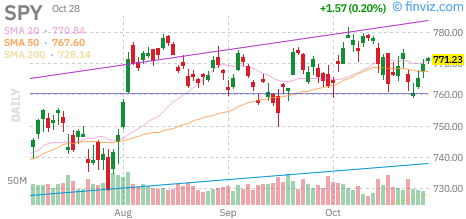
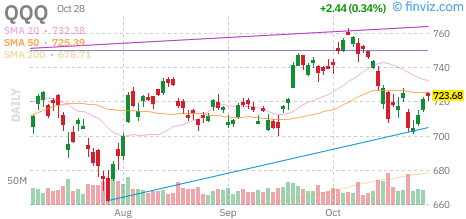
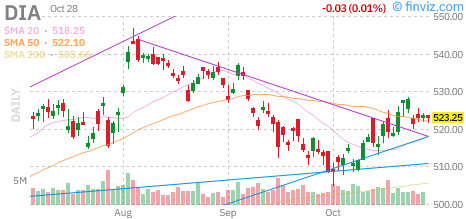
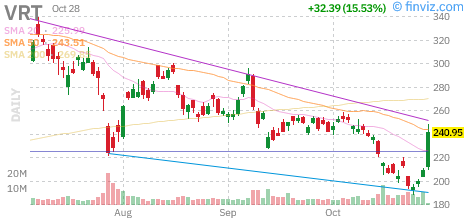
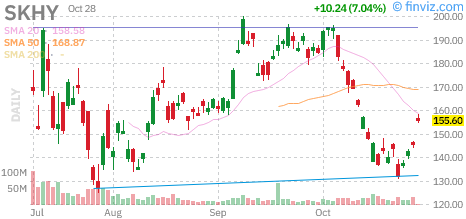
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
Overnight & Global Markets
Tuesday closed firm: the S&P 500 rose 0.6% to 7,722.60, the Nasdaq Composite jumped 1.18% to 26,477.81 on a chip-led rally, and the Dow edged up just 0.03% to 52,377.57, a second straight winning day that left the indexes just under record territory. This morning the tape is flat and split: Nasdaq-100 futures lead, up about 0.3%, S&P 500 futures are barely green near +0.1%, and Dow futures slip about 0.2%. The flatness is the story — the market is refusing to commit ahead of two catalysts stacked this afternoon. The Fed decides at 2:00 PM ET, with Chair Kevin Warsh’s press conference at 2:30; markets price roughly a 93% chance of a hold at 3.75%-4.00%, so the real focus is December, where economists broadly expect another hike. Then, after the close, the quarter’s two biggest prints land together: Microsoft (consensus EPS $4.72 on $90.61B revenue, call 5:30 PM) and Alphabet (consensus EPS $3.02 on $127.69B revenue, call 4:30 PM), with Ford also reporting. Azure and Google Cloud growth plus capex discipline are what grade the AI trade tonight. Crude is the quiet caution — WTI is back near $101, up about 1.6%, keeping a floor under inflation while the 10-year holds at 5.0%. Premarket, earnings winners lead: Vertiv is up about 16% on a strong beat and guide and SK Hynix is up about 7% on record memory results and a $75B buyback, while Robinhood drops about 7% on a profit miss and Enphase sinks sharply. Mark SPX 7,770 as the reclaim that puts records in play, 7,700 as the first support to defend, and 7,635 as the deeper floor. Don’t predict the Fed. Trade the reaction. No alignment, no trade.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The Fed decision at 2:00 PM ET is the first of two catalysts stacked today, but the decision itself is nearly a non-event — markets price roughly a 93% chance of a hold at 3.75%-4.00%. The real story is December. A Reuters survey found nearly every economist expects no change today, while essentially all of them forecast another hike before year-end. That makes Chair Kevin Warsh’s 2:30 press conference the actual market mover: the tape will trade his tone on whether December tightening is locked in, not the hold everyone already knows is coming. Don’t trade the headline at 2:00 — trade the reaction to the message at 2:30.
- After the close, the quarter’s two biggest earnings land at once. Alphabet reports with consensus EPS of $3.02 on $127.69B revenue (call at 4:30 PM), and Microsoft follows with consensus EPS of $4.72 on $90.61B revenue (call at 5:30 PM); Ford also reports. This is where the AI trade gets graded: Google Cloud growth and search resilience for Alphabet, Azure growth and Copilot monetization for Microsoft, and capex discipline for both. The chip rally that led Tuesday is effectively a bet on what these two say tonight. The setup is loaded into the close — size accordingly and let the numbers settle it.
- Oil is the quiet cross-current keeping the tape honest. WTI is back near $101, up about 1.6% and climbing, which puts a floor under the inflation story at exactly the moment the Fed is weighing December. Higher crude is a headwind for the rate picture and part of why futures aren’t leaning harder into risk this morning. Meanwhile earnings reactions are already sorting winners from losers premarket: Vertiv up about 16% on a strong beat and guide, SK Hynix up about 7% on record memory results and a $75B buyback, against Robinhood down about 7% on a profit miss and Enphase sinking sharply. Price action is rewarding real numbers and punishing misses — that’s a healthy tape, but a selective one.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,770 — the reclaim that puts records back in play. This is the resistance just above Tuesday’s 7,722.60 close; take it and hold it and the path opens toward the 7,782-7,812 record-close zone and the 7,844 intraday record from October 6. But this is a day to let the level prove itself, not chase it — with the Fed at 2 PM and mega-cap earnings after the close, a push into 7,770 before the catalyst is exactly where chasers get trapped. Make the market earn the reclaim on real volume after the decision clears. Don’t predict the breakout into a binary afternoon.
- SPX 7,700 — the first support the bulls must defend. This is the round level just under Tuesday’s close and the line that decides whether the back-to-back rally stays intact. Hold above 7,700 and the structure is constructive heading into the Fed; lose it and the tape is telling you the bid is thinning ahead of the catalysts. On a day this event-driven, 7,700 is the pivot that separates a healthy pause from a nervous one. Watch which side of it SPX settles on once the morning surge cools and the 2 PM clock gets closer.
- SPX 7,635 — the deeper floor. This is the must-hold support below the pivot, lining up with the 7,635 Fibonacci area and the October 16 low near 7,632. It’s the level that matters if Warsh sounds hawkish on December or if Microsoft or Alphabet disappoint after the close and the tape unwinds the record-chase. Lose 7,635 and the constructive structure is in question — that’s where dip-buyers have to step up to keep the uptrend alive. Mark it, respect it, and let price confirm. Don’t guess the bottom on a catalyst-driven flush; let the level do the talking.
Premarket Movers
Gainers
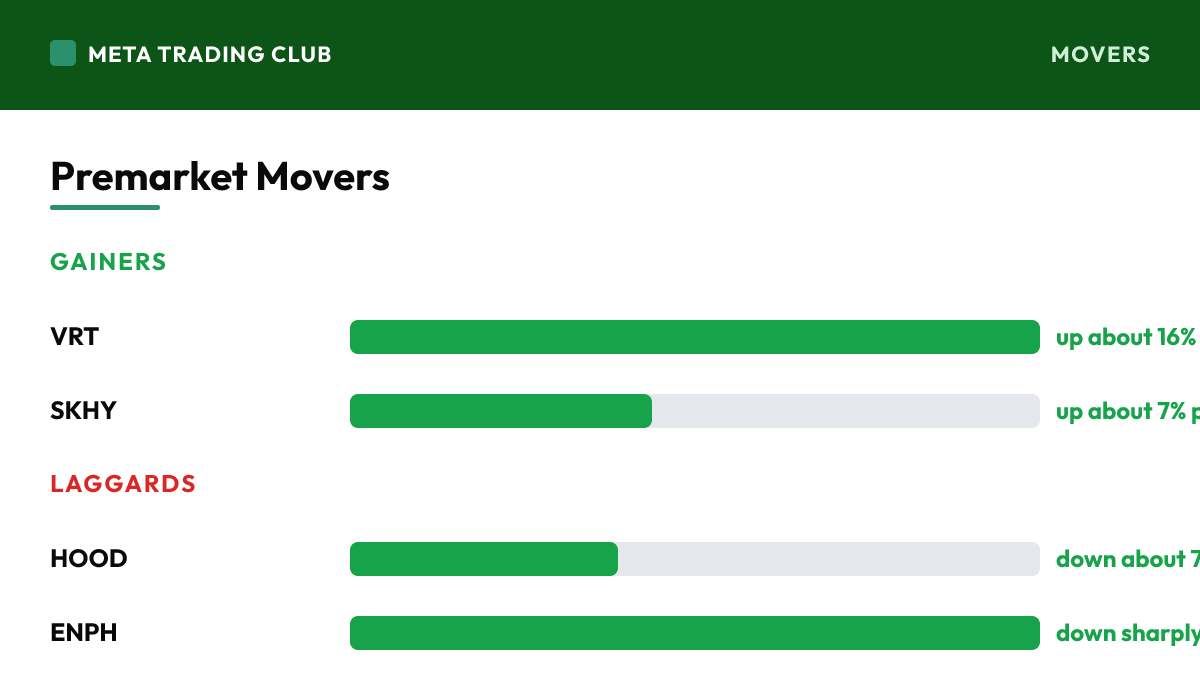
| VRT | Vertiv | up about 16% premarket on a Q3 beat and stronger-than-expected guidance | Leading the premarket on a clean beat-and-raise — adjusted earnings of $2.21 per share and a guide above expectations. This is a catalyst-driven move on real numbers, and as a data-center infrastructure name it’s a direct proxy for AI buildout demand. Trade it on its own levels: a 16% earnings gap can give back fast if the market fades the move into a Fed-decision afternoon, so let the stock prove the pop holds rather than chasing the headline into the open. It’s also a tone-setter for the AI-infrastructure trade heading into tonight’s hyperscaler capex numbers. |
| SKHY | SK Hynix | up about 7% premarket on record results and a $75B buyback | Up about 7% after record quarterly results on AI-memory demand and a massive $75B shareholder-return plan. It’s the name that lit the memory complex and helped drive Tuesday’s chip rally, so read it as both a single-stock story and a tell on the group. Trade the reaction and the level, not the headline — a record quarter is already in the price after a 7% gap, and the real question for the chip trade is whether tonight’s Microsoft and Alphabet capex confirms the demand. If the chip bid holds into the open, it adds credibility ahead of the prints. |
Laggards
| HOOD | Robinhood | down about 7% premarket on a quarterly profit miss | Down about 7% after net income fell 14% to $476 million, missing expectations. In a tape that’s rewarding beats and punishing misses, Robinhood is the clean example of the second — and a read on whether the retail trading tailwind is cooling. Trade it on its own levels and treat the reaction as a gauge of how unforgiving the market is heading into the Fed and the mega-cap prints. A name that can’t find a bid even on a green tech morning is telling you the market is being selective, not euphoric. |
| ENPH | Enphase Energy | down sharply premarket, off roughly 18% on its results | Sinking hard premarket, down roughly 18% on its quarterly report — the biggest decliner among the liquid names this morning. Solar has been a rough group, and a drop this size says guidance or demand disappointed badly. Trade it on its own levels and don’t try to catch the falling knife on a catalyst-heavy day; a gap-down this large can keep bleeding or snap back violently, and neither is a clean setup. Treat it as a single-stock blowup, not a sector-wide signal, and let the dust settle before touching it. |
Risks Into the Open
- Primary risk today: trading before the catalyst instead of after it. With the Fed at 2 PM and the two biggest earnings of the quarter after the close, the temptation is to pre-position for the move. But both are binary events, and positioning ahead of them is gambling, not trading. The decision at 2:00 is nearly priced — the real move comes from Warsh’s tone at 2:30 and the Microsoft-Alphabet prints after 4 PM. The discipline is to let SPX hold 7,700 and reclaim 7,770 on real volume after the catalysts clear. Flat futures this morning are the market modeling exactly this restraint. Respect it.
- The structural risk is the December message, not today’s hold. Markets expect a hold at 3.75%-4.00%, so the hold itself changes nothing. What moves the tape is whether Warsh signals December tightening is locked in — with oil back near $100 and the 10-year at 5.0%, the inflation backdrop gives the Fed room to stay hawkish. The trap is reading a hold as dovish and chasing risk, only to get caught offside if the presser leans the other way. Trade the reaction to the message, not the headline of the decision. The dot plot and the tone are the event, not the number.
- The company-specific risk is treating tonight’s earnings as a sure thing. The chip rally priced in strong hyperscaler demand, but Microsoft and Alphabet still have to deliver on Azure, Google Cloud, and — critically — capex discipline. A beat with bloated spending guidance can sell off just as fast as a miss. Don’t carry oversized AI exposure into the close assuming the prints confirm the rally; the whole point of a confirmation-first approach is that you let the numbers verify the thesis before you commit. Size for the fact that both could surprise in either direction. Confirmation over conviction, especially into a double catalyst.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Wednesday, October 28, 2026, S&P 500 futures are at 7,722.60 (+0.6%), with the VIX near 18.39. The stock market today is coiled, not calm — and the whole read is that nobody wants to commit size before two catalysts stacked on top of each other this afternoon. Tuesday closed strong: the S&P 500 added 0.6% to 7,722.60, the Nasdaq Composite jumped 1.18% to 26,477.81 on a chip-led rally, and the Dow edged up just 0.03% to 52,377.57. This morning the tape is mixed and flat: Nasdaq-100 futures lead, up about 0.3%, S&P 500 futures are barely green around +0.1%, and Dow futures slip about 0.2%. That split is the tell — tech holds the bid while blue chips cool, and the flatness isn’t peace, it’s the market holding its breath. The reason is the calendar: the Fed decision lands at 2:00 PM ET with Chair Kevin Warsh’s press conference at 2:30, and markets price roughly a 93% chance of a hold at 3.75%-4.00% — but the real question is December, where economists broadly expect another hike. Then, after the close, the two biggest earnings of the quarter hit at once: Microsoft (consensus EPS $4.72 on revenue $90.61B, call 5:30 PM) and Alphabet (consensus EPS $3.02 on revenue $127.69B, call 4:30 PM), with Ford also on the card. Azure and Google Cloud growth plus capex discipline are what the AI trade gets graded on tonight. Crude is the quiet caution — WTI is back near $101, up about 1.6%, keeping a floor under the inflation story while the 10-year sits right at 5.0%. Premarket, earnings winners lead: Vertiv is up about 16% on a strong beat and guide, SK Hynix is up about 7% on record memory results and a massive buyback, while Robinhood drops about 7% on a profit miss and Enphase sinks sharply. Mark SPX 7,770 as the reclaim that puts record highs back in play, 7,700 as the first support the bulls must defend, and 7,635 as the deeper floor. Don’t predict the Fed. Trade the reaction. No alignment, no trade.
What is the biggest catalyst for the market today?
The Fed decision at 2:00 PM ET is the first of two catalysts stacked today, but the decision itself is nearly a non-event — markets price roughly a 93% chance of a hold at 3.75%-4.00%. The real story is December. A Reuters survey found nearly every economist expects no change today, while essentially all of them forecast another hike before year-end. That makes Chair Kevin Warsh’s 2:30 press conference the actual market mover: the tape will trade his tone on whether December tightening is locked in, not the hold everyone already knows is coming. Don’t trade the headline at 2:00 — trade the reaction to the message at 2:30.
What key levels should traders watch today?
SPX 7,770 — the reclaim that puts records back in play. This is the resistance just above Tuesday’s 7,722.60 close; take it and hold it and the path opens toward the 7,782-7,812 record-close zone and the 7,844 intraday record from October 6. But this is a day to let the level prove itself, not chase it — with the Fed at 2 PM and mega-cap earnings after the close, a push into 7,770 before the catalyst is exactly where chasers get trapped. Make the market earn the reclaim on real volume after the decision clears. Don’t predict the breakout into a binary afternoon. SPX 7,700 — the first support the bulls must defend. This is the round level just under Tuesday’s close and the line that decides whether the back-to-back rally stays intact. Hold above 7,700 and the structure is constructive heading into the Fed; lose it and the tape is telling you the bid is thinning ahead of the catalysts. On a day this event-driven, 7,700 is the pivot that separates a healthy pause from a nervous one. Watch which side of it SPX settles on once the morning surge cools and the 2 PM clock gets closer. SPX 7,635 — the deeper floor. This is the must-hold support below the pivot, lining up with the 7,635 Fibonacci area and the October 16 low near 7,632. It’s the level that matters if Warsh sounds hawkish on December or if Microsoft or Alphabet disappoint after the close and the tape unwinds the record-chase. Lose 7,635 and the constructive structure is in question — that’s where dip-buyers have to step up to keep the uptrend alive. Mark it, respect it, and let price confirm. Don’t guess the bottom on a catalyst-driven flush; let the level do the talking.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – October 28, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.