Wednesday, October 14, 2026 · 4:30 PM ET · MTC Market Close
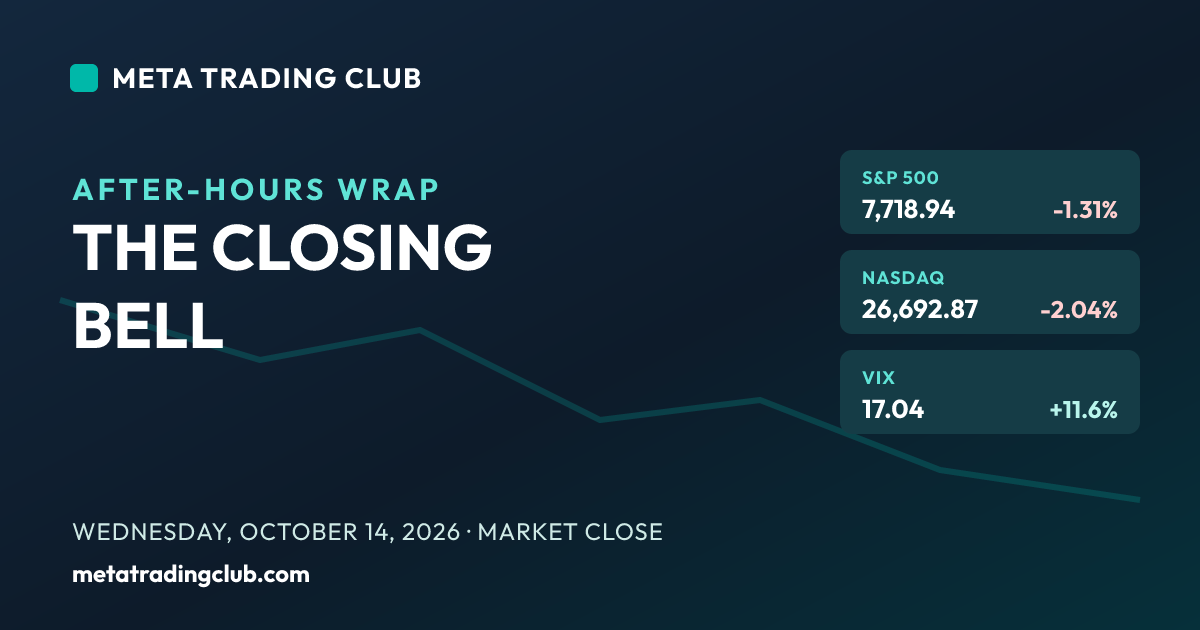
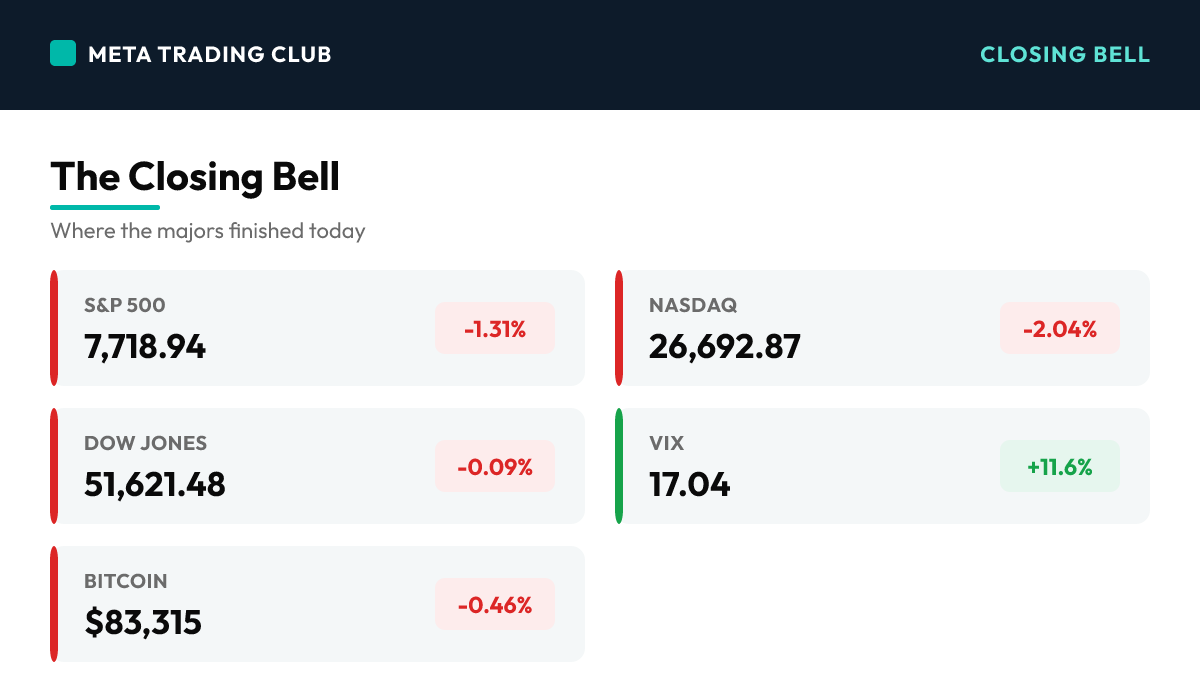
Hot inflation finally bit the stock market today. September CPI came in at 0.6% month over month and 3.7% year over year, with core at 0.3% and 2.6%, all hotter than the Street expected, and the market did exactly what you would expect when the Fed’s rate-cut path gets questioned: it sold the stuff priced for perfection. The S&P 500 fell 1.31% to close at 7,718.94, the Nasdaq dropped 2.04% to 26,692.87, and the Russell 2000 took the brunt with a 2.12% slide to 2,725.10 as higher-for-longer slammed the most rate-sensitive names. The damage was concentrated, not broad. The AI and semiconductor trade led the way down, with AMD off 5.15%, Intel down about 4%, and Micron off roughly 3.6%, dragging Technology down 2.73% to the bottom of the sector board. But here is the tell that matters: the Dow closed down just 0.09%, basically flat, because money did not run for the exits, it rotated. Health Care rose 2.09% behind a 3.9% pop in UnitedHealth on an earnings beat and guidance hike, with Amgen up 3.29%, and Consumer Staples and Energy both finished green. That is a defensive rotation, not a liquidation. The VIX popped to 17.04 but never spiked into panic, and gold actually fell 1.24% to $4,126, so there was no classic flight to safety either. The S&P closed at 7,718.94, right on top of the 7,700 shelf. That makes 7,700 the single line into Thursday, when PPI, retail sales, and jobless claims all hit at 8:30 AM ET. Hold 7,700 and this was a one-day repricing in the hottest corner of the market. Lose it on a hot PPI and the AI weakness becomes the whole tape’s problem.
The Closing Bell
| Instrument | Close | Change | Note |
|---|---|---|---|
| S&P 500 | 7,718.94 | -1.31% | Fell about 102 points to close at 7,718.94, its worst session in weeks, as a hotter-than-expected September CPI revived bets that the Fed may have to hike again rather than cut. The selling was heavy but orderly, concentrated in the AI and semiconductor names that had led the record run, while defensive sectors actually finished green. The index closed sitting right on the 7,700 shelf, and that makes 7,700 the single line that matters into Thursday’s PPI: hold it and this was a one-day repricing in the hottest corner of the market, lose it and the quiet AI weakness becomes everyone’s problem. |
| Nasdaq | 26,692.87 | -2.04% | The clear laggard, down about 554 points as the semiconductor group was gutted. AMD fell 5.15%, Intel dropped roughly 4%, and Micron slid about 3.6%, and with chips carrying the most weight in the index, a 2% down day was the mechanical result. This is the exact corner that led the market to records for months, so a sharp, broad-based sell in AI and memory on a hot inflation print is the honest signal of where the air comes out first when the rate story turns. |
| Dow Jones | 51,621.48 | -0.09% | Essentially flat, down only about 49 points, and that is the most important number on the board. While the Nasdaq fell 2%, the Dow barely moved because a 3.9% jump in UnitedHealth on an earnings beat and a strong healthcare tape offset the tech weakness. When one index drops 2% and another closes flat on the same day, it tells you this was a rotation out of growth and into defense, not a wholesale exit from stocks. That distinction is the whole read into Thursday. |
| Russell 2000 | 2,725.10 | -2.12% | Small caps took the brunt, off about 59 points to 2,725.10, because the most rate-sensitive corner of the market has the most to lose when a hot CPI pushes rate-hike odds back up and the 10-year holds above 5%. A 2% drop in small caps on an inflation surprise is textbook: higher-for-longer is a direct headwind for the companies that need cheap money most. When the Russell leads the tape lower, it confirms the day was about rates, not earnings. |
| VIX | 17.04 | +11.6% | The volatility gauge jumped about 11.6% to 17.04, its sharpest pop in weeks, as traders scrambled to hedge a genuinely hot inflation print. But notice the level: 17 is elevated, not panic. A reading in the high teens on a 2% Nasdaq down day says the market is alert and repricing, not breaking. If this were the start of a real unwind, the VIX would be in the 20s. The jump confirms the stress is real, but the modest ceiling on it is the quiet tell that this is a repricing, not yet a liquidation. |
| 10-Year Yield | 5.22% | + | Pushed higher toward 5.22% as the hot CPI forced the bond market to price in a higher-for-longer Fed, and that move is the engine behind the entire equity selloff. A rising 10-year above 5% is a direct weight on long-duration growth and the richly valued AI complex, which is exactly why semiconductors and small caps took the most damage. Until this yield rolls over, the ceiling over this market stays heavy, and Thursday’s PPI is the next print that can shove it even higher. |
| WTI Crude | $95.66 | +1.55% | Rose about 1.55% to $95.66 a barrel, and firm crude is the last thing this market wanted on a hot CPI day. Rising oil feeds directly into the inflation story the market is suddenly worried about again, adding to the higher-for-longer pressure on yields. Energy stocks managed a small green finish on the firmer oil, but for the broader tape, crude pushing toward $96 is a reason the inflation worry has teeth heading into Thursday. Level approximate into the settle. |
| Gold | $4,126.50 | -1.24% | Slipped about 1.24% to $4,126 an ounce, and that is a notable tell. On a day stocks sold off on inflation fear, the classic inflation hedge did not catch a bid, it fell, pressured by the jump in real yields as the 10-year climbed. When gold drops alongside stocks, it says the move was driven by higher rates rather than a flight to safety, which lines up with the whole read of the session: this was a rate-driven repricing, not a panic. Level approximate into the settle. |
| Bitcoin | $83,315 | -0.46% | Held near $83,315, down less than half a percent, and holding up better than stocks on a risk-off day is its own small story. The above-5% yield backdrop has kept crypto capped for weeks, but on a session where equities dropped hard, a nearly flat Bitcoin shows the selling was targeted at expensive equity risk rather than the whole risk complex. It is treading water, which on a day like today is relative strength. Level approximate into the settle. |
Today’s Charts
Daily candlestick charts with 20/50/200-day moving averages — the index majors, the day’s biggest mover on each side, and the leading sector ETF.

Charts: Finviz (daily). Levels and overlays update through the next session.
Sector Scoreboard
What Drove The Day
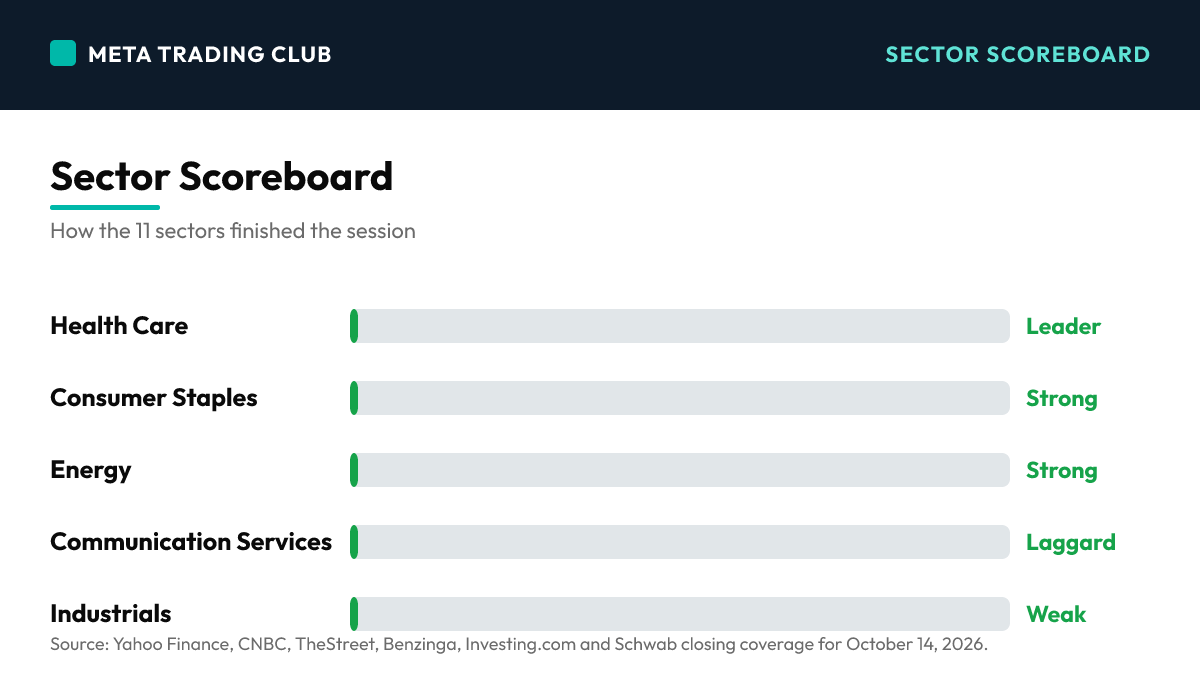
This was a rate-driven repricing, concentrated in the most expensive corner of the market. The trigger was September CPI at 8:30 AM ET: headline inflation rose 0.6% on the month and 3.7% on the year, with core at 0.3% and 2.6%, all hotter than expected, and the number put another Fed rate hike back on the table. The reaction was immediate and selective. The S&P 500 fell 1.31% to 7,718.94, the Nasdaq dropped 2.04% to 26,692.87, and the Russell 2000 slid 2.12% to 2,725.10, but the Dow closed essentially flat at 51,621.48, down just 0.09%. That split is the entire story. Technology fell 2.73% to the bottom of the board as the AI and semiconductor trade was gutted, with AMD off 5.15%, Intel down about 4%, and Micron off roughly 3.6%. On the other side, money rotated into defense: Health Care rose 2.09% on a 3.9% jump in UnitedHealth and a 3.29% gain in Amgen, while Consumer Staples and Energy also finished green. The 10-year yield pushed toward 5.22%, the VIX jumped 11.6% to 17.04, and gold fell 1.24% as higher real yields did the damage. The S&P closed right on the 7,700 shelf, turning Thursday’s data dump, PPI, retail sales, and jobless claims all at 8:30 AM, into a clean binary rather than a signal on its own.
MAJOR HEADLINES AND CATALYSTS
Top Market-Moving Stories
- HOT SEPTEMBER CPI REVIVES RATE-HIKE FEAR (Day) – The trigger for the whole session. Headline CPI rose 0.6% on the month and 3.7% on the year, with core at 0.3% and 2.6%, all hotter than the 0.2% and 2.5% the Street expected. The number put another Fed rate hike back on the table, pushed the 10-year yield toward 5.22%, and sent the most rate-sensitive, highest-valued corners of the market lower. This was the catalyst that turned weeks of quiet into a 2% Nasdaq down day.
- THE AI AND SEMICONDUCTOR TRADE BREAKS DOWN (Day) – The group that led the record run took the most damage. AMD fell 5.15%, Intel dropped about 4%, and Micron slid roughly 3.6%, dragging Technology down 2.73% to the bottom of the sector board. A rising 10-year is a direct weight on long-duration growth, and the AI complex is the longest-duration trade in the market. The selloff was concentrated here, which is both the bad news and, for anyone watching 7,700, the key thing to track into Thursday.
- THE DOW HELD FLAT ON A DEFENSIVE ROTATION (Day) – The quiet story under the headline red. While the Nasdaq fell 2%, the Dow closed down just 0.09% because money rotated into defense rather than leaving. UnitedHealth jumped 3.9% on an earnings beat and guidance hike, Amgen rose 3.29%, and Health Care, Consumer Staples, and Energy all finished green. A day where one index drops 2% and another closes flat is a rotation, not a liquidation, and that is the single most important nuance in today’s tape.
- NO FLIGHT TO SAFETY IN GOLD OR A VIX PANIC (Day) – Two tells that this was a repricing, not the start of an unwind. Gold fell 1.24% to $4,126 as higher real yields did the damage, so the classic inflation hedge did not catch a bid on an inflation-fear day. And the VIX, while up 11.6% to 17.04, stayed in the high teens rather than spiking into the 20s. Both say the market is alert and repricing growth for higher rates, not panicking out of risk altogether.
AFTER-HOURS EARNINGS SPOTLIGHT
Post-Close Reports
- LIGHT POST-CLOSE SLATE (Day) – The day’s big earnings were morning reports, not after-hours ones. Bank of America, Morgan Stanley, and BlackRock all reported before the open, continuing the Q3 financials season, with Bank of America shares pressured after regulators fined the company more than $1.2 billion over compliance failures. The post-4:05 PM ET slate tonight is light, which keeps the market’s full attention on Thursday’s 8:30 AM data dump rather than any single-name after-hours reaction.
- THE REAL CATALYST IS TOMORROW MORNING, NOT TONIGHT (Day) – With no major after-hours earnings to move the tape, the overnight setup is clean: the market closed on the 7,700 shelf and the next real information is PPI, retail sales, and jobless claims all at 8:30 AM ET Thursday. That makes the open tomorrow, not the after-hours session tonight, the moment that decides whether today’s AI-led repricing extends or stabilizes.
WHAT IT SETS UP FOR THURSDAY
The Binary Into The Data Dump
- PPI IS THE SECOND INFLATION READ IN TWO DAYS (Day) – At 8:30 AM ET Thursday, PPI lands right after today’s hot CPI, with headline seen at 0.5% versus 0.4% prior and core at 0.3% versus 0.2%. This is the confirmation print. A hot PPI stacks a second inflation surprise on top of CPI, pushes yields higher, and likely extends the AI selloff below 7,700. A cool PPI gives the market room to argue CPI was a one-off and sets up a bounce off the shelf.
- RETAIL SALES AND CLAIMS ADD TO THE PICTURE (Day) – Alongside PPI, September retail sales are seen at 0.3% versus a strong 1.2% prior, with jobless claims and the Philly Fed survey also hitting at 8:30. The combination tells you whether the consumer is still spending into higher rates and whether the labor market is softening. A hot inflation read paired with still-strong spending is the worst mix for the rate-cut story, while cooling data on both fronts would ease the pressure that drove today’s selloff.
Winners & Losers
Winners
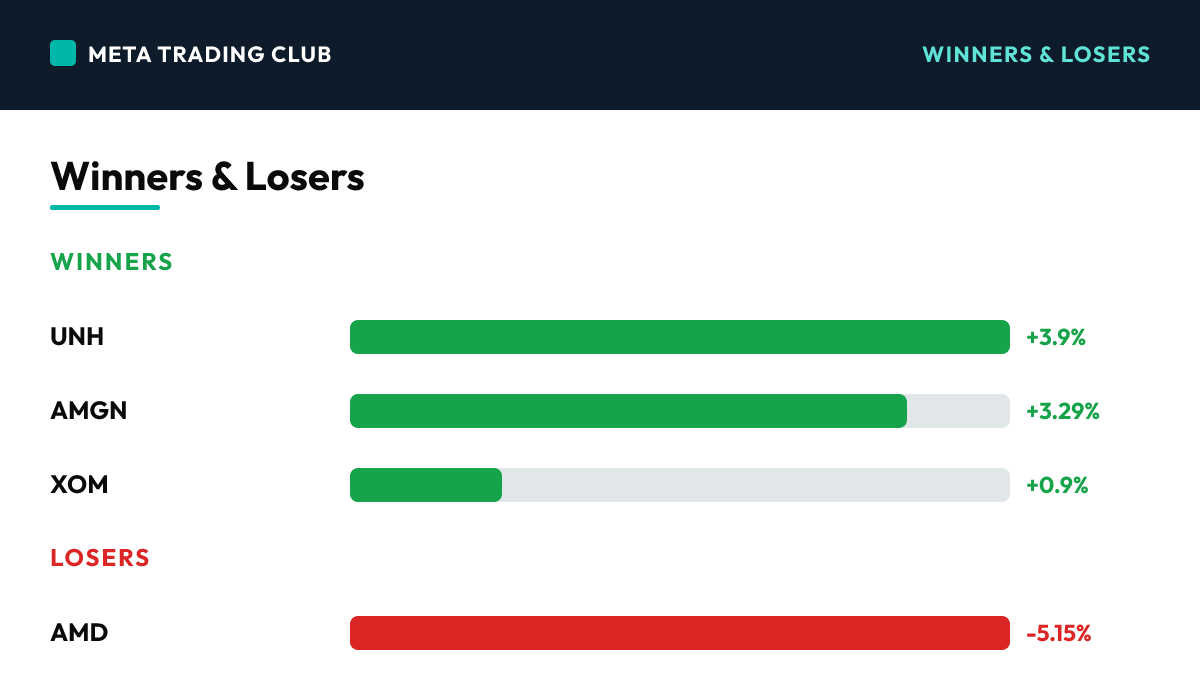
| UNH | +3.9% | UnitedHealth was the standout winner, up about 3.9% on an earnings beat and a guidance hike. On a 2% Nasdaq down day, a defensive giant delivering clean results and raising its outlook was exactly the kind of name money rotated into, and the move single-handedly kept the Dow near flat while growth sold off. It was the clearest expression of the day’s rotation out of expensive growth and into earnings visibility. | |
| AMGN | +3.29% | Amgen climbed about 3.29%, riding the defensive healthcare bid on positive analyst sentiment and pipeline optimism. On a day chips were gutted and the rate story turned risk-off, a steady biopharma name gaining 3% confirmed the selling was targeted at expensive growth, not a wholesale exit, and that money was actively looking for safe, earnings-backed places to hide. | |
| XOM | +0.9% | Exxon Mobil and the energy complex finished modestly higher as WTI crude rose 1.55% toward $96. On a day almost everything cyclical and growth sold off, firm oil gave energy names one of the few bids in the market. The catch is that the same rising crude that lifted energy also fed the inflation worry driving the broader selloff, making energy’s strength both a winner and a warning into Thursday’s PPI. |
Losers
| AMD | -5.15% | Advanced Micro Devices was the sharpest decliner among the mega-cap chips, down 5.15% as the AI and semiconductor trade was gutted by the hot CPI and the jump in yields. AMD has been one of the leaders of the AI run, so a 5% drop on an inflation print is the honest signal of how much air is in the highest-valued, longest-duration names when the rate story turns. When the AI leaders drop this hard, it tells you the market is repricing the premium it has paid for the entire group. | |
| INTC | -4.0% | Intel fell about 4%, swept up in the broad semiconductor selloff as higher yields slammed the chip complex. The decline dragged Technology to the bottom of the sector board and was a major contributor to the Nasdaq’s 2% drop. When the entire chip group sells off together on a macro print rather than company news, it signals the move was about rates and positioning, not any single company’s fundamentals. | |
| MU | -3.6% | Micron Technology slid about 3.6%, continuing to bleed as the semiconductor group took the brunt of the rate-driven selloff and competitive worries in the memory space lingered. Micron is a memory bellwether, so its persistent weakness alongside AMD and Intel confirmed the selling was concentrated in the exact corner that carried the record run. Whether these names find buyers at lower levels is the key question for whether the S&P holds 7,700 into Thursday. |
What It Sets Up For Tomorrow
Levels Into Tomorrow
- S&P 500 7,700 – THE LINE THAT DECIDES IT. Price closed at 7,718.94, sitting right on top of the 7,700 shelf. This is the single most important level on the page. Hold 7,700 through Thursday’s 8:30 AM data dump and today was a one-day repricing in the hottest corner of the market, with the defensive rotation keeping the broader tape intact. Lose 7,700 on a hot PPI, especially with the AI trade still bleeding, and the market is telling you the concentrated weakness is going broad. The first clean move relative to 7,700 after the 8:30 print is the signal to trade, not the data itself.
- S&P 500 7,650 – THE SHELF BELOW. The next real support if 7,700 gives way. A loss of 7,650 would confirm the pullback has legs and open a path toward 7,600 and the larger gap-fill zone beneath it. This is the level that separates a healthy shakeout from a genuine trend change. If the data runs hot and price slices through 7,700 and 7,650 without a fight, respect it and stand aside rather than trying to catch the falling knife.
- S&P 500 7,750 – THE RECLAIM LEVEL. The first ceiling on any bounce. Today’s selloff accelerated under 7,750, so a decisive reclaim of that level on a cool PPI would say the market is shrugging off the CPI scare and the dip is being bought. Until price gets back above 7,750, every bounce is suspect and the path of least resistance stays lower. Watch whether buyers can reclaim it on the first rally attempt Thursday, or whether it caps the tape.
Bull case: The bull case is that today was a single-day, single-theme repricing, not the start of a trend change. The evidence is in the rotation: the Dow closed flat, Health Care rose 2%, Consumer Staples and Energy finished green, and the VIX never spiked past 17. That is money moving from growth into defense, not money leaving the market. If PPI comes in cool Thursday, the CPI print looks like a one-off, yields ease back, and the oversold AI names bounce off the 7,700 shelf. In that scenario the pullback was a healthy reset of the most extended corner of the market, and holding 7,700 confirms the uptrend is still intact.
Bear case: The bear case is that today was the first crack and PPI confirms it. If Thursday’s producer prices also run hot, that is two inflation surprises in two days, the 10-year pushes further above 5.22%, and the rate-hike fear that gutted the AI trade spreads to the rest of the tape. In that scenario the defensive rotation that held the Dow flat today breaks down, 7,700 gives way, and the index opens a path toward 7,650 and 7,600. The concentrated AI weakness becomes everyone’s problem, and the record highs that looked routine a week ago become a distant memory.
Risks Into Tomorrow
- A 2% Nasdaq day and a flat Dow is a rotation, not a crash, so read the whole board — Today is a textbook example of why the index headline alone will fool you. The Nasdaq fell 2% and the Russell fell 2%, which on its own reads like a bad day across the board. But the Dow closed down just 0.09%, basically flat, and Health Care, Consumer Staples, and Energy all finished green. That split is not noise, it is the entire story. When one index drops 2% and another closes flat on the same session, the market is not leaving, it is rotating, in this case out of the expensive, rate-sensitive AI and growth trade and into defensive, earnings-backed names like UnitedHealth and Amgen. The lesson is to always read the full sector board and the breadth, not just the Nasdaq print. A trader who saw only the 2% tech drop would think the market broke; a trader who saw the flat Dow and green defensives would understand it was a repricing of one specific theme. That distinction, a broad liquidation versus a targeted rotation, is the difference between standing aside in fear and recognizing a healthy reset. Today it was clearly the latter, and the proof is in the parts of the market that went up while the headlines went down.
- When gold falls and the VIX stays under 20 on a selloff, the move is about rates, not panic — The two cross-asset tells today both pointed the same direction. Gold, the classic inflation and fear hedge, did not rally on an inflation-fear day, it fell 1.24% as the 10-year yield pushed toward 5.22%. And the VIX, while it jumped 11.6%, stopped at 17.04, firmly in the high-teens rather than spiking into the 20s where real panic lives. Put those two together and they tell you the selloff was driven by rising real yields repricing expensive growth, not by a liquidation-style flight to safety. If this were the start of a genuine unwind, gold would have caught a bid and the VIX would be in the 20s. Neither happened. For a trader, this is the kind of context that keeps you from overreacting. A rate-driven repricing in the most extended corner of the market is a normal, healthy event; a panic liquidation is a different animal that demands you get out of the way. Today the cross-asset evidence said repricing, which is why the right play was to watch 7,700 and wait for the confirmed reaction to Thursday’s data, not to assume the worst and sell into the hole.
- You do not trade the CPI number, you trade the reaction at your level — The temptation after a day like today is to form a strong opinion about where inflation and rates are headed and position for it ahead of Thursday’s PPI. That is a trap. Nobody knows what the producer price number will be, and the market has already shown it can move 2% on a single surprise. The disciplined approach is the one the MTC framework is built on: identify the level that matters, which today is clearly 7,700, and wait for price to show you its hand after the 8:30 AM print. If the S&P holds and reclaims 7,750 on a cool number, that is a confirmed signal the dip is being bought. If it slices through 7,700 and 7,650 on a hot number, that is a confirmed signal to stand aside. Either way, the trade comes from the reaction at the level, not from a prediction about the data. This is the whole point of waiting for alignment: the market will tell you what it wants to do, and your job is to let it confirm before you commit risk. No alignment yet into Thursday. No trade yet.
Frequently Asked Questions
How did the S&P 500 close today?
On Wednesday, October 14, 2026, the S&P 500 closed at 7,718.94 (-1.31%), with the VIX at 17.04. Hot inflation finally bit the stock market today.
What drove the market today?
HOT SEPTEMBER CPI REVIVES RATE-HIKE FEAR (Day) – The trigger for the whole session. Headline CPI rose 0.6% on the month and 3.7% on the year, with core at 0.3% and 2.6%, all hotter than the 0.2% and 2.5% the Street expected. The number put another Fed rate hike back on the table, pushed the 10-year yield toward 5.22%, and sent the most rate-sensitive, highest-valued corners of the market lower. This was the catalyst that turned weeks of quiet into a 2% Nasdaq down day.
What levels matter for tomorrow?
S&P 500 7,700 – THE LINE THAT DECIDES IT. Price closed at 7,718.94, sitting right on top of the 7,700 shelf. This is the single most important level on the page. Hold 7,700 through Thursday’s 8:30 AM data dump and today was a one-day repricing in the hottest corner of the market, with the defensive rotation keeping the broader tape intact. Lose 7,700 on a hot PPI, especially with the AI trade still bleeding, and the market is telling you the concentrated weakness is going broad. The first clean move relative to 7,700 after the 8:30 print is the signal to trade, not the data itself. S&P 500 7,650 – THE SHELF BELOW. The next real support if 7,700 gives way. A loss of 7,650 would confirm the pullback has legs and open a path toward 7,600 and the larger gap-fill zone beneath it. This is the level that separates a healthy shakeout from a genuine trend change. If the data runs hot and price slices through 7,700 and 7,650 without a fight, respect it and stand aside rather than trying to catch the falling knife. S&P 500 7,750 – THE RECLAIM LEVEL. The first ceiling on any bounce. Today’s selloff accelerated under 7,750, so a decisive reclaim of that level on a cool PPI would say the market is shrugging off the CPI scare and the dip is being bought. Until price gets back above 7,750, every bounce is suspect and the path of least resistance stays lower. Watch whether buyers can reclaim it on the first rally attempt Thursday, or whether it caps the tape.
How does Meta Trading Club prepare for the next session?
We wrap every session and carry the read forward through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
New to this? Start with the free training.
Learn how we read the market before you risk a dollar — our free education library and ebook break down the fundamentals step by step.
Free education → Get the free ebookThe session’s over. The prep isn’t.
This is how MTC members close each day — wrap what happened, mark the levels, and carry one clean read into tomorrow. If you want to build that habit and qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process. It’s application-based — see if it’s a fit.
Explore the MTC Incubator → Apply nowSources: Yahoo Finance, CNBC, TheStreet, Benzinga, Investing.com and Schwab closing coverage for October 14, 2026.. For educational purposes only. Not financial advice.