Monday, October 12, 2026 · 4:30 PM ET · MTC Market Close
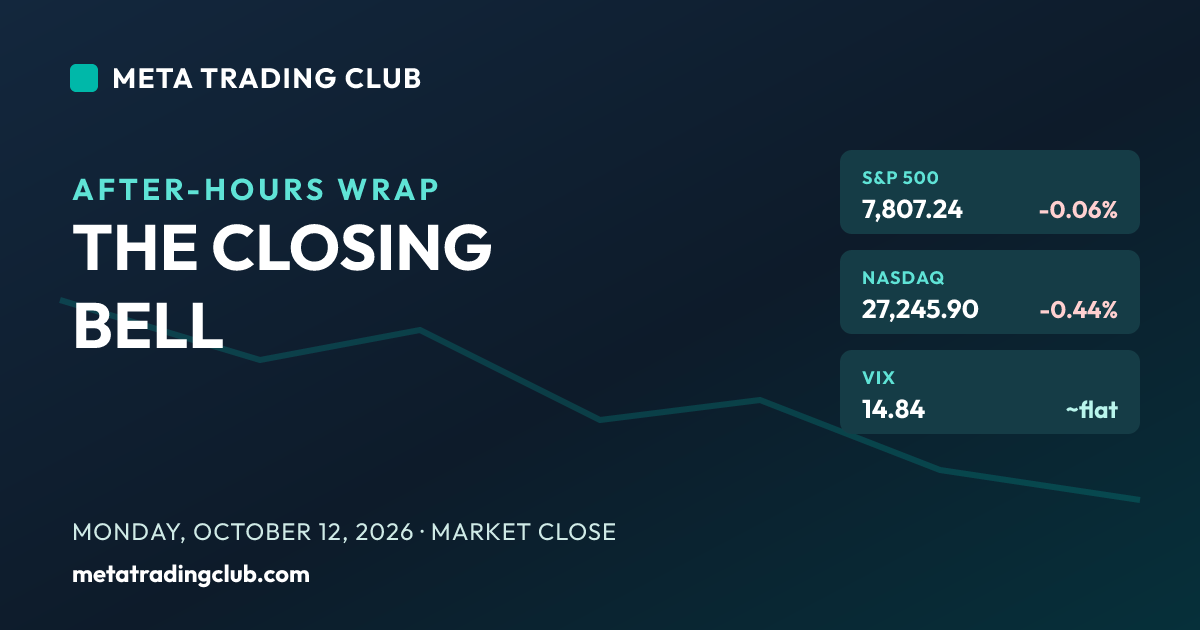
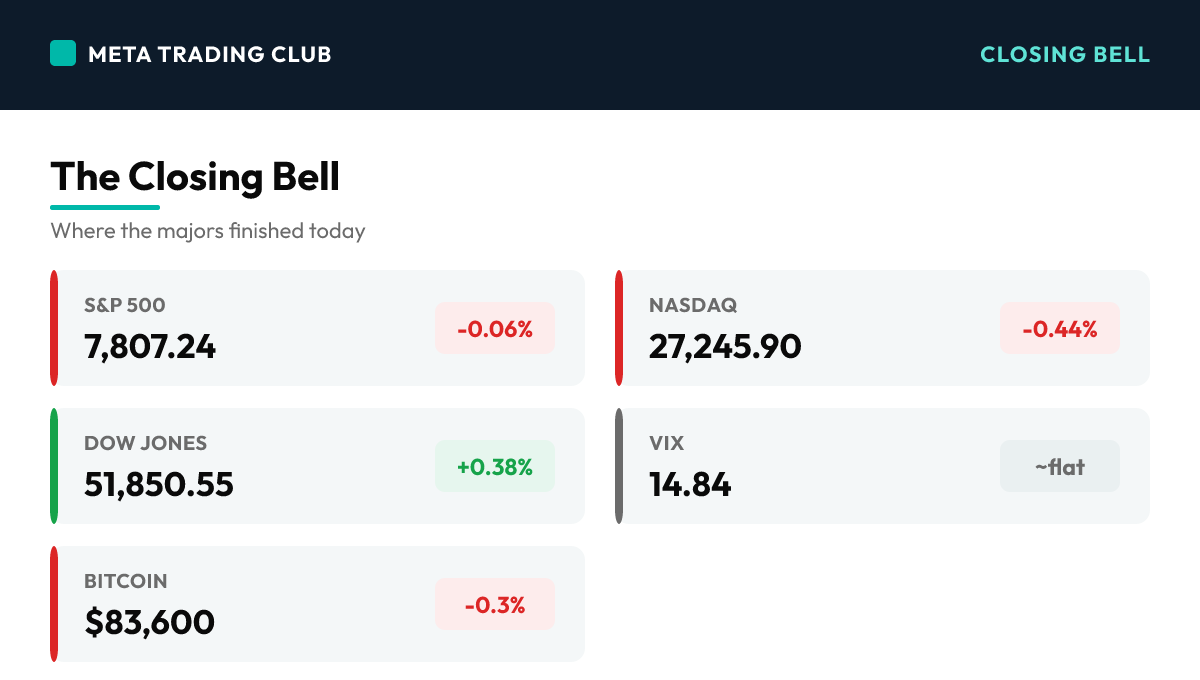
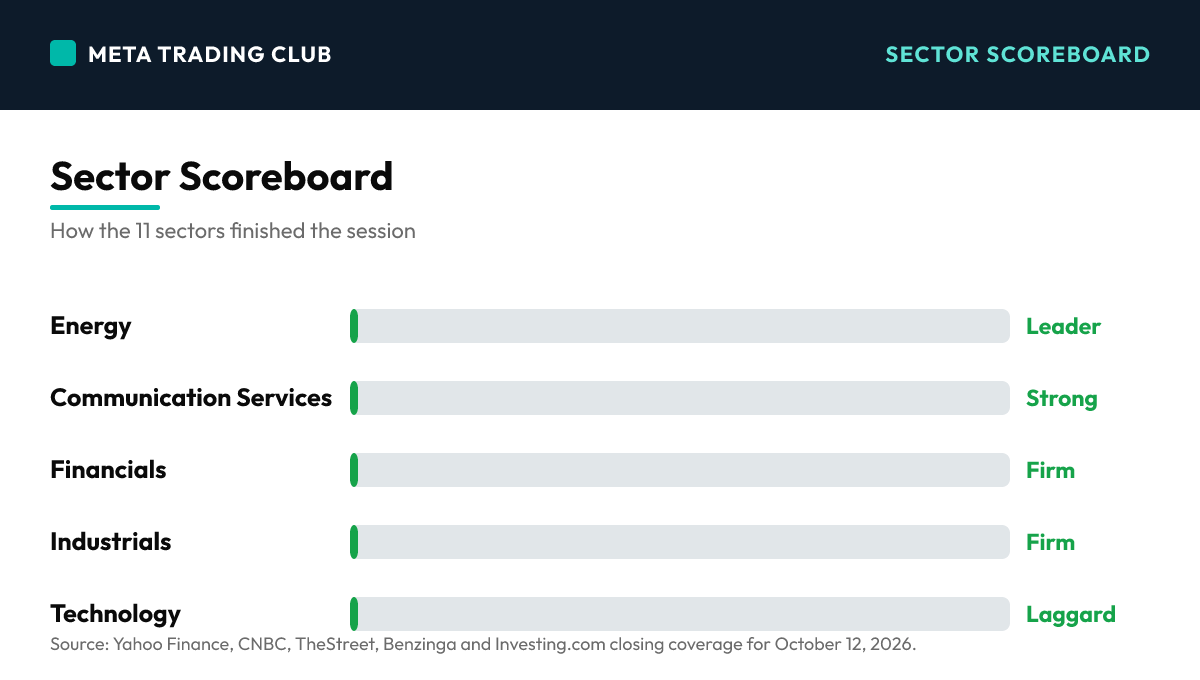
The stock market today looked calm on the surface — a holiday-thinned Columbus Day session — but it still told you something important: the leadership is rotating. The Dow rose 0.38% to 51,850.55 while the Nasdaq slipped 0.44% to 27,245.90 and the S&P 500 finished almost exactly flat, down just 0.06% to 7,807.24. The split is the story. Money came out of mega-cap tech and chips and moved into value, with energy leading as WTI crude jumped about 1.9% back toward $93 on Middle East supply worries. Nine of the eleven S&P sectors actually closed higher even though the index was flat, which tells you the weakness was concentrated in semiconductors, where the group fell roughly 2.7%, dragged by memory names like SanDisk off almost 7% into its earnings. With the bond market closed for the holiday there was no fresh read from yields, and volume ran thin, so none of this is a high-conviction signal on its own. What matters is where it leaves the tape: the S&P closed just above 7,800, the line it has defended for a week, right as the real catalysts arrive. Big-bank earnings hit Tuesday morning with JPMorgan, Goldman, Wells Fargo and Citi, and September CPI lands Wednesday. That hands tomorrow a clean read. Hold 7,800 through the bank numbers and the rotation is healthy churn under a rising market. Lose it and the quiet tech weakness becomes the whole market’s problem.
The Closing Bell
| Instrument | Close | Change | Note |
|---|---|---|---|
| S&P 500 | 7,807.24 | -0.06% | Finished almost perfectly flat, down about 4 points to 7,807.24, and that flat number hides a rotation underneath. Nine of the eleven sectors actually closed higher, but the index was pinned because its heaviest weights, mega-cap tech and semiconductors, were the two groups that fell. The index is sitting just above 7,800, the shelf it has defended for a week, and just below its record near 7,816. That makes 7,800 the single line that matters into Tuesday’s bank earnings: hold it and the rotation is healthy, lose it and the quiet tech weakness spreads. |
| Nasdaq | 27,245.90 | -0.44% | The laggard of the day, off about 0.44% as money rotated out of the tech and semiconductor names that carry the most weight here. The semiconductor group fell roughly 2.7%, with memory names leading the slide, and that was enough to pull the Nasdaq red even on a day most of the market rose. This is the clean read on the session: the weakness was not broad, it was concentrated in the exact corner that led the rally for months, which is why a flat S&P and a red Nasdaq sat side by side. |
| Dow Jones | 51,850.55 | +0.38% | The winner of the majors, up about 196 points, or 0.38%, as the blue-chip index with the least AI and chip exposure caught the rotation into value and industrials. On a day the Nasdaq fell, a green Dow is the clearest picture of where the money went: out of growth and into the cyclical, energy-heavy, dividend-paying corners of the market. When the Dow leads and the Nasdaq lags, that is rotation, not risk-off, and today was a textbook example. |
| Russell 2000 | 2,794.48 | -0.45% | Small caps slipped about 0.45% to 2,794.48, trailing the large-cap value trade. With the bond market closed for the holiday there was no fresh relief on rates, and the most rate-sensitive corner of the market stayed heavy. A modest red day fits a session where the rotation favored the big, cash-rich value names over the smaller, more leveraged ones that need lower yields to work. |
| VIX | 14.84 | ~flat | The volatility gauge sat near 14.84, essentially unchanged on a quiet, holiday-thinned session. A sub-15 VIX tells you the market is calm and complacent heading into a genuinely heavy week, with big-bank earnings Tuesday and CPI Wednesday. That calm is worth noting: when fear is this low right before a wall of catalysts, there is little cushion if the numbers disappoint. The level, not a dramatic move, is the signal here. |
| 10-Year Yield | ~5.30% | closed | No official close today. The Treasury market was shut for the Columbus Day holiday, so the 10-year sits where it finished Friday, near 5.30% and still a hair off multi-decade highs. That matters because yields reopen Tuesday right as bank earnings and the run-up to Wednesday’s CPI begin. The rate backdrop is still the heavy ceiling over the long-duration tech names, and the bond market gets its say again starting tomorrow. |
| WTI Crude | $93.00 | +1.9% | The driver of the day’s rotation, up about 1.9% back toward $93 a barrel as Middle East supply worries firmed the energy complex. Rising crude put energy at the top of the sector board and gave the value trade its engine. A firmer oil tape is a double-edged sword, though: it helps energy earnings but feeds the inflation worry heading into Wednesday’s CPI, which is exactly why a crude pop matters more than usual this week. Level approximate into the settle. |
| Gold | $4,168.78 | -0.60% | Eased about 0.6% to near $4,169 an ounce, giving back a little ground on a quiet session. After a strong run, a modest pullback in gold on a low-volume holiday is noise more than signal. The metal remains elevated as a hedge against the restrictive-rate, sticky-inflation backdrop, and a small down day does not change that bigger picture. Level approximate into the settle. |
| Bitcoin | $83,600 | -0.3% | Hovered near $83,600, little changed on the session after opening higher and fading through the day. Crypto has been pressured by the same high-yield backdrop weighing on long-duration growth, and a flat-to-lower Bitcoin on a quiet day fits that theme. The risk appetite that showed up today went into energy and value, not the speculative end of the risk complex. Level approximate into the settle. |
Today’s Charts
Daily candlestick charts with 20/50/200-day moving averages — the index majors, the day’s biggest mover on each side, and the leading sector ETF.

Charts: Finviz (daily). Levels and overlays update through the next session.
Sector Scoreboard
What Drove The Day
This was a thin, holiday-shortened session that still carried a clear message: the market rotated. The Dow rose 0.38% while the Nasdaq fell 0.44% and the S&P 500 finished flat at 7,807.24, down a rounding error. The order of the board told the whole story. Blue-chip industrials and value led, energy topped the sectors as WTI crude jumped about 1.9% toward $93 on Middle East supply worries, and nine of the eleven S&P sectors actually closed green. The drag came from the one place it has not come from in months, technology, where the semiconductor group fell roughly 2.7% and memory names like SanDisk dropped almost 7% ahead of earnings. With the bond market closed for Columbus Day there was no fresh read from yields and volume ran light, so this is a low-conviction tape rather than a trend to chase. The real test arrives immediately: big-bank earnings Tuesday morning from JPMorgan, Goldman, Wells Fargo and Citi, then September CPI on Wednesday. The S&P closed pinned just above 7,800, the level it has defended all week, which turns a quiet rotation day into a clean binary for Tuesday rather than a signal on its own.
MAJOR HEADLINES AND CATALYSTS
Top Market-Moving Stories
- ROTATION OUT OF TECH, INTO VALUE (Day) – The defining move of the day. The Dow rose 0.38% while the Nasdaq fell 0.44% and the S&P finished flat, as money came out of mega-cap tech and chips and moved into energy, industrials and other value groups. Nine of eleven sectors closed higher even with a flat index. When the Dow leads and the Nasdaq lags on the same day, that is rotation, and today was a clean example of it.
- ENERGY LEADS AS OIL JUMPS (Day) – WTI crude climbed about 1.9% back toward $93 a barrel on renewed Middle East supply worries, pushing energy to the top of the sector board. The firmer oil tape was the engine of the rotation into value, but it also feeds the inflation worry into Wednesday’s CPI. A crude pop that helps energy earnings and pressures the inflation read at the same time is a double-edged catalyst this week.
- SEMICONDUCTORS SELL OFF AGAIN (Day) – The chip group fell roughly 2.7%, the clear drag on the tape, led by memory names. SanDisk dropped almost 7% ahead of its earnings and the caution spread across the storage and memory complex. After leading the market for months, semis were the one corner that could not participate today, and because they carry so much index weight, that weakness was enough to pin the S&P flat and pull the Nasdaq red.
- A QUIET HOLIDAY TAPE BEFORE A LOUD WEEK (Day) – Volume ran thin with the bond market closed for Columbus Day, so none of today’s moves carry full conviction. That calm is the setup, not the story. Big-bank earnings hit Tuesday morning and September CPI lands Wednesday, which means the market is sitting still right before its biggest catalysts in weeks. A sub-15 VIX into that wall of data is worth respecting.
AFTER-HOURS EARNINGS SPOTLIGHT
A Light Post-Close Slate
- NO MAJOR S&P NAMES AFTER THE BELL (AH) – Monday’s post-close earnings slate was light, with no index-moving S&P 500 reports hitting the tape after 4:05 PM ET. That is the calm before the storm: the real earnings season kicks off tomorrow morning, so today leaves the quiet rotation as the full story and keeps all eyes on the technical setup into Tuesday.
- THE BANKS OPEN THE FLOODGATES TUESDAY (AH) – The next, and far bigger, catalysts arrive before Tuesday’s open with JPMorgan, Goldman Sachs, Wells Fargo and Citigroup all reporting Q3 results. These numbers, and especially management commentary on the consumer and lending in a world of higher oil and yields, will set the tone for financials and the broader tape far more than anything that happened on a thin holiday Monday.
WHAT IT SETS UP FOR TUESDAY
The Banks Decide, and 7,800 Keeps Score
- 7,800 IS THE LINE THAT MATTERS (AH) – The S&P closed at 7,807.24, parked just above the 7,800 shelf it has defended for a week and just below its record near 7,816. With big-bank earnings before the open, there is a real catalyst to force the move. Hold 7,800 through the bank numbers and the rotation reads as healthy churn under a rising market. Lose it and today’s quiet tech weakness starts to look like the whole market’s problem.
- WATCH THE BANKS AND THE CHIPS (AH) – Two tells into Tuesday. First, the bank reactions: strong numbers and upbeat consumer commentary would confirm the rotation into value and keep the tape supported. Second, whether the semiconductor selling stops or spreads. If chips stabilize while banks deliver, the rotation is healthy. If semis keep sliding and the banks disappoint, the quiet weakness becomes the story and 7,800 gets tested.
Winners & Losers
Winners
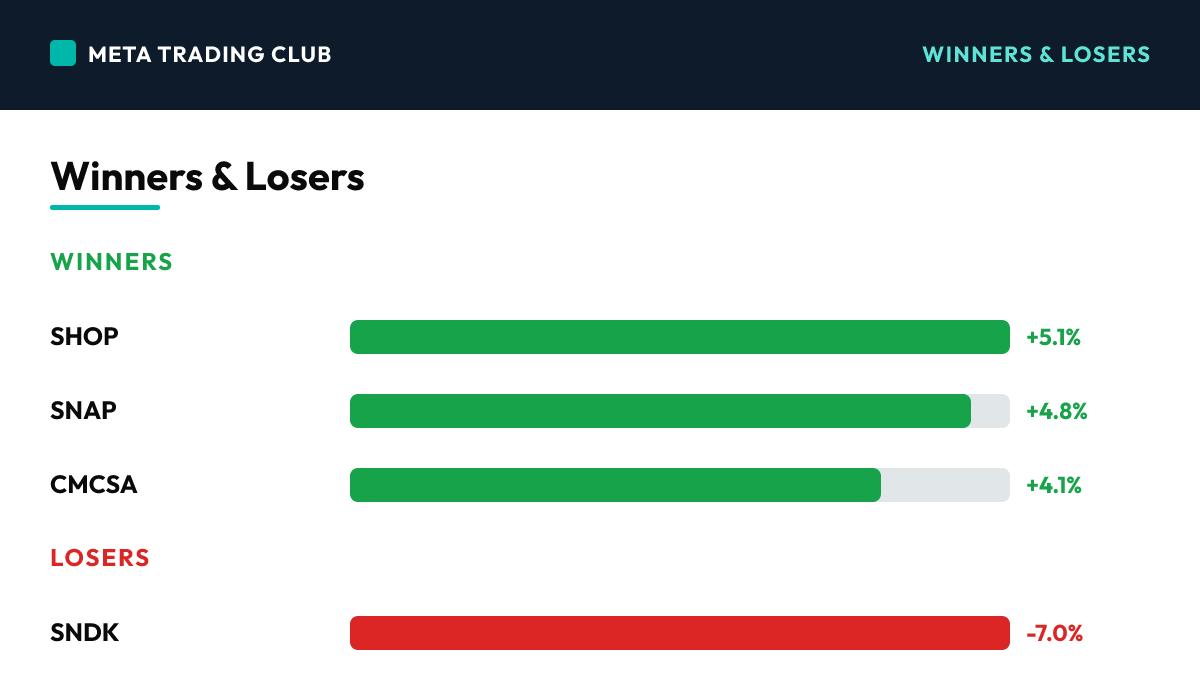
| SHOP | +5.1% | Shopify was the standout gainer of the day, up about 5.1% as money rotated toward select growth and consumer names with momentum. On a day the broad tech complex lagged, Shopify’s strength showed the rotation was selective rather than a blanket exit from growth, with buyers still willing to pay up for the right names even as chips sold off. | |
| SNAP | +4.8% | Snap jumped about 4.8%, one of the top movers in the communication services group that finished near the top of the sector board. The gain fit the day’s selective-rotation theme, with specific names in communication and consumer catching a bid even as the heavyweight semiconductor names dragged the Nasdaq lower. | |
| CMCSA | +4.1% | Comcast rose about 4.1%, helping lift communication services and the value-leaning tape. On a day the rotation favored cyclical and dividend-paying names over high-multiple tech, Comcast was exactly the kind of steadier, cash-generating name that caught the flows leaving the chip complex. |
Losers
| SNDK | -7.0% | SanDisk was the day’s clear decliner, down about 7% ahead of its earnings as caution swept back across the memory and storage complex. The slide was the sharpest symptom of the broader semiconductor weakness, and it dragged the chip group down roughly 2.7% on the session. When a memory name drops this hard into its report, it signals the market is nervous about the group that led the entire rally. | |
| BE | -6.9% | Bloom Energy sank about 6.9% as investors took profits following a massive recent rally. The pullback is a reminder that the hottest momentum names cut both ways, and on a quiet holiday session the path of least resistance for an overextended winner was lower. The move reflects profit-taking rather than a change in the story. | |
| NVDA | -1.7% | Nvidia slipped about 1.7%, part of the broad semiconductor pullback that defined the day’s weakness. On a session where money rotated out of the AI and chip leaders into value, the sector’s bellwether fading is the same story told through its biggest name: the trade that led for months took a step back while the rest of the market rotated higher. Move reflects the regular session. |
What It Sets Up For Tomorrow
Levels Into Tomorrow
- S&P 500 7,800 – THE LINE THAT DECIDES IT. Price closed at 7,807.24, sitting just above the 7,800 shelf it has defended all week. This is the single most important level on the page. Hold 7,800 through Tuesday’s bank earnings and today’s rotation reads as healthy churn, with a clear path back toward the record near 7,816. Lose it, especially if the chip selling spreads and the banks disappoint, and the market is telling you the quiet tech weakness is becoming everyone’s weakness. The first clean move relative to 7,800 after the bank numbers tells you whether the breakout stays alive.
- S&P 500 7,816 – THE RECORD TO RECLAIM. The all-time high and the ceiling this tape has to clear to prove the rotation is powering a broad advance, not just defending a line. A decisive close above 7,816 on strong bank earnings would confirm the money leaving tech is finding a home that lifts the whole index. Until that happens, the market is holding its ground rather than breaking out, and the record stays just out of reach.
- S&P 500 7,750 – THE SHELF BELOW. The next real support if 7,800 gives way. A loss of 7,750 would confirm that the rotation could not hold the line and that the chip weakness was the honest signal. This is where quiet churn turns into a genuine pullback, and where the most rate-sensitive and lower-quality names would likely lead the move lower, especially with yields reopening near 5.30%.
Bull case: The rotation is healthy and the tape is resilient. Nine of eleven sectors closed higher, energy and value are leading, and the market held 7,800 on a day its heaviest sector sold off, which is a sign of underlying strength, not weakness. If Tuesday’s bank earnings come in strong with upbeat commentary on the consumer, the money leaving tech finds a durable home in financials, energy and industrials, the S&P holds 7,800 and presses back toward its record at 7,816. In this read, the chip selling is a healthy unwind of a crowded trade while the broad market quietly improves underneath.
Bear case: A flat index is masking a crack in the leadership. The group that carried this entire rally, semiconductors, fell almost 3% today, and memory names are sliding into earnings. If the chip weakness spreads and Tuesday’s banks disappoint, or guide cautiously on the consumer, the rotation runs out of buyers, the S&P loses 7,800, and the quiet weakness in the market’s most important sector becomes the whole market’s problem. Add a crude pop feeding Wednesday’s CPI worry and a bond market reopening near multi-decade-high yields, and the path back toward 7,750 opens quickly.
Risks Into Tomorrow
- A flat index can hide a rotation, so read the sectors, not the headline — The S&P finished down a rounding error today, and a trader who only glanced at that number would have missed the entire story. Underneath that flat close, nine of eleven sectors rose, energy led on a crude pop, value and industrials caught a bid, and the only real weakness was concentrated in semiconductors. That is rotation, not stagnation, and it is a completely different market than a flat tape with broad, listless trading. The lesson is to always look past the index print to the participation behind it. Breadth and sector leadership tell you where the money is actually moving, and today the money was moving with conviction, just not in the direction the headline number suggested. When the Dow leads and the Nasdaq lags, the market is making an active choice about what it wants to own, and your job is to read that choice rather than the flat number on the screen. The discipline is to let the internals, not the index, define the day, because a flat S&P built on a healthy rotation is a very different setup than a flat S&P built on nobody showing up. Today was the former, and that distinction is the whole read into Tuesday.
- When the market’s leader sells off, watch whether it spreads or gets absorbed — Semiconductors carried this entire rally, and today they fell almost 3% while the rest of the market rose. That is a specific, important kind of signal, and how you handle it separates disciplined traders from reactive ones. There are two ways this resolves. Either the broad rotation absorbs the chip weakness, with value and cyclicals continuing to lift the index while the crowded tech trade quietly unwinds, or the selling in the market’s most heavily weighted sector eventually drags the indexes it dominates down with it. You do not know which yet, and pretending you do is how you get hurt. The right move is to treat the leader’s weakness as a question, not an answer. Watch whether the chip selling stabilizes or accelerates over the next session, because that tells you which scenario is playing out. A one-day pullback in an extended, crowded group after months of gains is normal and healthy. A multi-day slide that starts pulling the broad index through support is a different animal entirely. The lesson is patience: let the market show you whether this is a healthy unwind or the start of something bigger before you position around it. No alignment between the leader and the tape means you wait for confirmation, and the level, 7,800, will tell you when the question has been answered.
- Low volatility into a wall of catalysts is a setup, not a signal of safety — The VIX sat near 14.84 today, a calm, sub-15 reading, and the temptation on a quiet holiday session is to read that as the all-clear. It is the opposite. The market is sitting still right before its biggest week of catalysts in a month: big-bank earnings before Tuesday’s open and September CPI on Wednesday, with the bond market reopening near multi-decade-high yields and crude firming into the inflation read. Low volatility going into that wall of data does not mean the risk is low. It means the market is complacent, and complacency is exactly when there is the least cushion if the numbers disappoint. The lesson is that volatility is a measure of how much protection the market is pricing, not a measure of how much risk actually exists. When the two diverge, when real catalysts are stacking up but the fear gauge is asleep, the disciplined move is to respect the gap rather than lean into the calm. That means sizing for the possibility of a sharp move in either direction, keeping risk defined, and not confusing a quiet tape for a safe one. The calm is the setup. The bank earnings and the inflation print are what the market will actually trade, and a sub-15 VIX just means the move, whichever way it breaks, has room to be larger than anyone is currently pricing.
Frequently Asked Questions
How did the S&P 500 close today?
On Monday, October 12, 2026, the S&P 500 closed at 7,807.24 (-0.06%), with the VIX at 14.84. The stock market today looked calm on the surface — a holiday-thinned Columbus Day session — but it still told you something important: the leadership is rotating.
What drove the market today?
ROTATION OUT OF TECH, INTO VALUE (Day) – The defining move of the day. The Dow rose 0.38% while the Nasdaq fell 0.44% and the S&P finished flat, as money came out of mega-cap tech and chips and moved into energy, industrials and other value groups. Nine of eleven sectors closed higher even with a flat index. When the Dow leads and the Nasdaq lags on the same day, that is rotation, and today was a clean example of it.
What levels matter for tomorrow?
S&P 500 7,800 – THE LINE THAT DECIDES IT. Price closed at 7,807.24, sitting just above the 7,800 shelf it has defended all week. This is the single most important level on the page. Hold 7,800 through Tuesday’s bank earnings and today’s rotation reads as healthy churn, with a clear path back toward the record near 7,816. Lose it, especially if the chip selling spreads and the banks disappoint, and the market is telling you the quiet tech weakness is becoming everyone’s weakness. The first clean move relative to 7,800 after the bank numbers tells you whether the breakout stays alive. S&P 500 7,816 – THE RECORD TO RECLAIM. The all-time high and the ceiling this tape has to clear to prove the rotation is powering a broad advance, not just defending a line. A decisive close above 7,816 on strong bank earnings would confirm the money leaving tech is finding a home that lifts the whole index. Until that happens, the market is holding its ground rather than breaking out, and the record stays just out of reach. S&P 500 7,750 – THE SHELF BELOW. The next real support if 7,800 gives way. A loss of 7,750 would confirm that the rotation could not hold the line and that the chip weakness was the honest signal. This is where quiet churn turns into a genuine pullback, and where the most rate-sensitive and lower-quality names would likely lead the move lower, especially with yields reopening near 5.30%.
How does Meta Trading Club prepare for the next session?
We wrap every session and carry the read forward through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
New to this? Start with the free training.
Learn how we read the market before you risk a dollar — our free education library and ebook break down the fundamentals step by step.
Free education → Get the free ebookThe session’s over. The prep isn’t.
This is how MTC members close each day — wrap what happened, mark the levels, and carry one clean read into tomorrow. If you want to build that habit and qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process. It’s application-based — see if it’s a fit.
Explore the MTC Incubator → Apply nowSources: Yahoo Finance, CNBC, TheStreet, Benzinga and Investing.com closing coverage for October 12, 2026.. For educational purposes only. Not financial advice.