Friday, October 16, 2026 · 8:45 AM ET · MTC Market Intelligence
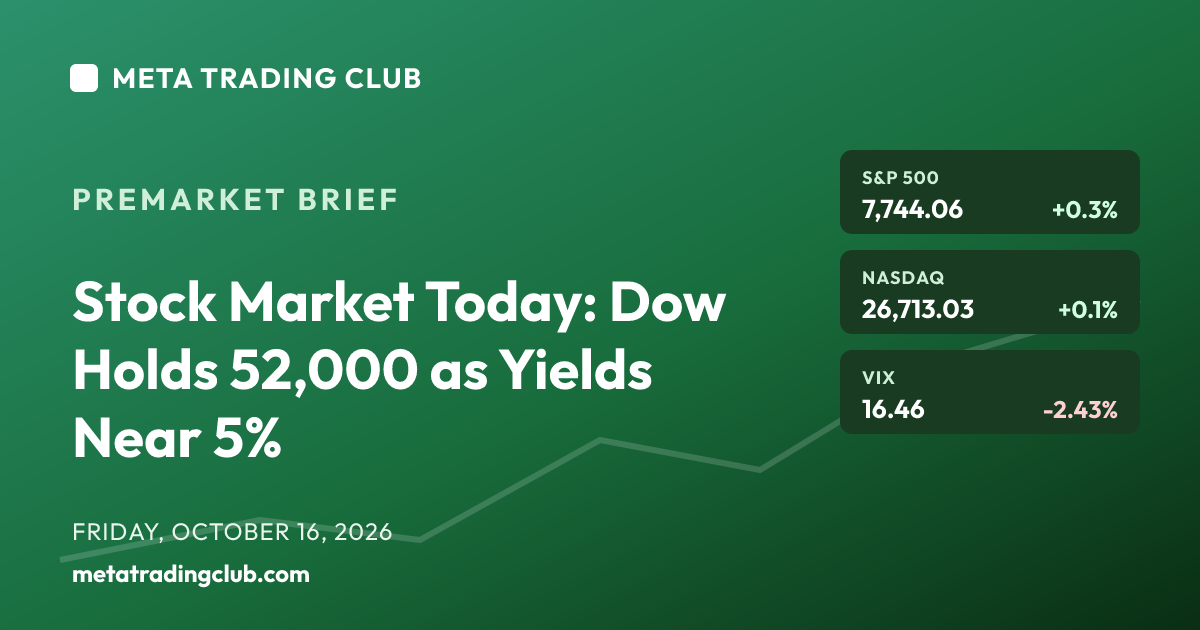
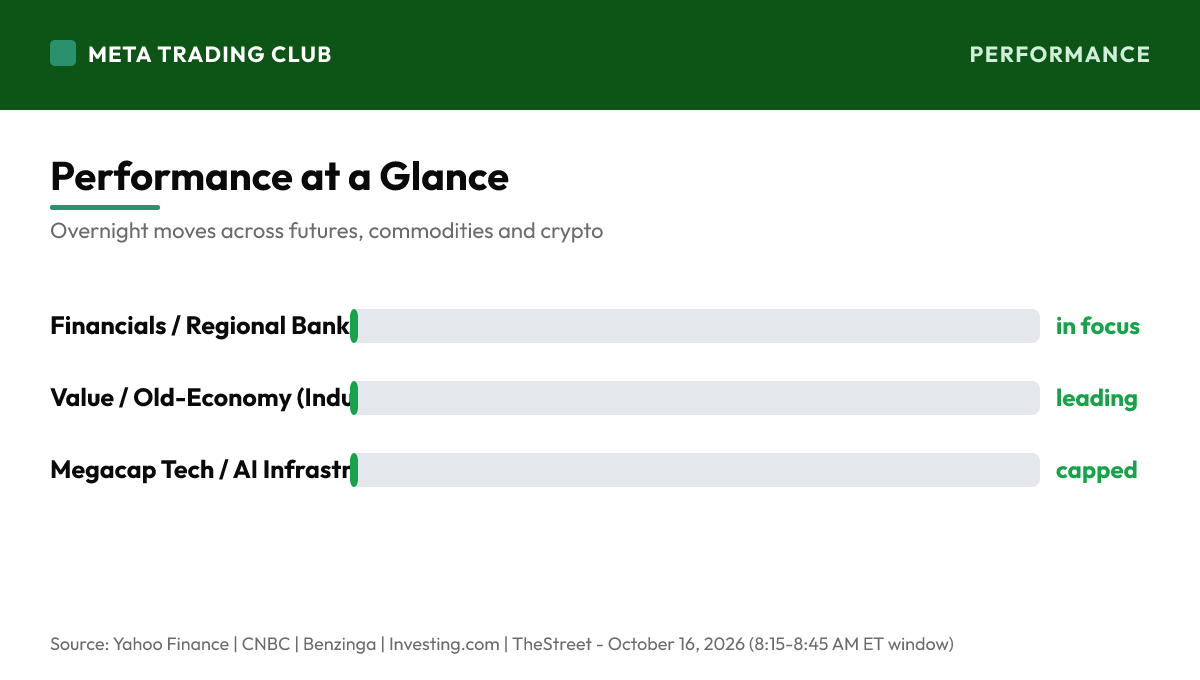
The stock market today opens with a split personality — and that split is the whole read. Thursday the Dow ripped 556 points (+1.1%) to 52,177.69 as the AI jitters from earlier in the week faded, while the Nasdaq Composite barely moved, up just 0.1% to 26,713.03, and the S&P 500 added 0.3% to 7,744.06. This morning the same shape holds: Dow futures lead green, up about 0.41%, S&P 500 futures are modestly higher around +0.19%, and Nasdaq futures sit essentially flat, down about 0.06%. The story behind the split is rates. A hot inflation week — September PPI jumped 1.3% month over month (6.3% year over year) and core CPI firmed to 2.6% — has pushed the 10-year Treasury yield above 5%, now near 5.08%, and that is the lid keeping growth and the most rate-sensitive AI names capped even on an up day. Money keeps favoring old-economy and value over high-multiple tech. Tesla is the standout mover, up about 4.6% premarket after unveiling its second-generation Roadster, while Hubbell leads gainers around +5%. The other side of the tape: CoreWeave is down about 4% as rising borrowing costs squeeze the most indebted AI-infrastructure names, Travelers is off about 4% despite beating, and Netflix slips about 1.5% on a leadership shake-up. VIX has cooled to 16.46, down about 2.4%, WTI is softer near $95.84, and Bitcoin is recovering near $82,000 but still set for a second straight down week. It’s a heavy morning for financials: SLB, Truist, Regions, Citizens and M&T all report, making the regional banks a live read on what 5% rates are doing to the group. Data lands too — import/export prices at 8:30, industrial production and capacity utilization at 9:15 — and Fed Chair Warsh speaks in a fireside chat at the IMF meetings. Mark SPX 7,700 as the pivot the index held all week, 7,780 as the record-chase wall it still has to clear, and 7,615 as the deeper floor. The scorecard so far: the Dow reclaimed its lead, but a 5% 10-year keeps the lid on the record chase. A bounce isn’t a trend until the level holds. No alignment, no trade.
Market Snapshot
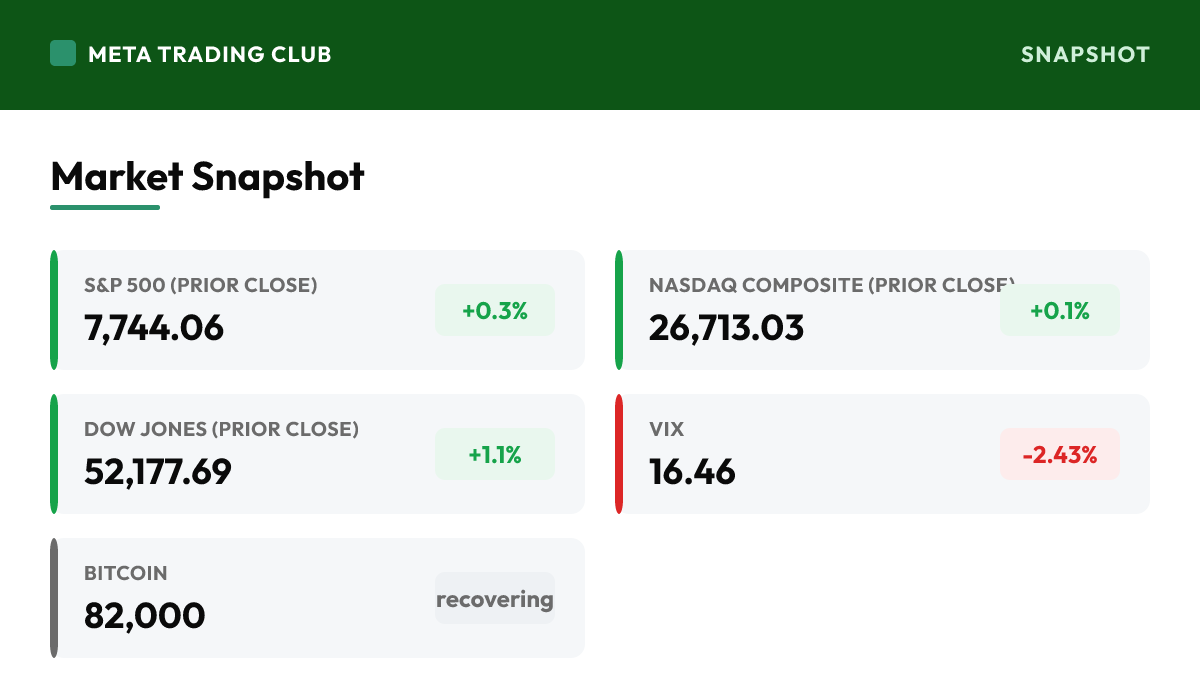
| Instrument | Level | Change | Note |
|---|---|---|---|
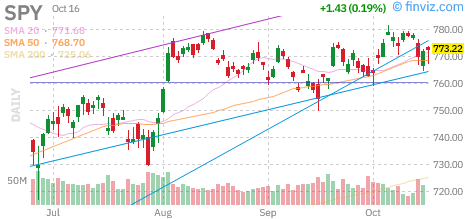
| S&P 500 (prior close) | 7,744.06 | +0.3% | Added 0.3% Thursday to 7,744.06, erasing an early loss and pulling back toward the all-time high set last week. This morning S&P 500 futures are up about 0.19% — green, but lagging the Dow because the index is still carrying its heavy tech weighting into a 5% rate backdrop. The level that matters is 7,700: the bull/bear pivot the index defended all week. Hold above it and the structure stays intact; the real prize is 7,780, the record-chase wall it has to clear on real volume to say the breakout is back on. |
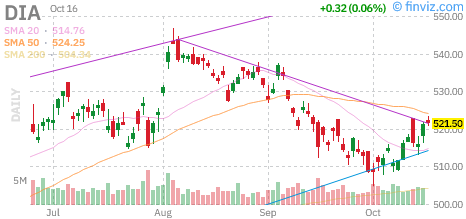
| Dow Jones (prior close) | 52,177.69 | +1.1% | The star of Thursday — up 556.21 points, or 1.1%, to 52,177.69 as money rotated into old-economy and value names while tech sat out. This morning Dow futures lead again, up about 0.41%, and that is the tell: in a 5% yield world, the market keeps rewarding the Dow’s lower-multiple, cash-generating mix over high-growth tech. A Dow that holds above 52,000 while the Nasdaq idles says the rebound has a floor — watch whether that leadership sticks into the open. |
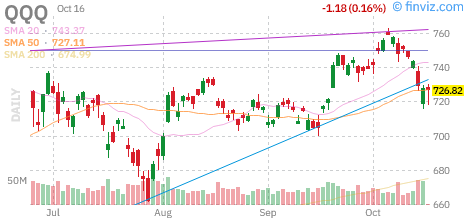
| Nasdaq Composite (prior close) | 26,713.03 | +0.1% | Barely budged Thursday, up just 0.1% to 26,713.03 while the Dow ripped — the clearest sign that rates, not demand, are the constraint. This morning Nasdaq futures are essentially flat, down about 0.06%, as CoreWeave and the most indebted AI names stay heavy under rising borrowing costs. Tech can’t lead until the 10-year backs off 5%; until then the Nasdaq grinds while value does the work. Watch the chips and AI-infrastructure names for whether the group can even hold flat. |
| Russell 2000 (prior close) | — | N/A | Small caps are the rate-sensitivity gauge today. With the 10-year pinned above 5%, the Russell carries the heaviest borrowing-cost burden of the major indices, so watch whether it can join the Dow’s value bid or gets left behind. A Russell that leads would say the market is betting rates have peaked; a Russell that lags says 5% is still doing damage to the most rate-exposed corner of the tape. Treat it as a breadth and rate-direction tell, not a standalone setup. |
| VIX | 16.46 | -2.43% | Cooled about 2.4% to 16.46 as the week’s inflation scare drained out of the tape and the Dow-led rebound steadied nerves. That’s a calm reading — fear is leaving — but calm during a 5% rate backdrop can be complacency as much as comfort. Watch for a push back above 18 if the data runs hot or yields reverse higher; a VIX that stays pinned in the mid-16s says the market has made peace with higher-for-longer, at least for now. |
| WTI Crude | 95.84 | lower | Softer near $95.84, down about 1.7% as risk sentiment steadied and the dollar firmed. Oil in the mid-90s keeps a floor under headline inflation without being today’s driver — the inflation story this week was services and core, not energy. Treat crude as a quiet cross-check on the inflation narrative rather than the main event; a sharp move either way would matter for the rate read, but at these levels it’s a sidebar to the yield story. |
| 10-Yr Treasury | 5.08% | higher | Sitting near 5.08%, above the 5% line, and this is the single most important number on the board. A hot inflation week — PPI up 1.3% month over month, core CPI firming to 2.6% — has repriced the rate path higher for longer, and that yield is the lid on growth stocks, small caps and the most leveraged AI names. As long as the 10-year holds above 5%, value leads and tech stays capped. A move back under 5% would be the release valve the Nasdaq needs; a push toward 5.15%-plus would tighten the screws again. |
| Bitcoin | 82,000 | recovering | Recovering near $82,000 after a rough stretch, but still on track for a second straight week in the red. Crypto’s bounce tracks the broader risk-appetite steadying that lifted the Dow, yet the recovery is tentative with rates this high — the same 5% yield that caps tech is a headwind for risk assets broadly. A reclaim and hold back above $85K would say risk appetite is genuinely healing; a slide back under $80K would flag that the week’s caution hasn’t fully cleared. |
Charts to Watch
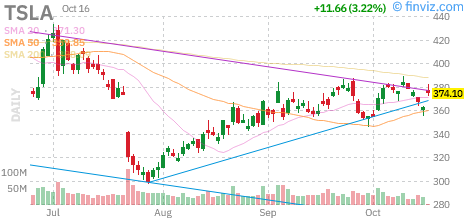
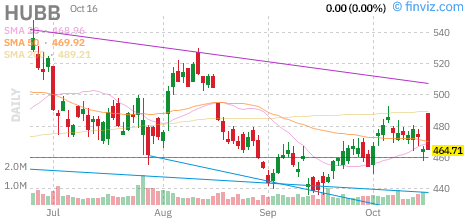
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
Overnight & Global Markets
Thursday reset the tone after a jittery week: the Dow surged 556.21 points (+1.1%) to 52,177.69 as the AI-debt fears that dominated midweek faded, while the Nasdaq Composite added just 0.1% to 26,713.03 and the S&P 500 rose 0.3% to 7,744.06, closing back near its record. The split told the story — value and old-economy names did the heavy lifting while tech sat out, because the overhang is rates. A hot inflation week (PPI +1.3% m/m, 6.3% y/y; core CPI 2.6%) has pushed the 10-year above 5%, now near 5.08%, and that yield is the lid on growth. This morning the same shape holds: Dow futures lead up about 0.41%, S&P 500 futures are up about 0.19%, and Nasdaq futures are essentially flat, down about 0.06%. Tesla is the standout, up about 4.6% on its second-gen Roadster unveil, with Hubbell leading gainers near +5% and Alcoa higher on an earnings beat. The other side: CoreWeave is down about 4% as borrowing costs squeeze the most indebted AI names, Travelers is off about 4% despite a beat, and Netflix slips about 1.5% on a leadership shake-up. VIX cooled to 16.46, WTI eased to $95.84, and Bitcoin is recovering near $82,000. Financials headline the earnings slate — SLB, Truist, Regions, Citizens and M&T — making the regional banks a live read on 5% rates. Data hits at 8:30 (import/export prices) and 9:15 (industrial production, capacity utilization), and Fed Chair Warsh speaks at the IMF meetings. Mark SPX 7,700 as the pivot held all week, 7,780 as the record-chase wall, and 7,615 as the deeper floor. A bounce isn’t a trend until the level holds. No alignment, no trade.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- Rates are running the tape, and the split futures prove it. Dow futures lead up about 0.41% while Nasdaq futures sit flat, down about 0.06% — the same value-over-growth shape that drove Thursday’s 556-point Dow rally. The reason is the 10-year near 5.08% after a hot inflation week: September PPI jumped 1.3% month over month (6.3% y/y) and core CPI firmed to 2.6%, repricing the rate path higher for longer. As long as the 10-year holds above 5%, the market keeps paying up for cash-generating value and capping high-multiple tech. This isn’t a demand story — it’s a discount-rate story.
- Tesla is the standout single-stock move, up about 4.6% premarket after unveiling its second-generation Roadster at a Thursday event, with the company touting rocket-style thrusters and aerial maneuvers and targeting production in 2028. Hubbell leads the broader gainers list near +5% and Alcoa is firm on a Q3 earnings beat helped by a rebound in alumina. On the other side, CoreWeave is down about 4% as rising borrowing costs squeeze the most indebted AI-infrastructure names, Travelers is off about 4% despite beating, and Netflix slips about 1.5% on a leadership shake-up. Reward is concentrated in value and specific catalysts; the debt-heavy AI names stay under pressure.
- It’s a heavy morning for data, earnings and the Fed. Import and export prices hit at 8:30 AM ET, with industrial production and capacity utilization at 9:15. Financials dominate the earnings slate — SLB, Truist, Regions, Citizens and M&T all report, making the regional banks a live read on how 5% rates are hitting margins and credit. And Fed Chair Warsh speaks in a fireside chat at the IMF meetings, with Cleveland’s Hammack also on the calendar; Warsh has declined to pre-commit on the next move, keeping October and December live. Any of these can swing the morning — let the reactions settle before you lean on a direction.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,780 — the record-chase wall. This is the level the index has to clear and hold to say the breakout toward new highs is genuinely back on, not just a relief bounce fading into resistance. It sits above Thursday’s 7,744.06 close, right in the zone of last week’s all-time high, so expect sellers to lean here on the first test. Don’t chase a gap into 7,780 on an oversold-to-overbought open — make the market prove it can hold above the prior record on real volume with the 10-year behaving. A record run that stalls at the wall while yields push back toward 5.15% is exactly where breakout-chasers get trapped. Earn the long; don’t predict it.
- SPX 7,700 — the pivot that held all week. This is the bull/bear line the index defended through the whole inflation scare, sitting just under Thursday’s close, and it’s the whole trade today: hold above 7,700 on real volume and the value-led structure stays intact; lose it and fail to reclaim and the rebound is unraveling. On a rotation tape the index can grind sideways while value rises and tech idles, so trust a break of this level only with volume behind it — a flush that snaps back inside is noise. The real signal is which side SPX leaves 7,700 on once the 8:30 data and the bank-earnings reactions clear.
- SPX 7,615 — the deeper floor. The must-hold support below the pivot and the level that decides whether a loss of 7,700 is a quick shakeout or the start of a real repricing. If yields reverse higher through 5.15% and the value bid fails, 7,615 is where dip buyers have to step up to keep the larger structure intact. Lose 7,615 and the tape is no longer ‘value leads, tech idles’ — it’s ‘rates break the whole market,’ and that’s a heavier game driven by the 10-year, not by sector rotation. Mark it, respect it, and let price confirm. Don’t guess the bottom; let the level tell you whether the weakness is a dip or a trend change.
Premarket Movers
Gainers
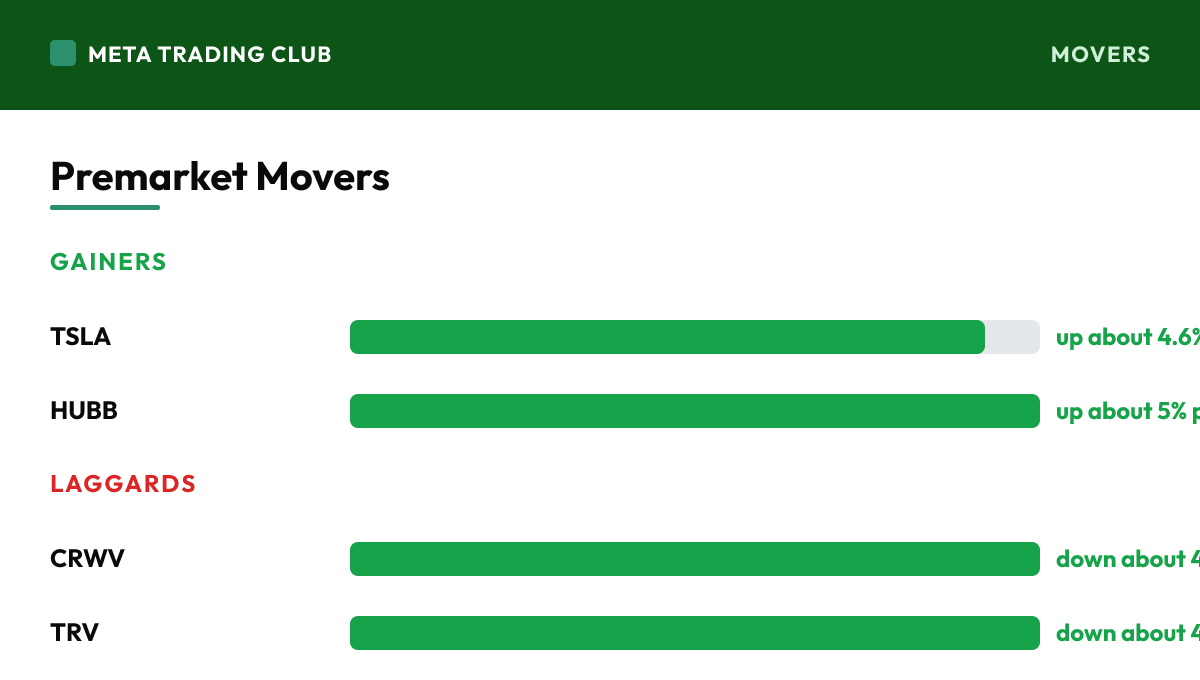
| TSLA | Tesla | up about 4.6% premarket after unveiling its second-generation Roadster | Up about 4.6% this morning after Thursday’s unveil of the second-generation Roadster — complete with SpaceX-developed rocket-style thrusters and aerial maneuvers at the event, with production targeted for 2028. This is a catalyst-driven move, not a tape move: Tesla is rising on its own news while the broader growth complex stays capped by rates. Treat it as a single-stock story and trade it on its own levels — a hype-fueled gap can give back fast, so let the stock prove the move holds rather than chasing the headline into the open. Catalyst pops reward patience, not reflexes. |
| HUBB | Hubbell | up about 5% premarket, leading gainers as value-and-industrial names catch the bid | Leading the premarket gainers near +5% as the market keeps rewarding industrial and value names in a 5% yield world. Hubbell fits the day’s shape perfectly — a cash-generating, old-economy electrical name benefiting from the same rotation that drove Thursday’s Dow rally while high-multiple tech idles. Read it as confirmation of where capital wants to be right now: paying up for cash flow today rather than growth tomorrow. Don’t chase the pop; use it as a tell for the value leadership, and let the broad-tape levels, not the single move, drive your actual trade. |
Laggards
| CRWV | CoreWeave | down about 4% premarket as rising borrowing costs squeeze the most indebted AI name | Down about 4% this morning as the clearest symbol of what 5% rates are doing to the AI build-out. CoreWeave is a heavily indebted data-center operator, and with the 10-year above 5% the market keeps questioning how that build-out gets paid for. This is the lesson of the tape in one name: the AI selloff isn’t about whether the chips are in demand, it’s about how the infrastructure gets financed when borrowing costs stay high. Trade it on its own levels and treat it as the tell for the whole debt-heavy AI complex — when the most leveraged name stays heavy, the group can’t lead. |
| TRV | Travelers | down about 4% premarket despite a Q3 beat | Off about 4% this morning even though the headline numbers beat — core Q3 EPS of $9.18 on $12.48B revenue topped the $7.42 estimate handily. The move is the lesson: in this tape, a beat alone doesn’t earn a bid when investors are focused on what’s underneath, from underwriting trends to reserve adequacy. Don’t trade the headline EPS; trade the reaction. Travelers reacting lower on a beat is a reminder to wait for the market to tell you how it’s reading the print rather than assuming a beat means up. The tape prices the quality of earnings, not just the number. |
Risks Into the Open
- Primary risk today: treating one green day as the all-clear. Thursday’s 556-point Dow rally felt like the scare was over, and the reflex is to pile back into the names that got hit. But the overhang hasn’t moved — the 10-year is still above 5%, and a relief rally during a high-rate backdrop traps the people who chase it. The discipline is to let SPX hold 7,700 and reclaim 7,780 before you trust the record chase. A bounce isn’t a trend until the level holds, and a big candle during a rate problem is a reaction, not a resolution.
- The structural risk is the 10-year reversing higher. Right now value leads, the Dow is green, and the VIX has cooled to 16.46 — a tape at peace with higher-for-longer. But that peace is contingent on yields staying put. If this morning’s import/export prices or industrial production run hot, or Warsh sounds hawkish at the IMF, a push toward 5.15%-plus would tighten the screws on tech and small caps fast and flip the calm to caution. Watch the 10-year and the VIX together as the live referees — steady yields and a pinned VIX keep the rebound alive; rising yields and a VIX back above 18 change the game.
- The company-specific risk is trading headline earnings instead of the reaction. Travelers beat and fell about 4%; a beat alone isn’t a bid in this tape. With SLB, Truist, Regions, Citizens and M&T all reporting, the trap is assuming a good number means a good trade. Price each name on its own print, read the credit and margin commentary from the regionals as the real signal on 5% rates, and size for the reaction, not the narrative. Let the market tell you how it’s reading the quality of earnings before you commit. Confirmation over conviction, every time.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Friday, October 16, 2026, S&P 500 futures are at 7,744.06 (+0.3%), with the VIX near 16.46. The stock market today opens with a split personality — and that split is the whole read. Thursday the Dow ripped 556 points (+1.1%) to 52,177.69 as the AI jitters from earlier in the week faded, while the Nasdaq Composite barely moved, up just 0.1% to 26,713.03, and the S&P 500 added 0.3% to 7,744.06. This morning the same shape holds: Dow futures lead green, up about 0.41%, S&P 500 futures are modestly higher around +0.19%, and Nasdaq futures sit essentially flat, down about 0.06%. The story behind the split is rates. A hot inflation week — September PPI jumped 1.3% month over month (6.3% year over year) and core CPI firmed to 2.6% — has pushed the 10-year Treasury yield above 5%, now near 5.08%, and that is the lid keeping growth and the most rate-sensitive AI names capped even on an up day. Money keeps favoring old-economy and value over high-multiple tech. Tesla is the standout mover, up about 4.6% premarket after unveiling its second-generation Roadster, while Hubbell leads gainers around +5%. The other side of the tape: CoreWeave is down about 4% as rising borrowing costs squeeze the most indebted AI-infrastructure names, Travelers is off about 4% despite beating, and Netflix slips about 1.5% on a leadership shake-up. VIX has cooled to 16.46, down about 2.4%, WTI is softer near $95.84, and Bitcoin is recovering near $82,000 but still set for a second straight down week. It’s a heavy morning for financials: SLB, Truist, Regions, Citizens and M&T all report, making the regional banks a live read on what 5% rates are doing to the group. Data lands too — import/export prices at 8:30, industrial production and capacity utilization at 9:15 — and Fed Chair Warsh speaks in a fireside chat at the IMF meetings. Mark SPX 7,700 as the pivot the index held all week, 7,780 as the record-chase wall it still has to clear, and 7,615 as the deeper floor. The scorecard so far: the Dow reclaimed its lead, but a 5% 10-year keeps the lid on the record chase. A bounce isn’t a trend until the level holds. No alignment, no trade.
What is the biggest catalyst for the market today?
Rates are running the tape, and the split futures prove it. Dow futures lead up about 0.41% while Nasdaq futures sit flat, down about 0.06% — the same value-over-growth shape that drove Thursday’s 556-point Dow rally. The reason is the 10-year near 5.08% after a hot inflation week: September PPI jumped 1.3% month over month (6.3% y/y) and core CPI firmed to 2.6%, repricing the rate path higher for longer. As long as the 10-year holds above 5%, the market keeps paying up for cash-generating value and capping high-multiple tech. This isn’t a demand story — it’s a discount-rate story.
What key levels should traders watch today?
SPX 7,780 — the record-chase wall. This is the level the index has to clear and hold to say the breakout toward new highs is genuinely back on, not just a relief bounce fading into resistance. It sits above Thursday’s 7,744.06 close, right in the zone of last week’s all-time high, so expect sellers to lean here on the first test. Don’t chase a gap into 7,780 on an oversold-to-overbought open — make the market prove it can hold above the prior record on real volume with the 10-year behaving. A record run that stalls at the wall while yields push back toward 5.15% is exactly where breakout-chasers get trapped. Earn the long; don’t predict it. SPX 7,700 — the pivot that held all week. This is the bull/bear line the index defended through the whole inflation scare, sitting just under Thursday’s close, and it’s the whole trade today: hold above 7,700 on real volume and the value-led structure stays intact; lose it and fail to reclaim and the rebound is unraveling. On a rotation tape the index can grind sideways while value rises and tech idles, so trust a break of this level only with volume behind it — a flush that snaps back inside is noise. The real signal is which side SPX leaves 7,700 on once the 8:30 data and the bank-earnings reactions clear. SPX 7,615 — the deeper floor. The must-hold support below the pivot and the level that decides whether a loss of 7,700 is a quick shakeout or the start of a real repricing. If yields reverse higher through 5.15% and the value bid fails, 7,615 is where dip buyers have to step up to keep the larger structure intact. Lose 7,615 and the tape is no longer ‘value leads, tech idles’ — it’s ‘rates break the whole market,’ and that’s a heavier game driven by the 10-year, not by sector rotation. Mark it, respect it, and let price confirm. Don’t guess the bottom; let the level tell you whether the weakness is a dip or a trend change.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – October 16, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.