Wednesday, October 14, 2026 · 8:45 AM ET · MTC Market Intelligence
The stock market today opens on a reaction day — and the reaction that matters already happened. September CPI landed at 8:30 AM hotter than the street wanted — 3.7% headline versus 3.6% expected and up from 3.4% in August, with core at 2.6%. On paper that’s a problem: hot inflation usually pressures stocks and lifts yields. Instead, futures are holding modestly green — Dow futures up about 0.3%, S&P 500 futures up about 0.1%, Nasdaq-100 futures roughly flat to slightly lower — and the 10-year is actually easing to about 5.19%, its second straight day lower. That gap between the scary headline and the calm tape is the whole story: the market is betting the Fed stays patient, with roughly 80% odds of no change at the October meeting still priced in. Prior session was quiet — the S&P 500 closed Tuesday essentially flat at 7,805.45, the Dow slipped 0.35% to 51,670.10, and the Nasdaq Composite eased 0.15% to 27,204.38 as memory chips stayed heavy. This morning the bank scorecard is mixed and the reactions tell the tale: Bank of America is down about 4% after a sharp profit drop tied to a $1.2B Treasury penalty, BlackRock is up about 3% on a clean beat, and Morgan Stanley reports into the open. Chips are soft again — ASML slipped about 1% on a slight sales miss even as it raised its full-year outlook, and Micron is fractionally lower. WTI is firm near $94.7 on Saudi-Houthi supply worries, the VIX sits calm near 15.3, and Bitcoin is heavy near $83,400, still capped under $84K. Mark SPX 7,800 as the shelf the index has to hold, 7,850 as the wall above, and 7,750 as the deeper support. The lesson today writes itself: a hot number that doesn’t sell off is the market telling you what it already knows. Don’t trade the headline — trade what price does with it. No alignment, no trade.
Market Snapshot
| Instrument | Level | Change | Note |
|---|---|---|---|
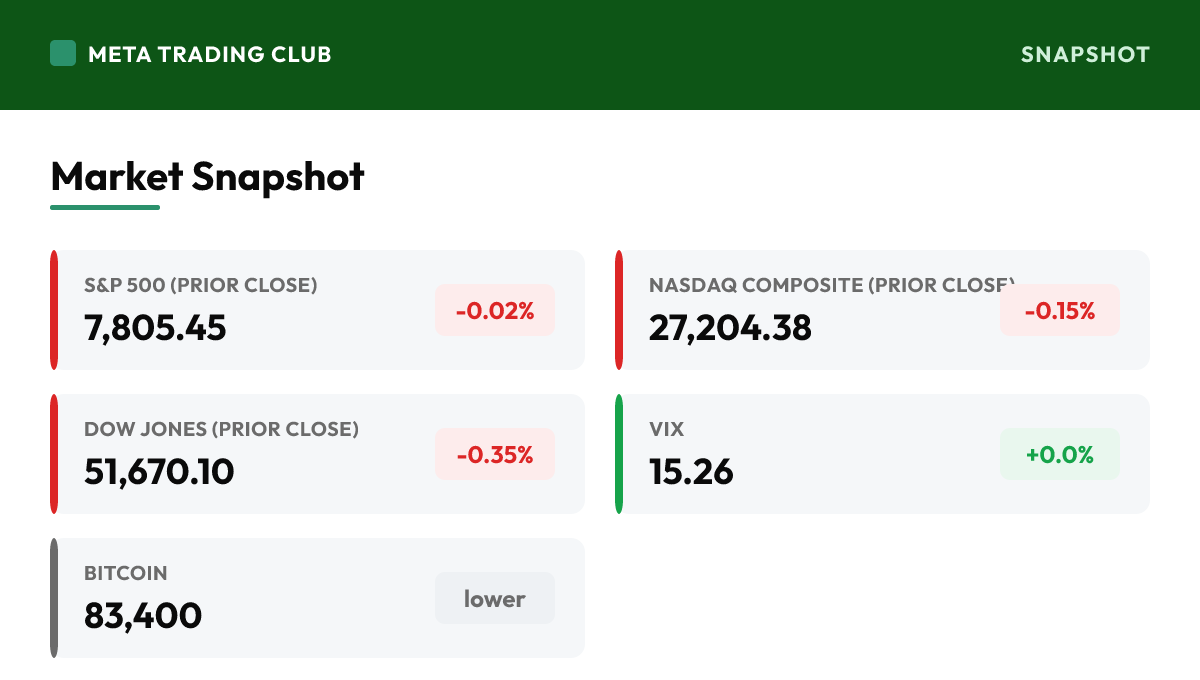
| S&P 500 (prior close) | 7,805.45 | -0.02% | Closed Tuesday essentially flat at 7,805.45, holding just under its record as quiet rotation offset heavy memory chips. This morning S&P 500 futures are up about 0.1% even after a hot CPI print — the tell that the market is treating 3.7% inflation as already known, not a fresh shock. The level that matters is 7,800: the round-number shelf right at Tuesday’s close. Hold it on real volume once the CPI reaction settles and the record stays intact; lose it and fail to reclaim and the hot print is winning the tape. |
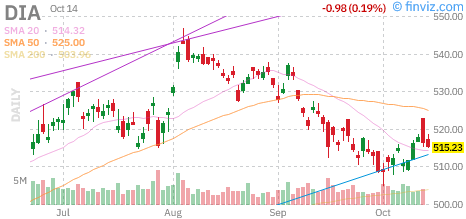
| Dow Jones (prior close) | 51,670.10 | -0.35% | Slipped 0.35% Tuesday to 51,670.10, down about 180 points on soft bank reactions. This morning Dow futures lead the majors, up about 0.3%, helped by BlackRock’s beat even as Bank of America drags on a $1.2B Treasury penalty. The Dow is the strongest of the three this morning — a financials-led bid that sticks keeps the index firm; one that fades says the earnings strength isn’t broad. |
| Nasdaq Composite (prior close) | 27,204.38 | -0.15% | Eased 0.15% Tuesday to 27,204.38 as memory names stayed under pressure after an overnight slide in South Korean chips. This morning Nasdaq-100 futures are roughly flat to slightly lower — ASML’s slight sales miss and continued softness in Micron keep the complex heavy. Tech is the laggard again: if chips stabilize the Nasdaq holds, if they roll the index drags the broad tape. |
| Russell 2000 (prior close) | — | N/A | Small-cap futures are up about 0.3% this morning, tracking the Dow higher. With the 10-year easing to about 5.19%, the rate-sensitive small caps get a small tailwind — watch whether they can lead a broad move or just drift with the majors. Breadth from the Russell joining the banks would make any push higher more credible. |
| VIX | 15.26 | +0.0% | Sitting calm near 15.3, firmly in low-volatility territory. A sub-16 VIX on a CPI morning is the clearest single tell that the market is not braced for a shock — it’s pricing a patient Fed and a tape that absorbs the hot print. Watch for a spike through 17 if the CPI reaction turns: rising vol into the open would say the calm is cracking. |
| WTI Crude | 94.71 | +0.6% | Firm near $94.7, up about 0.6% on supply worries as hostilities escalate between Saudi Arabia and Yemen’s Houthi rebels. Oil holding this high keeps a floor under headline inflation — the exact kind of sticky-energy backdrop that makes a hot CPI print harder to dismiss. Energy strength is a quiet cross-check on the inflation story. |
| 10-Yr Treasury | 5.194% | lower | Eased to about 5.194%, its second straight day lower, even as CPI ran hot. That’s the single most important tell on the tape: if inflation were the real threat today, yields would be rising, not falling. Bonds easing into a hot print says the market believes the Fed holds and looks through the number. Watch the 10-year closely — a reversal higher would flip the whole read. |
| Bitcoin | 83,400 | lower | Heavy near $83,400, still capped under the $83,600-$84,000 resistance zone after a leveraged flush. Crypto trading soft into the CPI print is a small risk-appetite tell — a clean break back above $84K would say risk is firming, while a slide under $82K would flag caution bleeding across risk assets. |
Charts to Watch
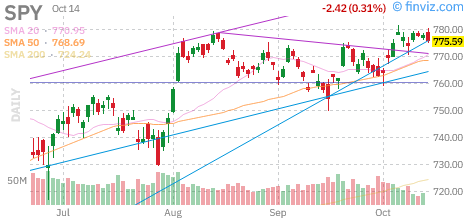
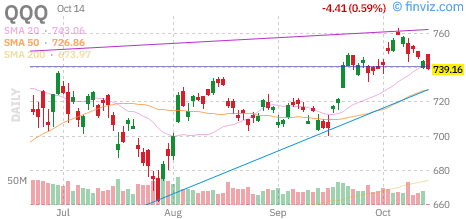
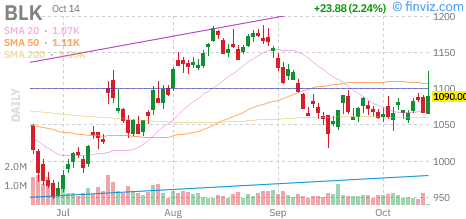
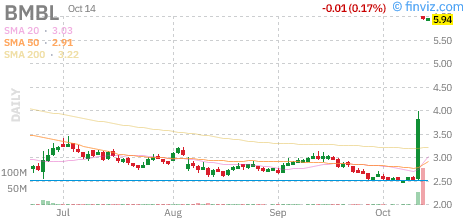
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
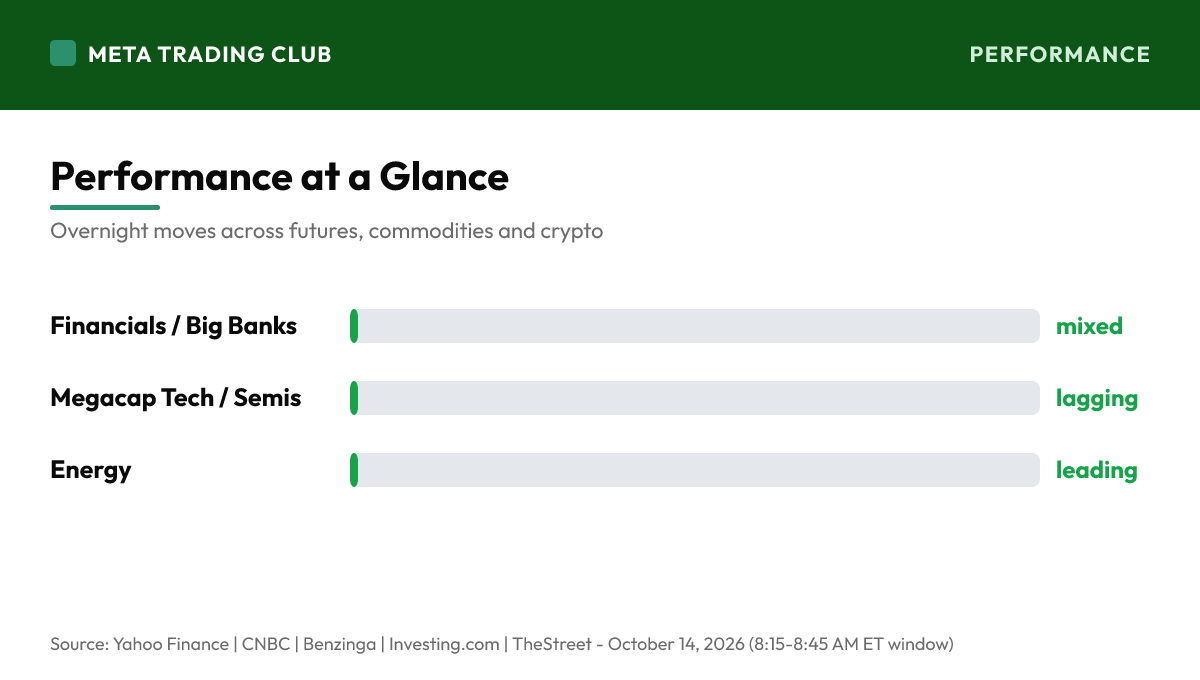
Overnight & Global Markets
Tuesday was quiet and set up a reaction day. The S&P 500 closed flat at 7,805.45, the Dow slipped 0.35% to 51,670.10, and the Nasdaq Composite eased 0.15% to 27,204.38 as memory chips stayed heavy on an overnight South Korean slide. The real event landed this morning at 8:30: September CPI at 3.7% headline, hotter than the 3.6% expected and up from 3.4%, with core at 2.6%. The textbook reaction to hot inflation is lower stocks and higher yields — and the tape did the opposite. Dow futures are up about 0.3%, S&P 500 futures up about 0.1%, Nasdaq-100 futures roughly flat, and the 10-year is easing to about 5.19% for a second day. That divergence is the information: the market is treating 3.7% as already priced and is betting on a patient Fed, with about 80% odds of no October change intact. Bank earnings add a mixed overlay — Bank of America is off about 4% on a profit drop tied to a $1.2B Treasury penalty, BlackRock is up about 3% on a clean beat, and Morgan Stanley reports into the open. Chips stay soft, with ASML down about 1% on a slight sales miss despite raising its full-year outlook. WTI is firm near $94.7 on Saudi-Houthi supply worries, the VIX is calm near 15.3, and Bitcoin is heavy near $83,400. Mark SPX 7,800 as the shelf, 7,850 as the wall above, and 7,750 as the deeper floor. Let the reaction settle before you commit — a hot number that doesn’t sell off is the market telling you what it already knows. No alignment, no trade.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- September CPI is the whole morning. The headline landed at 8:30 AM at 3.7% year-over-year, hotter than the 3.6% expected and up from 3.4% in August, with core CPI at 2.6% versus 2.4% prior. Hot inflation normally pressures stocks and lifts yields — and the tape did the opposite. Dow futures are up about 0.3%, S&P 500 futures up about 0.1%, Nasdaq-100 futures roughly flat, and the 10-year is easing to about 5.19% for a second straight day. That gap between a scary number and a calm reaction is the signal: the market is treating 3.7% as already priced and is betting on a patient Fed, with roughly 80% odds of no change at the October meeting still intact.
- Bank earnings are the second thread, and the reactions are split. Bank of America is down about 4% after a sharp third-quarter profit decline tied to a $1.2B penalty from the U.S. Treasury over money-laundering violations — a company-specific hit, not a sector signal. BlackRock is up about 3% on an earnings and revenue beat, and Morgan Stanley reports into the open. The lesson is the same one the tape teaches every earnings season: trade the reaction, not the headline. A big bank falling on a penalty and an asset manager rising on a beat are two different stories, and the market is pricing each on its own facts.
- Chips stay soft and the Fed’s Beige Book lands this afternoon. ASML slipped about 1% on a slight Q3 sales miss even as it raised its full-year sales outlook for the third time this year, and Micron is fractionally lower, extending memory-chip weakness that began with an overnight slide in South Korea. Later today the Fed’s Beige Book gives a fresh read on regional economic conditions into the October meeting. With CPI already out, the afternoon Fed color and the chip reactions are the two things that can still move the afternoon tape.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,850 — the wall above. The next round number over Tuesday’s 7,805.45 close and the level the index has to clear to prove the hot-CPI shrug is turning into a real push higher. A break and hold here, powered by broad breadth — banks beyond BlackRock, small caps joining, chips absorbed — is the tape saying the market is comfortable looking through the inflation print and the record run has room. But don’t chase into 7,850 on a CPI-reaction open. Make the market defend 7,800 first and earn this wall on real volume once the earnings and inflation reactions settle; a record stalling at the next wall while chips slide is exactly where chasers get trapped.
- SPX 7,800 — the shelf and the line in the sand. The round-number floor right at Tuesday’s close that the index has to defend to keep the run valid through a hot CPI print. This is the whole trade today: hold above 7,800 on real volume and the market’s ‘look-through’ read on inflation holds; lose it and fail to reclaim and the hot number is winning the tape after all. On a reaction day the index can sit quiet while banks and chips pull in opposite directions, so trust a break of this level only with volume behind it — a gap that fades back inside is noise. The real signal is which side SPX leaves 7,800 on once the CPI dust settles.
- SPX 7,750 — the deeper support. The floor below the shelf and the level that decides whether a 7,800 loss is a quick shakeout or the start of something real. If the hot CPI reaction turns and the 10-year reverses higher, 7,750 is where dip buyers have to show up to keep the structure intact. Lose 7,750 with yields climbing and you’re no longer in a ‘market shrugs off inflation’ tape — you’re in a ‘market finally reprices the Fed’ tape, and that’s a different, heavier game. Mark it, respect it, and let it tell you whether weakness is noise or a regime change. Don’t guess the bottom; let price confirm.
Premarket Movers
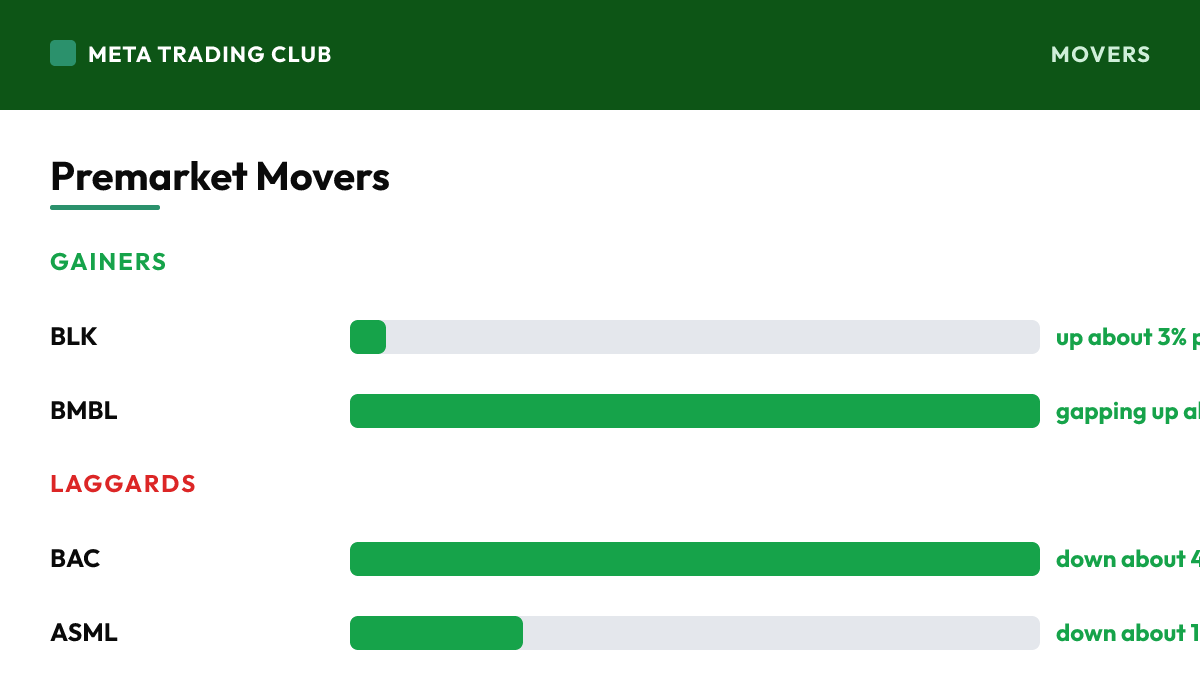
Gainers
| BLK | BlackRock | up about 3% premarket on an earnings and revenue beat; leading the morning reactions | Up about 3% this morning after a clean earnings and revenue beat, the standout of the bank-and-asset-manager reactions and the main leg under the Dow’s premarket strength. BlackRock is a read on whether the money-management engine and fee flows are holding up, and a 3% pop says the market liked the print. Trade it on its own levels and treat it as a tell for financials breadth: a beat that holds through the session keeps the Dow firm and the rotation credible, while a fade into the open says the strength is narrow and name-specific. For now, BlackRock is the leg the financials bid is standing on. |
| BMBL | Bumble | gapping up about 57% on a $1.3B take-private deal | Gapping up about 57% premarket on a reported $1.3B take-private deal with Ithaca Holdings — a deal-driven move, not an operating-results move. When a stock jumps on an acquisition, the gap is pricing the deal terms, so the trade is about the spread to the offer and deal risk, not momentum. Don’t treat a buyout pop like a breakout; the easy money is already in the price, and what’s left is the arbitrage and the risk the deal falls through. A name like this is a headline, not a setup — note it, understand why it moved, and keep your focus on the tape that actually trades on structure. |
Laggards
| BAC | Bank of America | down about 4% premarket on a sharp profit drop tied to a $1.2B Treasury penalty | Down about 4% this morning after a sharp Q3 profit decline tied to a $1.2B penalty from the U.S. Treasury over money-laundering violations. This is a company-specific hit, not a sector signal — which is exactly why it’s a teaching moment. A big bank falling on a one-time penalty while BlackRock rises on a beat tells you to price each name on its own facts, not on a ‘banks are weak’ narrative. Trade BAC on its own levels and don’t let one penalty-driven drop color your read on the whole financial sector. The reaction is the information: the market is punishing the penalty, not the franchise. |
| ASML | ASML Holding | down about 1% premarket on a slight Q3 sales miss despite raising its full-year outlook | Off about 1% this morning on a slight Q3 net-sales miss, even though the company raised its full-year sales outlook for the third time this year. That split — strong guidance, soft print — is a classic reaction puzzle, and the premarket dip says the market is focused on the near-term miss over the longer-term raise. ASML is the gatekeeper of advanced chip manufacturing, so it’s a key tell for the whole semi complex. Trade it on its own levels and read it alongside Micron as one group: broad chip softness holding into the open says the Nasdaq stays heavy, while a stabilization says the dip was a shakeout. Let price confirm before you lean either way. |
Risks Into the Open
- Primary risk today: trusting the calm too early. CPI ran hot at 3.7% and the tape shrugged — futures green, yields easing. That’s a real signal, but a CPI reaction can take hours to fully express, and the first move is often not the lasting one. The discipline is to let the market defend 7,800 and let the 10-year confirm the ‘look-through’ read before you size up. If yields reverse higher through the morning, the shrug flips to a reprice fast. Trade what the tape actually does with the number as the session develops, not the relief you feel in the first fifteen minutes.
- The structural risk is the inflation-vs-Fed tension the hot print just sharpened. Markets are pricing roughly 80% odds of no October change, and that consensus is doing a lot of work to keep the tape calm. A 3.7% headline with core firming to 2.6% is the kind of data that, if it continues, forces the Fed’s hand and reprices the whole rate path. Today the market is betting that doesn’t happen — but a narrow bet on a patient Fed is a fragile base if the next print also runs hot. Watch the 10-year as the live referee on whether that bet is holding.
- The company-specific risk is reading one name as the whole sector. Bank of America is down about 4% on a $1.2B Treasury penalty — a one-off, not a franchise problem — while BlackRock rises on a beat. On an earnings-heavy morning the trap is letting one dramatic reaction set your bias for an entire group. Price each name on its own facts, size for the reaction not the headline, and keep the chip complex on a separate line of the risk ledger from the banks. Confirmation over conviction, every time.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Wednesday, October 14, 2026, S&P 500 futures are at 7,805.45 (-0.02%), with the VIX near 15.26. The stock market today opens on a reaction day — and the reaction that matters already happened. September CPI landed at 8:30 AM hotter than the street wanted — 3.7% headline versus 3.6% expected and up from 3.4% in August, with core at 2.6%. On paper that’s a problem: hot inflation usually pressures stocks and lifts yields. Instead, futures are holding modestly green — Dow futures up about 0.3%, S&P 500 futures up about 0.1%, Nasdaq-100 futures roughly flat to slightly lower — and the 10-year is actually easing to about 5.19%, its second straight day lower. That gap between the scary headline and the calm tape is the whole story: the market is betting the Fed stays patient, with roughly 80% odds of no change at the October meeting still priced in. Prior session was quiet — the S&P 500 closed Tuesday essentially flat at 7,805.45, the Dow slipped 0.35% to 51,670.10, and the Nasdaq Composite eased 0.15% to 27,204.38 as memory chips stayed heavy. This morning the bank scorecard is mixed and the reactions tell the tale: Bank of America is down about 4% after a sharp profit drop tied to a $1.2B Treasury penalty, BlackRock is up about 3% on a clean beat, and Morgan Stanley reports into the open. Chips are soft again — ASML slipped about 1% on a slight sales miss even as it raised its full-year outlook, and Micron is fractionally lower. WTI is firm near $94.7 on Saudi-Houthi supply worries, the VIX sits calm near 15.3, and Bitcoin is heavy near $83,400, still capped under $84K. Mark SPX 7,800 as the shelf the index has to hold, 7,850 as the wall above, and 7,750 as the deeper support. The lesson today writes itself: a hot number that doesn’t sell off is the market telling you what it already knows. Don’t trade the headline — trade what price does with it. No alignment, no trade.
What is the biggest catalyst for the market today?
September CPI is the whole morning. The headline landed at 8:30 AM at 3.7% year-over-year, hotter than the 3.6% expected and up from 3.4% in August, with core CPI at 2.6% versus 2.4% prior. Hot inflation normally pressures stocks and lifts yields — and the tape did the opposite. Dow futures are up about 0.3%, S&P 500 futures up about 0.1%, Nasdaq-100 futures roughly flat, and the 10-year is easing to about 5.19% for a second straight day. That gap between a scary number and a calm reaction is the signal: the market is treating 3.7% as already priced and is betting on a patient Fed, with roughly 80% odds of no change at the October meeting still intact.
What key levels should traders watch today?
SPX 7,850 — the wall above. The next round number over Tuesday’s 7,805.45 close and the level the index has to clear to prove the hot-CPI shrug is turning into a real push higher. A break and hold here, powered by broad breadth — banks beyond BlackRock, small caps joining, chips absorbed — is the tape saying the market is comfortable looking through the inflation print and the record run has room. But don’t chase into 7,850 on a CPI-reaction open. Make the market defend 7,800 first and earn this wall on real volume once the earnings and inflation reactions settle; a record stalling at the next wall while chips slide is exactly where chasers get trapped. SPX 7,800 — the shelf and the line in the sand. The round-number floor right at Tuesday’s close that the index has to defend to keep the run valid through a hot CPI print. This is the whole trade today: hold above 7,800 on real volume and the market’s ‘look-through’ read on inflation holds; lose it and fail to reclaim and the hot number is winning the tape after all. On a reaction day the index can sit quiet while banks and chips pull in opposite directions, so trust a break of this level only with volume behind it — a gap that fades back inside is noise. The real signal is which side SPX leaves 7,800 on once the CPI dust settles. SPX 7,750 — the deeper support. The floor below the shelf and the level that decides whether a 7,800 loss is a quick shakeout or the start of something real. If the hot CPI reaction turns and the 10-year reverses higher, 7,750 is where dip buyers have to show up to keep the structure intact. Lose 7,750 with yields climbing and you’re no longer in a ‘market shrugs off inflation’ tape — you’re in a ‘market finally reprices the Fed’ tape, and that’s a different, heavier game. Mark it, respect it, and let it tell you whether weakness is noise or a regime change. Don’t guess the bottom; let price confirm.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – October 14, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.