Monday, November 2, 2026 · 8:06 AM ET · Shahryar Rahmani, MTC Desk
Oil drops under $100 (about −4% at 7:53 AM ET) and stock futures are higher this morning after last week’s sell-off. The day turns on the 10:00 AM ISM Manufacturing report (consensus 54.7) and Apple and Palantir earnings after the close. Until SPY is back above Friday’s high, we read this as a bounce, not a new leg up.
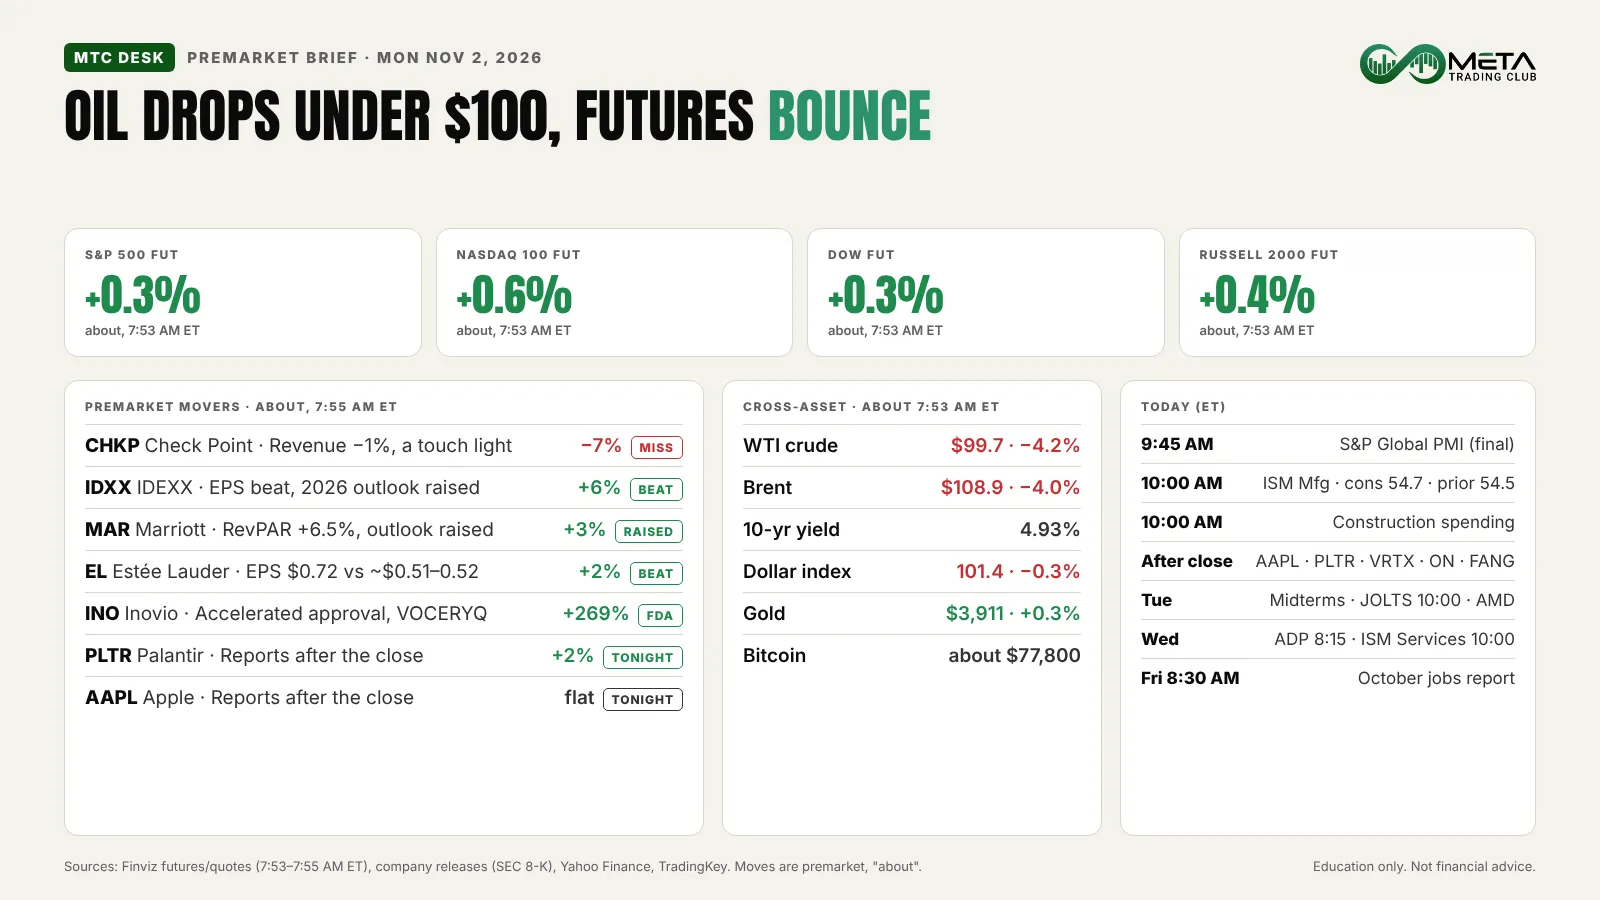
S&P 500 futures were up about 0.3% and Nasdaq 100 futures about 0.6% at 7:53 AM ET, a calm start after a rough Friday. The S&P 500 fell 1.82% on Friday and the Nasdaq dropped 2.86%, closing out an October in which the Nasdaq 100 lost about 6.5%, its worst month since March 2025 (Yahoo Finance).
The biggest overnight change is in oil. WTI crude fell about 4% to roughly $99.7 and Brent to about $108.9 by 7:53 AM ET, on easing supply fears and hopes for more time for U.S.-Iran diplomacy. Cheaper oil takes some pressure off inflation, and the 10-year Treasury yield eased to about 4.93%.
Earnings did the rest. As of 7:55 AM ET, IDEXX (about +6%) and Marriott (about +3%) were higher after raising their outlooks, while Check Point (about −7%) said its recovery is taking longer than expected.
The rest of the week is crowded: the midterm elections on Tuesday and the October jobs report on Friday. Read our guide to using premarket data to prepare for the day for how we turn these numbers into a plan.
Market Snapshot
| Market | Level / move | Note |
|---|---|---|
| S&P 500 futures | about +0.3% | 7:53 AM ET; Friday cash close 7,580.07 (−1.82%) |
| Nasdaq 100 futures | about +0.6% | Tech leads the bounce after October’s drop |
| Dow futures | about +0.3% | 7:53 AM ET |
| Russell 2000 futures | about +0.4% | Small caps follow the bounce |
| SPY premarket | 758.48 (about +0.4%) | 7:55 AM ET; Friday close 755.72 |
| QQQ premarket | 694.88 (about +0.6%) | 7:55 AM ET; Friday close 690.49 |
Top Premarket Stories
Moves are premarket, as of about 7:55 AM ET (Finviz).
Check Point Software (CHKP), about −7%. Third-quarter revenue was $669.8 million, down 1% from a year ago and a touch below the roughly $672 million analysts expected. Non-GAAP EPS of $2.49 was in line. The CEO said the company expects gradual improvement starting in the fourth quarter, after a recovery that is taking longer than planned (company release; Globes).
IDEXX Laboratories (IDXX), about +6%. Revenue rose 10% to $1.214 billion and comparable EPS jumped 22% to $3.96, ahead of the roughly $3.81 analysts expected (Current Logic). IDEXX raised its 2026 EPS outlook to $14.96–$15.16 from $14.69–$14.94 (SEC 8-K).
Marriott (MAR), about +3%. Worldwide RevPAR (revenue per available room, the hotel industry’s key number) rose 6.5%, with U.S. & Canada up 7.4%. Adjusted EPS was $3.02, up 22%, and Marriott raised its 2026 global RevPAR outlook to 4.5%–5% growth (SEC 8-K).
Estée Lauder (EL), about +2%. Fiscal first-quarter sales rose 7% to $3.72 billion, and adjusted EPS of $0.72 beat the roughly $0.51–$0.52 expected. The company raised its fiscal 2027 outlook, now calling for 4%–5.5% organic sales growth and adjusted EPS of $3.20–$3.45 (Grafa; Rallies).
Inovio (INO) more than tripled to about $2.20 after the FDA granted accelerated approval on October 30 for VOCERYQ, its treatment for adults with recurrent respiratory papillomatosis, a rare airway disease (SEC 8-K). Moves like this in a low-priced stock come with wide spreads and fast reversals.
Sectors
Technology leads the early bounce, with memory chips higher after Korea’s October chip exports jumped (Current Logic): Micron was up about 2% at 7:55 AM ET. Energy names face the drop in crude. All 11 sectors get a full scoreboard in tonight’s close recap.
Rates, Dollar and Commodities: Oil Drops Under $100
| Asset | About 7:53 AM ET | One line |
|---|---|---|
| 10-year yield | 4.93% | Slightly lower with oil |
| Dollar index | 101.4 (−0.3%) | Softer dollar |
| WTI crude | $99.7 (−4.2%) | Back under $100 on Iran diplomacy hopes |
| Brent crude | $108.9 (−4.0%) | Same story |
| Gold | $3,911 (+0.3%) | Still under $4,000 |
| Bitcoin | about $77,800 | Near $78K |
Economic Data Today
| Time (ET) | Release | Consensus | Prior | Actual |
|---|---|---|---|---|
| 9:45 AM | S&P Global Manufacturing PMI (Oct, final) | — | — | 54.9 |
| 10:00 AM | ISM Manufacturing PMI (Oct) | 54.7 | 54.5 | 55.5 |
| 10:00 AM | Construction spending (Sep) | — | — | -1.9% |
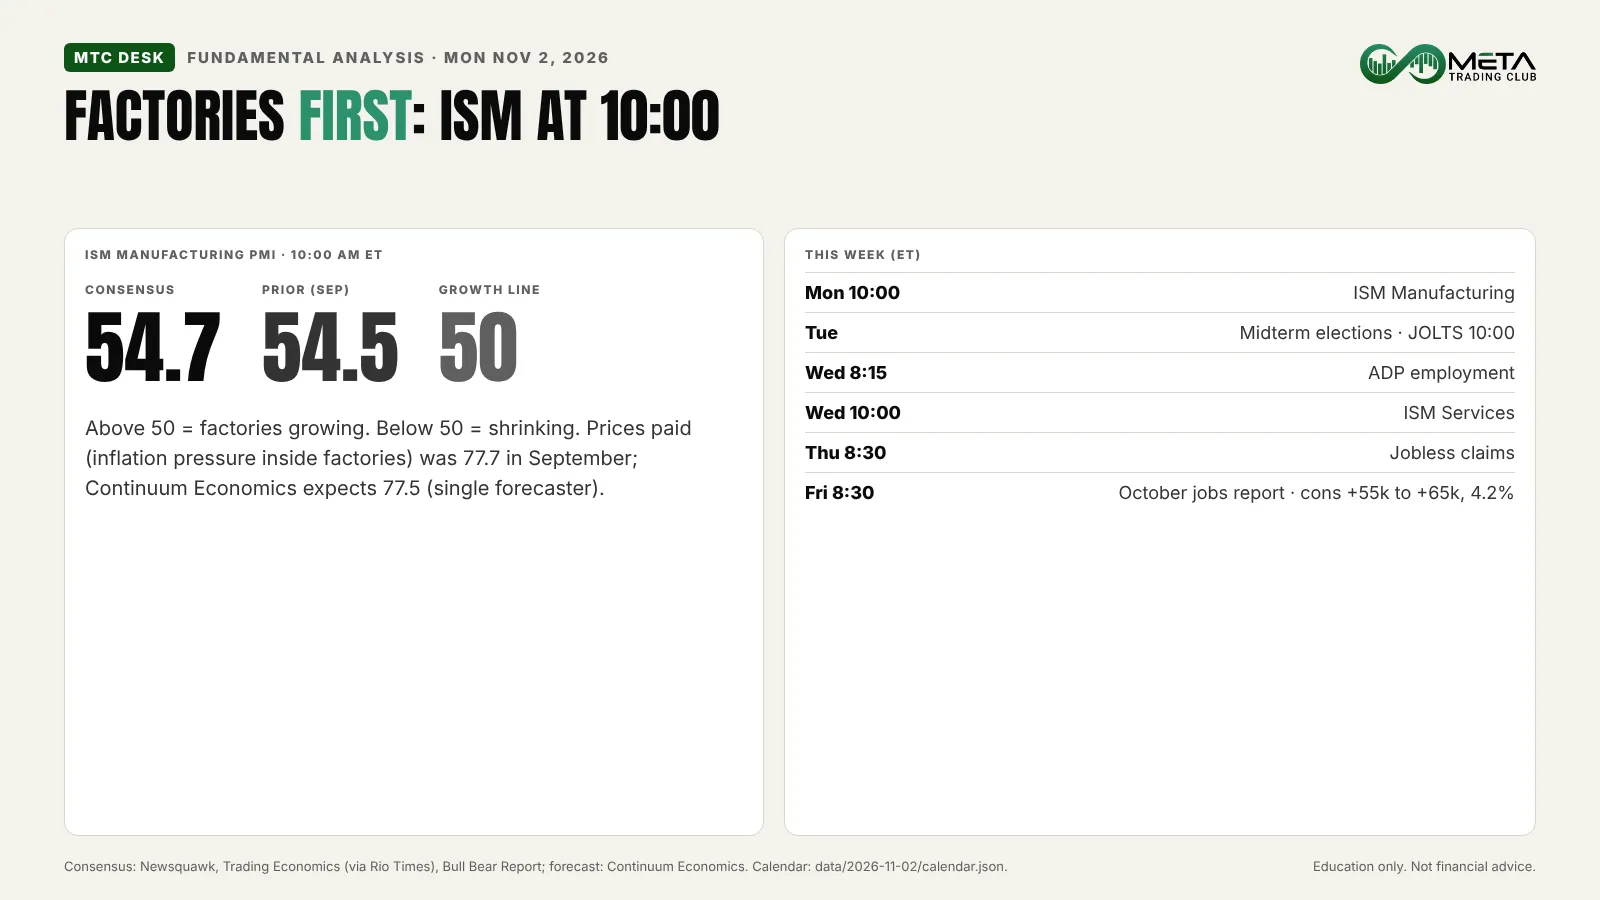
ISM Manufacturing is a survey of factory purchasing managers: above 50 means activity is growing. Continuum Economics expects no change at 54.5. The line to watch is prices paid, 77.7 in September (Continuum Economics expects 77.5); a hot number usually lifts yields. Our explainer on how inflation reports move the stock market covers why. No Fed speakers are confirmed for today.
Earnings
Before the open: Check Point, IDEXX, Marriott, Estée Lauder, Tower Semiconductor and Tempus AI reported.
After the close: Apple (options price a move of about 4%), Palantir (about 12%, per Earnings Watcher; analysts expect revenue near $2.18 billion and adjusted EPS of $0.41), Vertex Pharmaceuticals, ON Semiconductor and Diamondback Energy. Tech has been under pressure since our October 29 recap, and the Nasdaq fell 2.86% on Friday, so Apple’s numbers set up Tuesday’s open.
What to Watch Next
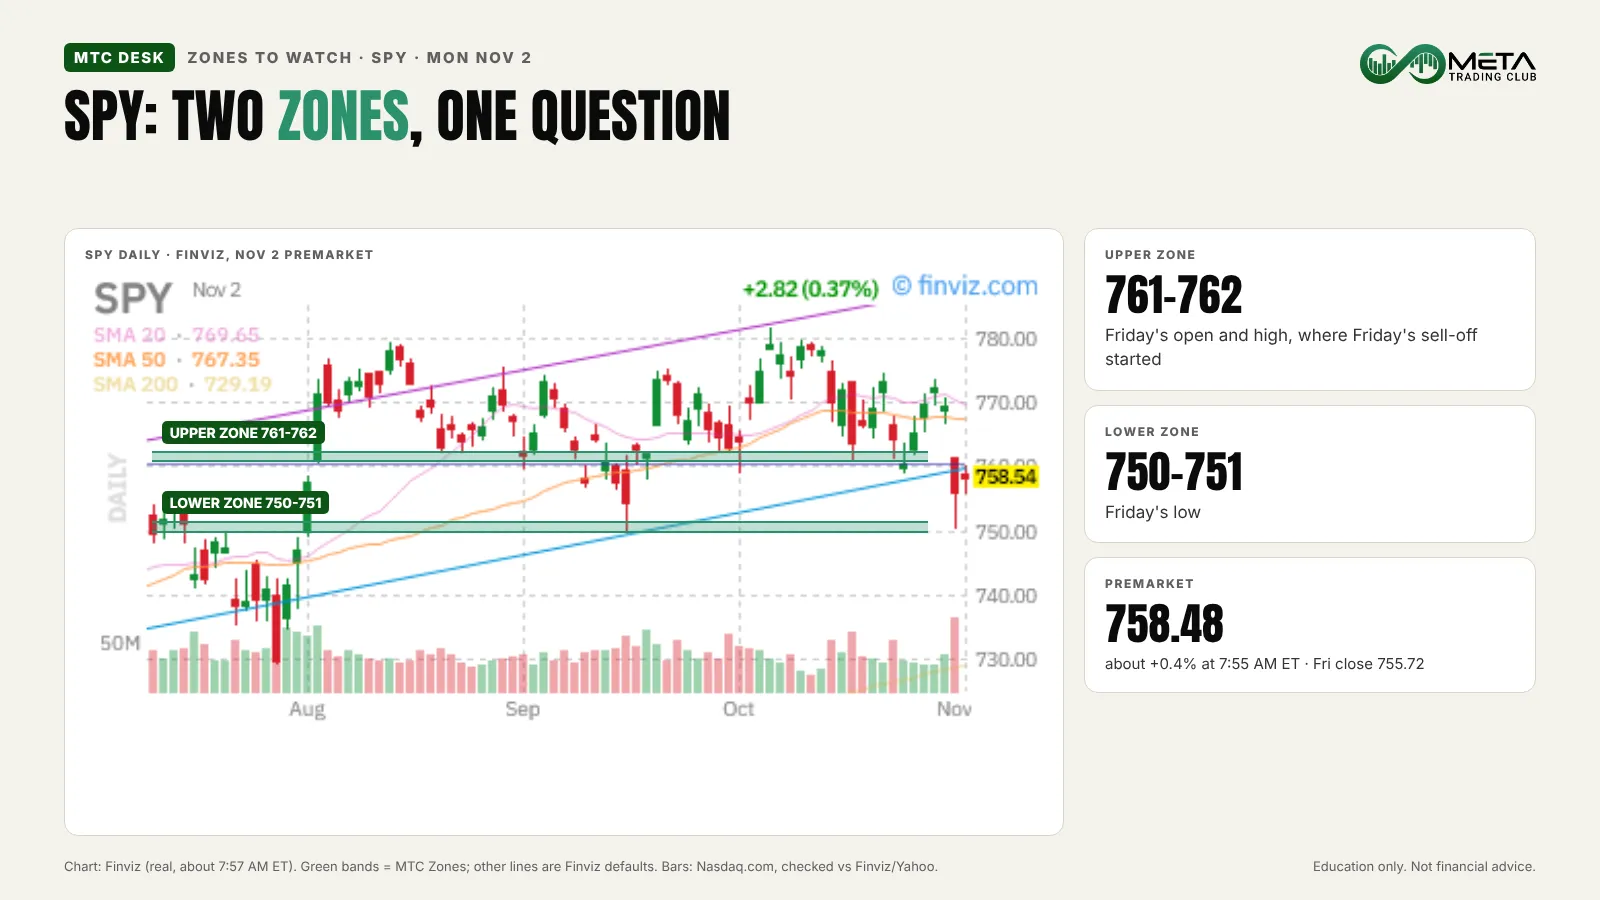
SPY 761–762 is Friday’s open and high, where the selling started. A stall there keeps the bounce in question; strength would need price to hold above it and set a higher low. SPY 750–751 is Friday’s low: a test that holds is the reaction we’d want, and a clean break says the pullback isn’t done.
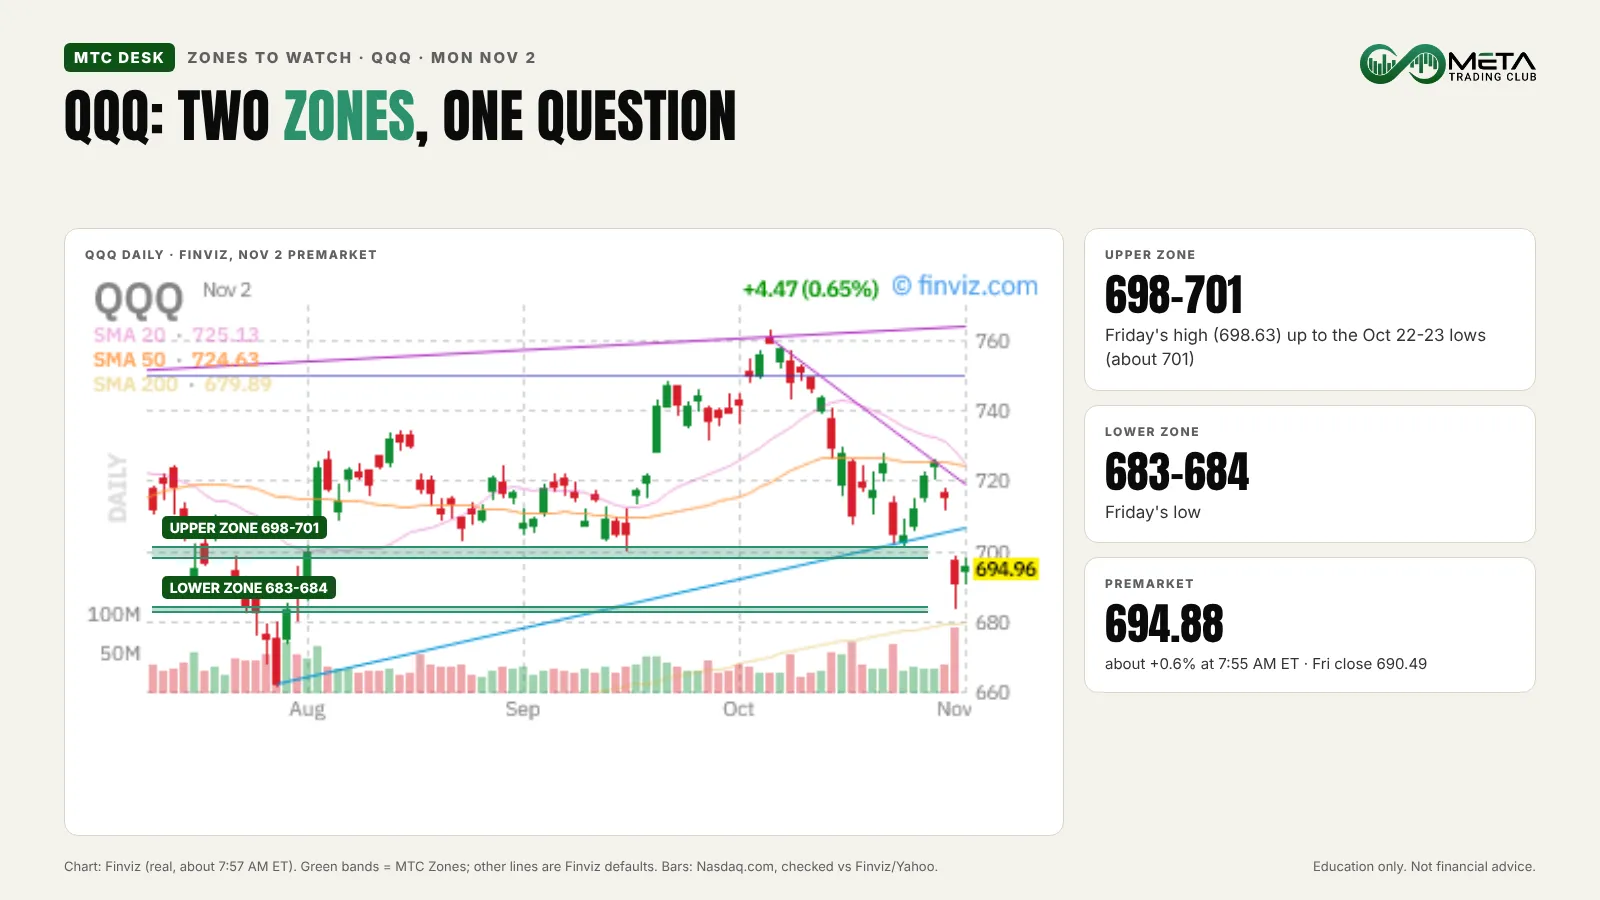
QQQ 698–701 (Friday’s high up to the October 22–23 lows) and 683–684 (Friday’s low) frame the Nasdaq side. We want SPY and QQQ to agree before trusting a move. If you’re unsure which kind of market this is, our guide to bull vs bear markets is a good place to start.
Risks: the 10:00 ISM print, Apple and Palantir tonight, the midterms and JOLTS (10:00 AM) on Tuesday with AMD after that close, and the jobs report at 8:30 AM Friday. No alignment, no trade.
FAQ
Futures are bouncing after last week’s sell-off, helped by oil falling about 4% back under $100 on hopes for more time for U.S.-Iran diplomacy. At 7:53 AM ET, S&P 500 futures were up about 0.3% and Nasdaq 100 futures about 0.6%.
The October ISM Manufacturing PMI is out at 10:00 AM ET. Consensus is 54.7 after 54.5 in September. A reading above 50 means factory activity is growing.
Apple reports fiscal fourth-quarter results after the close on Monday, November 2. Options were pricing a move of about 4% either way. Palantir, Vertex, ON Semiconductor and Diamondback also report after the close.
The upper Zone is 761 to 762 (Friday’s open and high) and the lower Zone is 750 to 751 (Friday’s low). They are places to watch for a reaction, not entries.
Sources: Finviz futures and quotes (7:53–7:55 AM ET); company releases and SEC 8-K filings (Check Point, IDEXX, Marriott, Inovio); Yahoo Finance; TradingKey; Current Logic; Globes; Grafa; Rallies; Continuum Economics; Newsquawk; Nasdaq.com daily prices. Premarket moves are approximate and change before the open.
Education only. Not financial advice.