Monday, October 12, 2026 · 8:45 AM ET · MTC Market Intelligence
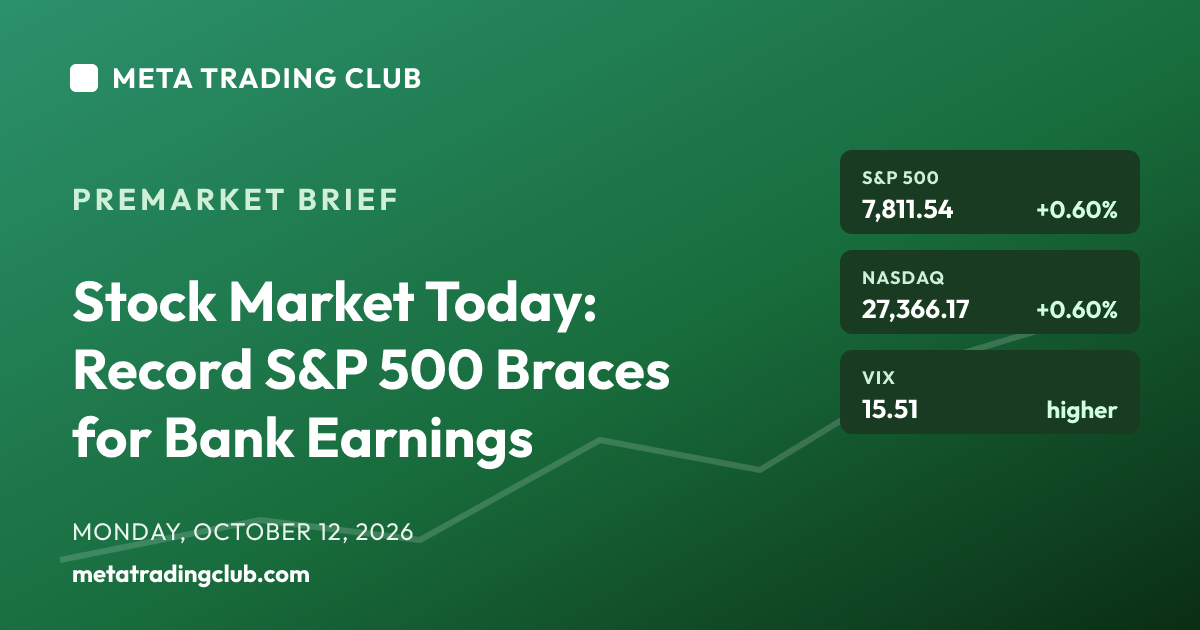
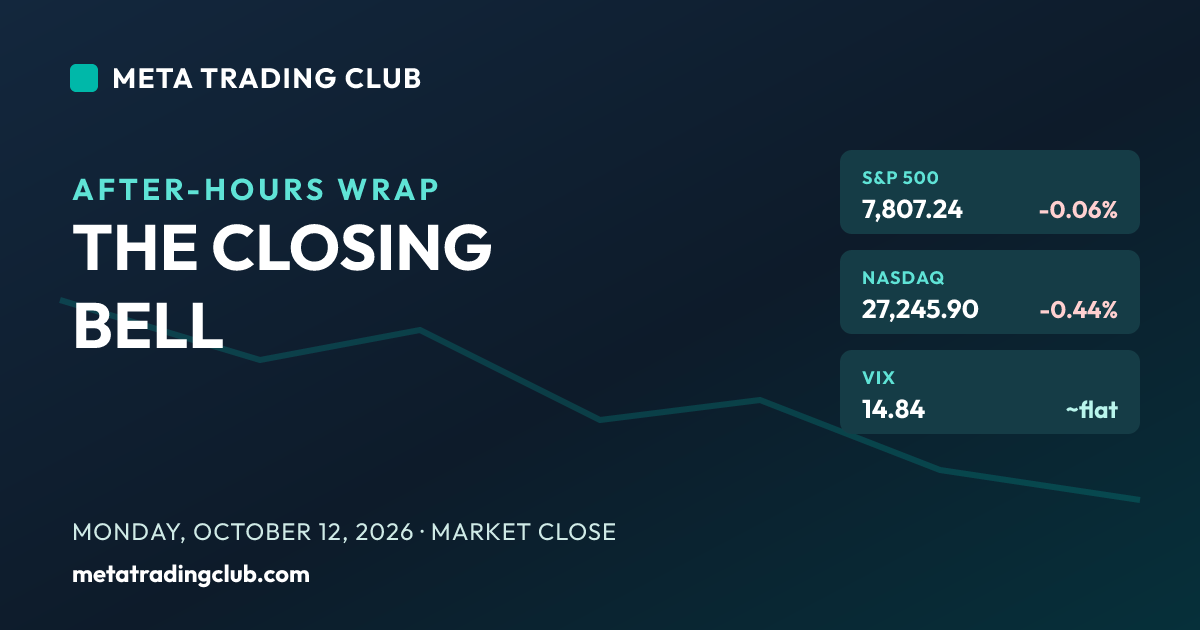
The stock market today opens at a record into the quietest session of a loud week. The S&P 500 closed Friday at 7,811.54, up 0.6%, capping a record-setting week, with the Dow up 0.83% to 51,655.01 and the Nasdaq Composite up 0.6% to 27,366.17. This is Columbus Day: the stock market is open on its regular schedule, but the Treasury market is closed, there is no economic data, and there are no notable earnings. That makes today a thin, low-catalyst drift — and the setup, not the session, is the story. Futures are barely moving: Dow and S&P 500 futures up about 0.1%, Nasdaq-100 futures little changed, small caps flat. Underneath the calm, two forces are leaning on the record. The 10-year Treasury yield is firm near 5.24%, close to a multi-decade high, and remains the single biggest headwind on a market priced for perfection. Oil is choppy near $93 WTI after President Trump said Russia and Ukraine agreed to stop attacking each other’s energy infrastructure — a supply-positive headline — even as fresh Houthi strikes on Saudi Arabia’s main airport keep Middle East risk live. The VIX ticking up to 15.5 is the first small tell that the options market is starting to price the week ahead. And it is a real week: big-bank earnings land Tuesday (JPMorgan, Goldman Sachs, Citi, Wells Fargo before the open), September CPI hits Wednesday, and retail sales Thursday. So today is a positioning day, not a conviction day. Mark SPX 7,800 as the round-number shelf the record has to hold, 7,850 as the extension wall above, and 7,750 as the deeper support below. Don’t let a quiet holiday tape pull you into forcing trades with no catalyst and thin volume. The week gets decided tomorrow, not today. No alignment, no trade.
Market Snapshot
| Instrument | Level | Change | Note |
|---|---|---|---|
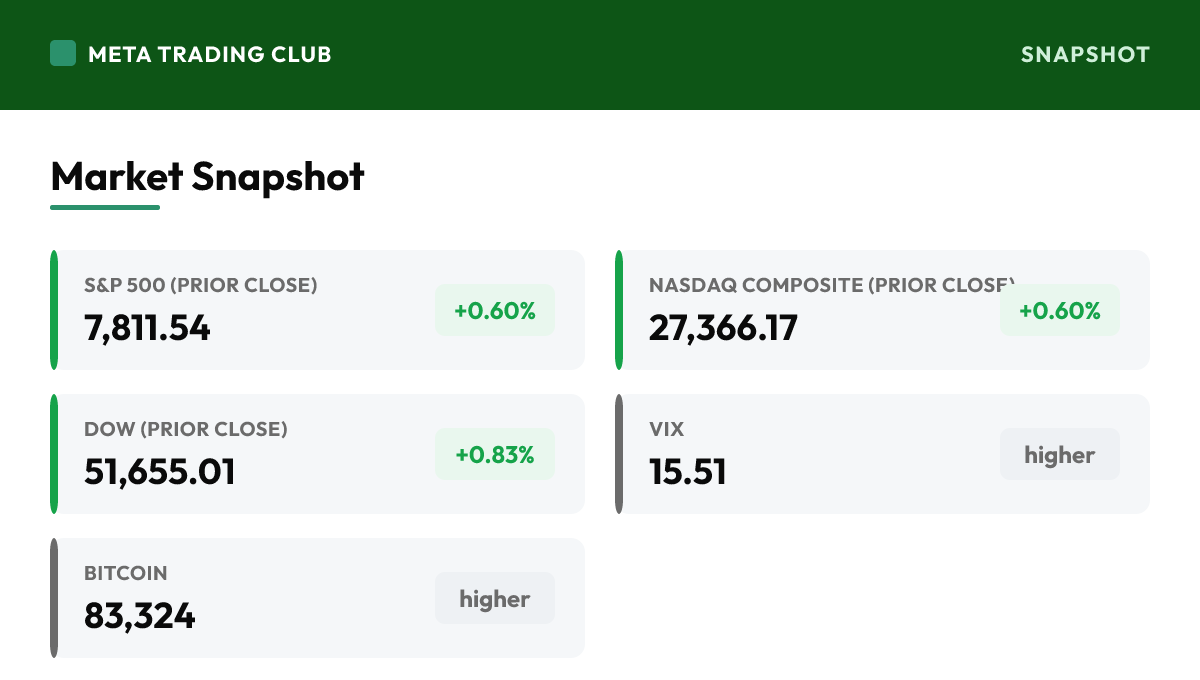
| S&P 500 (prior close) | 7,811.54 | +0.60% | Closed Friday at 7,811.54, up 0.6%, capping a record-setting week that kept the four-year-old bull market intact. That’s the backdrop: the index is sitting at an all-time high, priced for a strong earnings season and a Fed that eventually eases. This morning S&P 500 futures are up only about 0.1% — a flat, holiday-thinned drift with the Treasury market closed and no data on the calendar. The level that matters is 7,800: the round-number shelf just under Friday’s close that the record has to defend. Hold it on real volume this week and the run stays alive; lose it and fail to reclaim and the first crack in the record shows. Today is positioning into tomorrow, not a conviction session. |
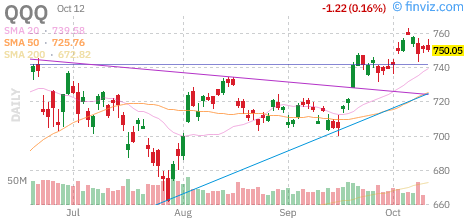
| Nasdaq Composite (prior close) | 27,366.17 | +0.60% | Printed a record close Friday at 27,366.17, up 0.6%, with the AI-chip complex still carrying the tape. This morning Nasdaq-100 futures are little changed, essentially flat. Tech is the highest-duration corner of the market, so a 10-year firm near 5.24% is the first thing that can pull it back if yields press higher into Wednesday’s CPI. The tension is familiar: chips led the record on the way up and are the most exposed if the rate story turns. Today the group is mixed premarket — Nvidia and Broadcom firmer, Apple heavy — so watch leadership breadth rather than the index tick in a thin holiday session. |
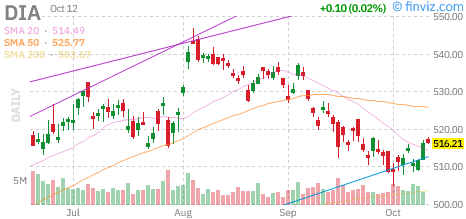
| Dow (prior close) | 51,655.01 | +0.83% | Closed Friday at 51,655.01, up 0.83% or about 423 points, the blue chips leading the record week rather than lagging it. This morning Dow futures are up about 0.1%. The value-heavy, rate-sensitive index is the one most exposed to a 10-year near 5.24%, and it’s also the one most levered to tomorrow’s bank earnings — JPMorgan, Goldman, Citi and Wells Fargo all report before Tuesday’s open and sit heavily in the financials weighting. Broad participation across the Dow, Nasdaq and small caps is what keeps a record credible; watch whether the banks can carry the index this week or whether firm yields cap it. |
| S&P 500 Futures | — | +0.1% | Up about 0.1% this morning, a flat-to-firm drift after Friday’s record close. With the Treasury market closed for Columbus Day, no economic data, and no notable earnings today, this is as quiet as the tape gets — don’t over-read a small green premarket in thin, holiday volume. The real signal is how cash trades the 7,800 shelf and whether the index can simply hold the record into tomorrow’s bank earnings and Wednesday’s CPI. Today is a positioning session; the catalysts that move the week land tomorrow. Patience beats forcing a trade in a low-liquidity drift. |
| Nasdaq-100 Futures | — | flat | Little changed this morning as high-multiple tech holds steady into a data-free holiday session. The chips led the record on the way up, which makes them the cleanest tell on the way down: if the AI complex holds its bid this week, the breakout has leadership behind it; if semis roll over while the 10-year sits near 5.24%, that’s the first sign rate pressure is reaching the market’s favorite names. This morning it’s mixed under the surface — Nvidia, Broadcom and Tesla firmer, Apple down near 2.7% — so read leadership breadth, not the flat index print, in thin volume. |
| Russell 2000 Futures | — | flat | Flat premarket near 2,821, with small caps neither leading nor lagging in a quiet holiday tape. The Russell is the most rate-sensitive group there is, so it’s the cleanest breadth tell for the week: if small caps can firm up while the 10-year holds near 5.24%, the record run is broadening and healthier; if they lag as yields press into CPI, the rally is narrowing back to megacap tech alone — exactly what you don’t want to see at an all-time high. Low conviction today; the Russell’s real signal comes once volume returns tomorrow. |
| VIX | 15.51 | higher | Ticking up about 4.5% toward 15.51 this morning — still a low, calm reading, but the small lift is the first tell that the options market is starting to price the week ahead. A VIX near 15 sitting on top of a record market, a 10-year near multi-decade highs, and a wall of catalysts (banks Tuesday, CPI Wednesday) is conditional calm: comfortable until it isn’t. Low volatility is not low risk; it’s the market pricing almost none. Treat the uptick as a quiet warning to respect the week, not a reason to hedge aggressively into a holiday session with no catalyst. |
| WTI Crude | 92.99 | higher | Choppy near $92.99 this morning, with the energy tape pulled two ways. On one side, President Trump said Russia and Ukraine agreed to stop attacking each other’s energy infrastructure, plus a US-Russia diesel-supply deal — both supply-positive, which pressured crude lower overnight. On the other, fresh Houthi strikes on Saudi Arabia’s main airport and talk of the US joining Saudi action against the Houthis keep Middle East risk live. Net, oil is range-bound around $93 rather than spiking. Track crude as the macro swing factor into CPI: sustained strength feeds the inflation worry that keeps the 10-year firm; a clean de-escalation takes heat off yields. |
| 10-Yr Yield | 5.24% | higher | Firm near 5.24% this morning — close to a multi-decade high and the single most important number on the screen this week, even with the Treasury market closed for the holiday. This is the force that should be capping a record stock market, and with September CPI landing Wednesday, the bond market is the thing to watch. A hot inflation print pushes the 10-year higher and the breakout gets a real headwind; a cooler read lets yields ease and gives stocks room. Note the recent theme that the 10-year is now taking its cue less from oil and more from fiscal and inflation worries. Watch it more closely than any single stock. |
| Bitcoin | 83,324 | higher | Firm near $83,324 this morning, up about 0.3%, steadying alongside equities as the highest-beta risk asset holds its ground in a quiet tape. Crypto holding while stocks sit at records is a mild risk-on tell — the speculative end of the curve isn’t flinching ahead of the week’s catalysts. Treat Bitcoin as a sentiment gauge: steady alongside equities says risk appetite is holding and the record has support; a sharp roll-over intraday is often the first place a broader risk-off shows up before it reaches the index. A calm Bitcoin into a data-free holiday fits the low-conviction drift. |
Charts to Watch
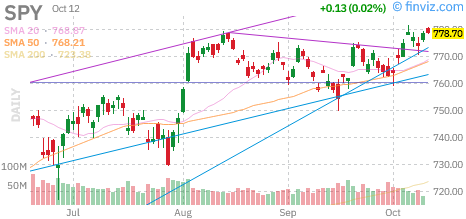
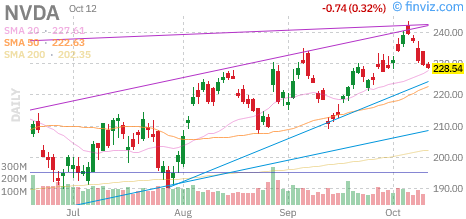
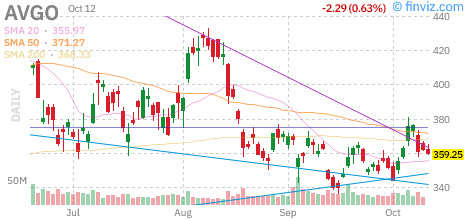
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
Overnight & Global Markets
Friday closed the week on a record across the board. The S&P 500 rose 0.6% to 7,811.54, an all-time high, with the Dow up 0.83% to 51,655.01 and the Nasdaq Composite up 0.6% to 27,366.17, capping a record-setting week and keeping a four-year-old bull market intact. Today is Columbus Day — the stock market is open on its normal schedule, but the Treasury market is closed, there is no economic data, and there are no notable earnings. That makes this a thin, low-catalyst drift, and the setup matters far more than the session. Futures are barely moving: Dow and S&P 500 futures up about 0.1%, Nasdaq-100 little changed, small caps flat. Two forces lean on the record underneath the calm. The 10-year Treasury yield is firm near 5.24%, close to a multi-decade high, the headwind a market priced for perfection can’t ignore. Oil is choppy near $93 WTI after President Trump said Russia and Ukraine agreed to stop targeting each other’s energy infrastructure — supply-positive — even as fresh Houthi strikes on Saudi Arabia’s main airport keep Middle East risk live. The VIX ticking up toward 15.5 is the first small sign the options market is pricing the week ahead. And it’s a real week: big-bank earnings Tuesday (JPMorgan, Goldman, Citi, Wells Fargo before the open), September CPI Wednesday, retail sales Thursday. So today is positioning, not conviction. Mark SPX 7,800 as the shelf the record has to hold, 7,850 as the extension wall above, and 7,750 as the deeper support below. Don’t let a quiet holiday tape bait you into forcing trades with no catalyst and thin volume — the week gets decided tomorrow.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The whole week runs through one setup: the S&P 500 just closed Friday at a record (7,811.54, +0.6%), capping a record-setting week — and now it has to hold that record against a 10-year near 5.24% and a wall of catalysts. Today isn’t one of them. It’s Columbus Day: the stock market is open on its regular schedule, but the Treasury market is closed, there’s no economic data, and there are no notable earnings. Futures are barely moving — Dow and S&P 500 up about 0.1%, Nasdaq-100 flat, small caps flat. This is a thin, low-catalyst drift and a positioning session, not a conviction day. The move that matters is how the index sets up into tomorrow.
- The real catalysts are stacked just ahead. Big-bank earnings kick off Q3 season Tuesday before the open — JPMorgan, Goldman Sachs, Citi and Wells Fargo all report, with Bank of America and Morgan Stanley on Wednesday — the first broad test of corporate America against rising yields. September CPI lands Wednesday and retail sales Thursday, the two data points that will set the 10-year’s direction and, by extension, the record’s. So the week front-loads the quiet and back-loads the risk: a sleepy holiday Monday into a Tuesday-through-Thursday gauntlet. Use today to mark levels and plan, not to force a position before the information arrives.
- Energy and geopolitics frame the macro. Oil is choppy near $93 WTI after President Trump said Russia and Ukraine agreed to stop attacking each other’s energy infrastructure, alongside a US-Russia diesel-supply deal — both supply-positive and the reason crude slipped overnight. Cutting the other way, fresh Houthi strikes on Saudi Arabia’s main airport that killed 12, and talk of the US joining Saudi action against the Houthis, keep Middle East risk live. The net is a range-bound crude rather than a spike. That matters because a calmer oil tape takes some pressure off the inflation-and-yield loop heading into Wednesday’s CPI — a quiet positive the market will take.
Stock-Specific
- Apple (AAPL) is the standout large-cap decliner, down about 2.7% premarket, as the AI-chip narrative rotates around it — reports of an Apple AI-chip deal with Broadcom lifted AVGO while weighing on Apple’s own relative positioning. It’s a clean, company-specific move in an otherwise flat tape, not a market-direction signal. Trade it on its own levels. The broader tell is that even on a quiet holiday, the AI-hardware supply chain is where the money is rotating — who supplies whom for frontier compute is now a daily driver of the megacap complex.
- The AI-chip complex is trading two-sided and it’s the leadership read for the week. Nvidia (NVDA) is up about 1.5%, Broadcom (AVGO) up near 1.6% after the Apple deal and CEO Lip-Bu Tan’s comment that AI hardware stays in short supply for the next two to three years, and Tesla (TSLA) up about 1.9%. Against them, Micron (MU) is down about 2% after China’s CXMT said it will produce next-generation memory to compete with US and Korean suppliers, and IREN popped on an Anthropic cloud-computing deal. Trade these on their own levels and treat the complex as one tell: broad strength holding keeps the breakout credible; a roll-over while yields press is the first crack.
- The names that actually move the week don’t trade today — they report tomorrow. JPMorgan, Goldman Sachs, Citi and Wells Fargo headline Tuesday’s premarket, and options are pricing roughly 3.65%-5% moves on the big banks into the prints. The question the group answers: can record trading and capital-markets revenue offset margin pressure from a 5.24% 10-year and any softening in credit. Don’t position ahead of a binary like bank earnings season; use today to mark the levels on the financials and the index, and let tomorrow’s reaction set up the trade. A beat-and-hold confirms the record; a guide-down into firm yields is the first real test.
Global and Macro
- The bond market is the macro story everything else bends around, and this week it has scheduled triggers — just not today. The 10-year near 5.24%, close to a multi-decade high, is the force that should be capping a record stock market, and September CPI on Wednesday is the event that can push it. The recent theme is that the 10-year is taking its cue less from oil and more from fiscal and inflation worries, with bond yields surging worldwide. With the Treasury market closed today there’s no fresh signal, which is exactly why today is a positioning session. Watch the 10-year’s reaction to Wednesday’s CPI as the real driver of every risk asset this week.
- Here’s the frame for the day — and the week. The market is at a record with yields near multi-decade highs and AI-bubble chatter growing louder; strip out the AI names and US equities have actually lagged Europe this year, a reminder of how concentrated this run is. That resilience is real, but a record sitting on narrow leadership into a heavy catalyst week is the most vulnerable kind of strength. The lesson isn’t to fade the record or to chase it in a thin holiday tape — it’s to let the week’s information arrive. A record isn’t confirmed until it holds through the catalysts. Mark 7,800 and let it prove itself Tuesday through Thursday.
TECHNICAL ANALYSIS
S&P 500 Key Levels
- The S&P closed Friday at 7,811.54, a record. That makes 7,800 the single most important level this week — the round-number shelf just under the close that the record has to defend. Hold above 7,800 on real volume once the holiday thins out, with breadth from the banks, the Dow and small caps rather than tech alone, and the record run stays valid into CPI. Above, 7,850 is the extension wall, the next round number the move has to clear to prove it’s trending rather than just sitting at the highs. Don’t chase into 7,850 in a thin Monday tape; let the market earn it after the week’s catalysts arrive and it has defended 7,800.
- Below 7,800, 7,750 is the deeper support that keeps the record intact — the first real floor where an orderly pullback holds and a dip is just a dip. Lose 7,750 and fail to reclaim it and the picture shifts: the record starts to look tired, the oil-and-yield pressure is showing up in price, and the tape opens back toward 7,700. Mark 7,850 above and 7,750 below, with 7,800 as the line in the sand in between. In today’s holiday session the levels are reference points, not triggers — volume is too thin to trust a break. The real test of these levels comes tomorrow and Wednesday, not today.
Sector and Sentiment
- The leadership read is two-sided and worth pre-marking into the week. The AI chips that drove the record are mixed this morning — Nvidia and Broadcom firmer, Apple and Micron heavy — and the financials that own tomorrow’s tape aren’t moving yet. For the record run to hold through the catalysts you want breadth to broaden, not narrow: the banks delivering, the Dow and small caps joining, not megacap tech left carrying the index alone. If the complex holds its bid and the banks beat-and-hold Tuesday, the breakout keeps its footing; if the rally narrows while yields press into CPI, that’s the first sign the move is running out of fuel at the highs.
- The VIX near 15.51, ticking up about 4.5%, says the options market is still pricing very little fear into a tape at records — but the small lift is the first sign it’s starting to respect the week ahead. That combination is conditional calm: comfortable until a hot CPI or a bank guide-down changes the math. Practically, respect that the quiet can break fast once volume and catalysts return, keep the 10-year on your screen as the real driver, and let SPX prove the 7,800 shelf through the week’s data before committing size. Low volatility is not low risk — it’s the market pricing almost none right before it may have to reprice.
TODAY’S ECONOMIC CALENDAR
Key Releases (ET)
- Today is clean: no economic data is scheduled because of the Columbus Day holiday, and the Treasury market is closed even though the stock market trades on its normal schedule. That absence is the point — with no data and no Fed speakers to move the 10-year, the session has nothing to price, which is why it’s a thin, low-catalyst drift. The weight of the week lands midweek: September CPI on Wednesday is the marquee release, the single data point most likely to set the 10-year’s direction and the record’s, followed by retail sales on Thursday. Use today to plan around those, not to react to anything.
- The calendar front-loads the quiet and back-loads the risk. Beyond the data, Q3 earnings season opens Tuesday with the big banks and runs hot through the month. For this session, there’s nothing to trade on the macro — so the discipline is to mark levels, size down, and let the week’s information come to you. CPI on Wednesday is the kind of scheduled catalyst that can reprice the 10-year in seconds and take the record with it, so keep real risk measured into midweek rather than committing in a holiday-thinned Monday with no edge on offer.
Earnings Today
- There are no notable earnings today — another reason the tape is quiet. The action starts tomorrow: JPMorgan, Goldman Sachs, Citi and Wells Fargo all report Q3 results before Tuesday’s open, with Bank of America and Morgan Stanley on Wednesday. Options are pricing roughly 3.65%-5% moves on the big banks into the prints, and the group’s reaction will set the tone for the whole reporting season. The core question is whether record trading and capital-markets revenue can offset the pressure from a 5.24% 10-year and any softening in credit quality. These are the names to pre-mark today, not trade.
- Look ahead, not at today’s empty calendar. The banks on Tuesday are the first broad read on whether high yields are starting to bite corporate results, and the megacap and chip names later in the month will test the AI-capex story that’s carried the record. Don’t position ahead of a binary like bank earnings. For today, there’s nothing to react to — mark the levels on the financials and the index, keep risk measured, and let tomorrow’s bank reactions and Wednesday’s CPI set up the trades that actually matter this week.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,850 — the extension wall. The next round number above Friday’s 7,811.54 record close and the level the breakout has to clear to prove it’s trending, not just sitting at the highs. A push through and a hold here, with breadth from the banks, the Dow and small caps rather than tech alone, is the tape saying the record run has legs even against a firm 10-year — and the door opens higher. But don’t chase into 7,850 in a thin holiday Monday. Make the market defend 7,800 first and earn this level on real volume once the week’s catalysts arrive; a record stalling at the next wall while yields press into CPI is exactly where chasers get trapped.
- SPX 7,800 — the shelf and the line in the sand. The round-number floor just under Friday’s record close that the index has to defend to keep the run valid. This is the whole trade this week: hold above 7,800 on real volume and the breakout stays alive; lose it and fail to reclaim and the first crack in the record shows. In today’s holiday session this level is a reference point, not a trigger — volume is too thin to trust a break. The real signal is which side SPX leaves 7,800 on once the banks report Tuesday and CPI hits Wednesday. Inside is noise; the move off the line, with volume behind it, is the trade. Patience beats forcing it.
- SPX 7,750 — the deeper support that keeps the record intact. The first real floor below the shelf. Hold it and a pullback is just a dip inside a fresh uptrend. Lose 7,750 and fail to reclaim it and the record starts to look tired — the oil-and-yield pressure is finally showing up in price, and the tape opens back toward 7,700. Below 7,750 the job shifts from catching the breakout to capital preservation. Mark it, and respect it if it goes — but not on today’s thin holiday volume. A failed hold on real volume after the week’s catalysts is the clean signal; a holiday-session wick is not.
Bull case: The record holds and extends through the catalysts. The big banks beat-and-hold Tuesday on strong trading and capital-markets revenue, September CPI comes in cool enough Wednesday to let the 10-year ease off 5.24%, and oil stays calm on the Russia-Ukraine energy agreement. SPX defends 7,800, the AI chips hold their bid, and breadth improves as financials, the Dow and small caps join rather than leaving megacap tech alone. In this scenario the resilience that carried the market to a record wins again: the breakout proves itself through the week’s data, 7,850 comes into play, and the path of least resistance stays higher even with yields near a multi-decade high.
Bear case: The catalyst week finally bites the record. The banks guide cautiously on credit or margins Tuesday, September CPI runs hot Wednesday, and the 10-year pushes further above 5.24%. SPX fails to hold 7,800, loses the 7,750 shelf, and the AI chips — the longest-duration, most rate-exposed leadership — roll over first while the record’s narrow breadth gives way. AI-bubble chatter gets louder, the VIX snaps off its complacent lows, and the all-time high becomes the top of the range rather than a launchpad. A record that fails on a hot CPI and firm yields is a clean short setup — but it needs the data to confirm it, not a thin holiday Monday.
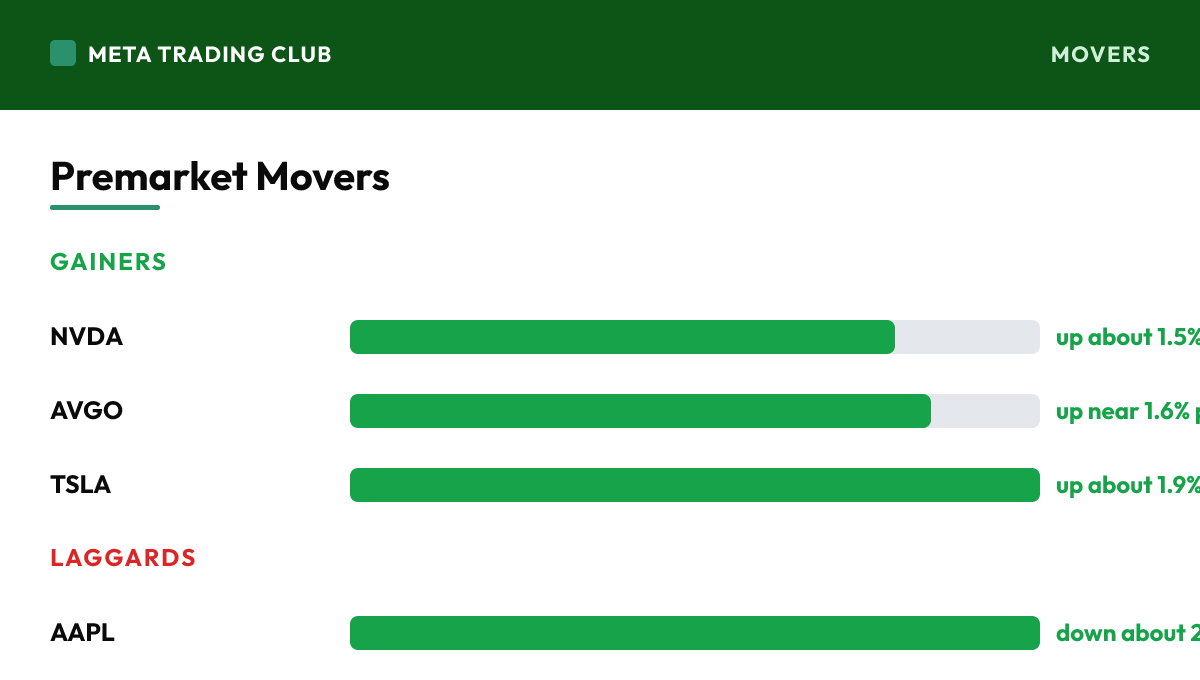
Premarket Movers
Gainers
| NVDA | Nvidia | up about 1.5% premarket as the AI-chip complex holds its bid; leadership tell for the week | Up about 1.5% this morning as the AI-chip complex holds its bid in an otherwise flat holiday tape. Nvidia remains the anchor of the market’s highest-conviction theme — the AI-infrastructure and frontier-compute buildout — and its relative strength is the cleanest read on whether that trade still has legs into a heavy catalyst week. Trade NVDA on its own levels and treat it as the tell for the whole complex: holding its bid keeps the record’s engine running; rolling over while the 10-year sits near 5.24% into Wednesday’s CPI is the first sign rate pressure is reaching the names that led. |
| AVGO | Broadcom | up near 1.6% premarket on an Apple AI-chip deal and CEO comments on tight hardware supply | Up near 1.6% this morning after reports of an Apple AI-chip deal and CEO Lip-Bu Tan’s comment that AI hardware stays in short supply for the next two to three years — a supply-constraint message that underpins the whole custom-silicon trade. Broadcom’s networking and custom-silicon exposure makes it a core beneficiary of the hyperscaler capex cycle, and today’s strength came partly at Apple’s expense as the AI-hardware supply chain rotated. Trade it on its own levels and treat the complex as one tell: broad chip strength holding supports the record; a fade while yields climb into CPI is the first crack in the leadership. |
| TSLA | Tesla | up about 1.9% premarket, firmest of the megacaps in a quiet holiday tape | Up about 1.9% this morning, the firmest of the megacap names in a thin, data-free session. Tesla trades as much on sentiment and its own product and delivery narrative as on the macro, so its premarket strength is a risk-on flicker rather than a market-direction signal in a holiday tape. Trade it on its own levels and don’t over-read a single green premarket print in low volume. The broader read is that the high-beta end of the megacap complex has a bid this morning, which fits the calm, risk-on drift — but conviction only comes once volume and the week’s catalysts return tomorrow. |
Laggards
| AAPL | Apple | down about 2.7% premarket as the AI-hardware supply chain rotates around a Broadcom chip deal | Down about 2.7% premarket, the standout large-cap decliner in an otherwise flat tape, as the AI-chip narrative rotates around it — reports of an Apple AI-chip deal with Broadcom lifted AVGO while weighing on Apple’s own relative positioning. It’s a clean, company-specific move, not a market-direction signal. Trade it on its own levels. The broader tell is that even on a quiet holiday Monday, the AI-hardware supply chain is where the money is rotating, and Apple’s relative weakness against a firmer Broadcom and Nvidia shows how much the megacap complex now trades on frontier-compute supply dynamics. |
| MU | Micron Technology | down about 2% premarket after China’s CXMT flagged next-gen memory to compete with US and Korean chipmakers | Down about 2% this morning after China’s CXMT said it will begin producing next-generation memory chips that compete directly with US and Korean suppliers — a competitive-threat headline that hits the memory trade specifically. It’s a company-and-subsector story, not a market signal, and a reminder that the AI-chip complex isn’t a single monolith: the custom-silicon and networking names can rally while memory sells off on supply competition. Trade MU on its own levels and read it alongside the rest of the group — divergence within the complex is itself a tell about where the AI-capex dollars are actually flowing. |
Risks Into the Open
- Primary risk today: over-trading a dead tape. It’s Columbus Day, the Treasury market is closed, there’s no data and no earnings — a thin, low-catalyst holiday drift. The trap is manufacturing a trade out of boredom, reading conviction into a flat premarket, or trusting a level break on volume that isn’t really there. There’s no edge on offer in a session with no catalyst. The discipline is to mark levels, size down, and wait: the real information — big-bank earnings Tuesday, CPI Wednesday — lands within 24 to 48 hours. Patience in a quiet tape is a position. Don’t let a boring Monday cost you the capital you’ll want when the week actually sets up.
- The structural risk is the bond market, and this week it has scheduled triggers. The 10-year near 5.24% is close to a multi-decade high, and September CPI on Wednesday is the event that can push it. The theme lately is that the 10-year is driven less by oil and more by fiscal and inflation worries, with yields surging worldwide. A hot CPI sends the 10-year higher and the pressure that’s supposed to cap a record market finally shows up in price; a cool read lets yields ease and gives stocks room. Keep the yield on your screen into Wednesday as the real driver of every risk asset — the record’s fate runs through the bond market, not any single stock.
- The concentration risk is the quiet one under the record. Strip out the AI names and US equities have lagged Europe this year — the all-time high is sitting on narrow, megacap-tech leadership, and AI-bubble chatter is getting louder. That’s fine while the chips hold their bid, but it means the record is more fragile than the index level suggests: if the AI complex wobbles into the week’s catalysts, there isn’t broad breadth underneath to cushion it. Watch leadership breadth — the banks, the Dow, small caps joining rather than tech carrying alone — as the real health check on whether this record can survive a heavy catalyst week.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Monday, October 12, 2026, S&P 500 futures are at 7,811.54 (+0.60%), with the VIX near 15.51. The stock market today opens at a record into the quietest session of a loud week. The S&P 500 closed Friday at 7,811.54, up 0.6%, capping a record-setting week, with the Dow up 0.83% to 51,655.01 and the Nasdaq Composite up 0.6% to 27,366.17. This is Columbus Day: the stock market is open on its regular schedule, but the Treasury market is closed, there is no economic data, and there are no notable earnings. That makes today a thin, low-catalyst drift — and the setup, not the session, is the story. Futures are barely moving: Dow and S&P 500 futures up about 0.1%, Nasdaq-100 futures little changed, small caps flat. Underneath the calm, two forces are leaning on the record. The 10-year Treasury yield is firm near 5.24%, close to a multi-decade high, and remains the single biggest headwind on a market priced for perfection. Oil is choppy near $93 WTI after President Trump said Russia and Ukraine agreed to stop attacking each other’s energy infrastructure — a supply-positive headline — even as fresh Houthi strikes on Saudi Arabia’s main airport keep Middle East risk live. The VIX ticking up to 15.5 is the first small tell that the options market is starting to price the week ahead. And it is a real week: big-bank earnings land Tuesday (JPMorgan, Goldman Sachs, Citi, Wells Fargo before the open), September CPI hits Wednesday, and retail sales Thursday. So today is a positioning day, not a conviction day. Mark SPX 7,800 as the round-number shelf the record has to hold, 7,850 as the extension wall above, and 7,750 as the deeper support below. Don’t let a quiet holiday tape pull you into forcing trades with no catalyst and thin volume. The week gets decided tomorrow, not today. No alignment, no trade.
What is the biggest catalyst for the market today?
The whole week runs through one setup: the S&P 500 just closed Friday at a record (7,811.54, +0.6%), capping a record-setting week — and now it has to hold that record against a 10-year near 5.24% and a wall of catalysts. Today isn’t one of them. It’s Columbus Day: the stock market is open on its regular schedule, but the Treasury market is closed, there’s no economic data, and there are no notable earnings. Futures are barely moving — Dow and S&P 500 up about 0.1%, Nasdaq-100 flat, small caps flat. This is a thin, low-catalyst drift and a positioning session, not a conviction day. The move that matters is how the index sets up into tomorrow.
What key levels should traders watch today?
SPX 7,850 — the extension wall. The next round number above Friday’s 7,811.54 record close and the level the breakout has to clear to prove it’s trending, not just sitting at the highs. A push through and a hold here, with breadth from the banks, the Dow and small caps rather than tech alone, is the tape saying the record run has legs even against a firm 10-year — and the door opens higher. But don’t chase into 7,850 in a thin holiday Monday. Make the market defend 7,800 first and earn this level on real volume once the week’s catalysts arrive; a record stalling at the next wall while yields press into CPI is exactly where chasers get trapped. SPX 7,800 — the shelf and the line in the sand. The round-number floor just under Friday’s record close that the index has to defend to keep the run valid. This is the whole trade this week: hold above 7,800 on real volume and the breakout stays alive; lose it and fail to reclaim and the first crack in the record shows. In today’s holiday session this level is a reference point, not a trigger — volume is too thin to trust a break. The real signal is which side SPX leaves 7,800 on once the banks report Tuesday and CPI hits Wednesday. Inside is noise; the move off the line, with volume behind it, is the trade. Patience beats forcing it. SPX 7,750 — the deeper support that keeps the record intact. The first real floor below the shelf. Hold it and a pullback is just a dip inside a fresh uptrend. Lose 7,750 and fail to reclaim it and the record starts to look tired — the oil-and-yield pressure is finally showing up in price, and the tape opens back toward 7,700. Below 7,750 the job shifts from catching the breakout to capital preservation. Mark it, and respect it if it goes — but not on today’s thin holiday volume. A failed hold on real volume after the week’s catalysts is the clean signal; a holiday-session wick is not.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – October 12, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.