Monday, September 28, 2026 · 8:45 AM ET · MTC Market Intelligence
The stock market today is opening the week with a rotation, not a rally. Friday the tape finished green across the board — the Dow ran 478 points, or 0.93%, to 51,828.62, the S&P 500 added 0.51% to 7,743.41, and the Nasdaq Composite rose 0.50% to 27,068.72 — and every major index booked a weekly win. This morning that momentum flips. Futures are lower and the split is the tell: Nasdaq-100 futures are down about 1.05%, S&P 500 futures off 0.54%, Dow futures down 0.48%, and Russell 2000 futures off 0.70%. Tech is leading the way down while energy leads up. The reason is sitting in two places on the screen — the 10-year yield and the oil tape. WTI is up roughly 4% and back above $96 after President Trump rejected Iran’s proposal to end the war and pushed back on a Strait of Hormuz deal, adding a fresh war premium to crude. At the same time the 10-year has crossed 5.2%, a generational high, and rising yields are draining the same rate-sensitive and high-multiple corners that led Friday. Meta is down about 3% premarket, giving back part of last week’s 13% run on its Muse AI-agent news, as the whole AI trade sells off. United Airlines and the other carriers are lower on the jet-fuel math from higher oil. Newmont is off more than 4% as gold falls 3% under the weight of a 5.2% yield. That is the map: oil and defensives up, AI and rate-sensitive down. And it is happening into the most important week of data in a month — JOLTS Tuesday, ISM Manufacturing and core PCE Wednesday, then ISM Services and the September jobs report Friday, with Barclays looking for just 50,000 nonfarm payrolls. Layer in a full slate of Fed speakers — Barkin, Cook, Goolsbee, Kashkari, Williams, Barr, Waller — and you have a week that trades the rate path, not the headline. So Monday is a map day, not a chase day. Mark where the lines are before the data hits: SPX 7,700 is the pivot the open rotates around, 7,760 is the reclaim that says Friday’s strength is still intact, and 7,660 is the line that keeps the structure from unwinding toward 7,600. No alignment, no trade.
Market Snapshot
| Instrument | Level | Change | Note |
|---|---|---|---|
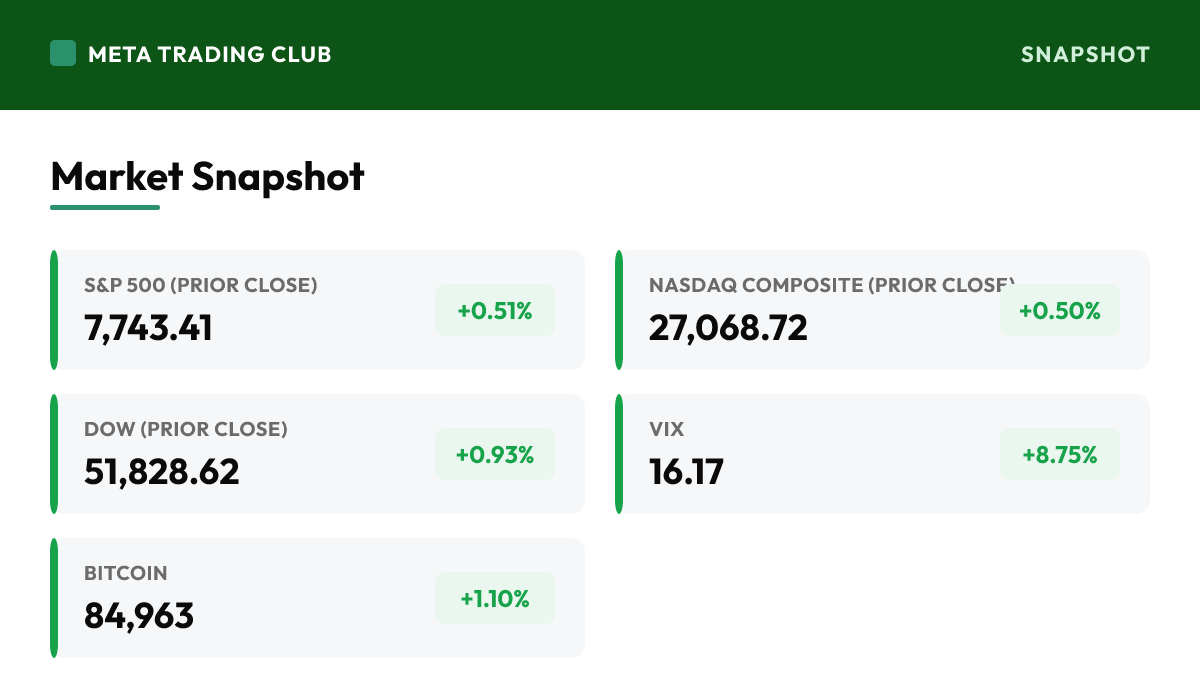
| S&P 500 (prior close) | 7,743.41 | +0.51% | Closed Friday at 7,743.41, up 0.51%, capping a weekly win as the tape shrugged off a bond sell-off. That close is the axis the morning rotates around: futures point back below it, so the first job of the session is whether cash can reclaim 7,743 or whether the open confirms the rotation lower. A strong Friday into a weak Monday is the classic setup where the weekend headline — here, oil and Iran — resets the tape before the data even hits. |
| Nasdaq Composite (prior close) | 27,068.72 | +0.50% | Rose 0.50% Friday to 27,068.72, riding the same AI-infrastructure strength that led all week. This morning it is the epicenter of the pullback — Nasdaq-100 futures are the weakest of the majors, down about 1.05%, as the AI trade broadly sells off and Meta gives back part of last week’s run. When the leadership group is the one leaking hardest premarket, treat it as the highest-beta read on the yield spike, not a company story. |
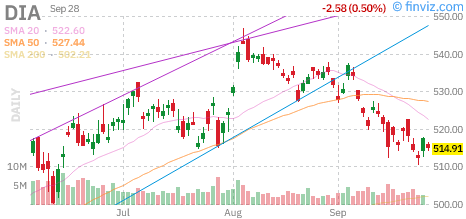
| Dow (prior close) | 51,828.62 | +0.93% | Led Friday with a 478-point gain, up 0.93% to 51,828.62 — the blue chips did the heavy lifting into the weekend. This morning Dow futures are the most resilient of the three, off only about 0.48%, because the rotation is out of high-multiple tech and into energy and defensives that live more in the Dow. When the Dow holds better than the Nasdaq on a down open, that is rotation, not a broad-market break. |
| S&P 500 Futures | — | -0.54% | Down about 0.54% this morning, pointing the cash open back under Friday’s 7,743 close. Don’t over-read the exact print — the signal is the split beneath it: the S&P is caught between energy pulling up and AI pulling down. Watch whether the index defends 7,700 once cash trades; the futures tell you the direction, the reaction at the level tells you whether it sticks. |
| Nasdaq-100 Futures | — | -1.05% | Off about 1.05%, the weakest major this morning as the AI trade sells off and the 10-year presses over 5.2%. High-multiple growth is where a yield spike bites first, and the Nasdaq is carrying the most of that duration. If the chips and megacap names can’t stabilize after the open, the rest of the tape has no leader to lean on — the Nasdaq is the tell on whether this is a dip or a rotation with legs. |
| Dow Futures | — | -0.48% | Down about 0.48%, holding up best of the three because the money leaving tech is rotating toward energy and defensives that carry more weight in the Dow. That relative strength is the honest signal this morning: this is a rotation inside the market, not a wholesale exit. Watch whether the Dow’s outperformance holds through the open — if it does, the pullback is a reshuffle, not a collapse. |
| Russell 2000 Futures | — | -0.70% | Off about 0.70%, small caps pointing lower again as the 10-year crosses 5.2%. The most rate-sensitive corner of the market feels a yield spike first, and their weakness into a jobs week is the clean tell on how the tape reads higher-for-longer. If the Russell can’t find a bid with the data still ahead, it says the market is bracing for rates to stay elevated, not fall. |
| VIX | 16.17 | +8.75% | Jumped about 8.75% to 16.17 as the oil spike and yield move woke up the options market. It’s still a low absolute reading, but the direction matters more than the level this morning: fear is being repriced higher off a complacent base right as a heavy data week begins. A rising VIX into JOLTS, ISM and Friday’s jobs report says the market is starting to pay up for protection — respect that the calm can keep unwinding if the data disappoints. |
| WTI Crude | 96.10 | +4.0% | Up roughly 4% and back above $96 after President Trump rejected Iran’s proposal to end the war and pushed back on a Strait of Hormuz deal, adding a fresh war premium to crude. This is the engine of the morning’s rotation: higher oil lifts energy, pressures airlines and consumers, and feeds straight into the inflation-and-yield loop that keeps the Fed cautious. If crude holds above $96 into the jobs week, it keeps upward pressure on the 10-year and on the whole rate-sensitive tape. |
| 10-Yr Yield | 5.19% | higher | Pressing higher and crossing 5.2% intraday, a generational high and the single most important number on the screen. Everything about this morning — the AI selloff, the small-cap weakness, gold falling 3% — traces back to a 10-year at these levels. Rising yields drain high-multiple growth and non-yielding assets first. Into a week of jobs data and Fed speakers, the direction of the 10-year is what decides whether this rotation deepens or stabilizes. |
| Bitcoin | 84,963 | +1.10% | Firm near $84,960, up about 1.1% and holding its bid even as the 10-year spikes and equities wobble — one of the few risk assets green this morning. It’s a modest tell that appetite hasn’t fully drained, but with rates at a generational high, treat the crypto bid as a spot of relative strength to watch, not confirmation the broad tape is healthy. Crypto holding while AI sells off is a rotation signal, not an all-clear. |
Charts to Watch
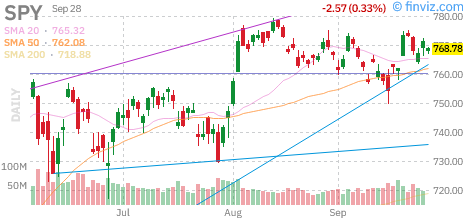
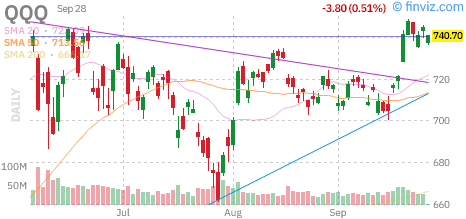
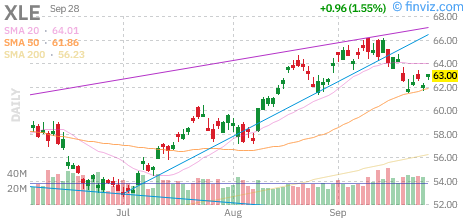
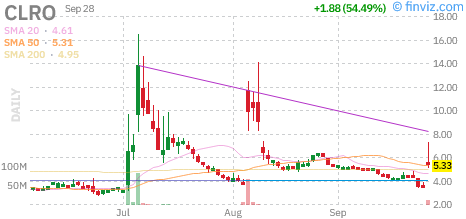
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
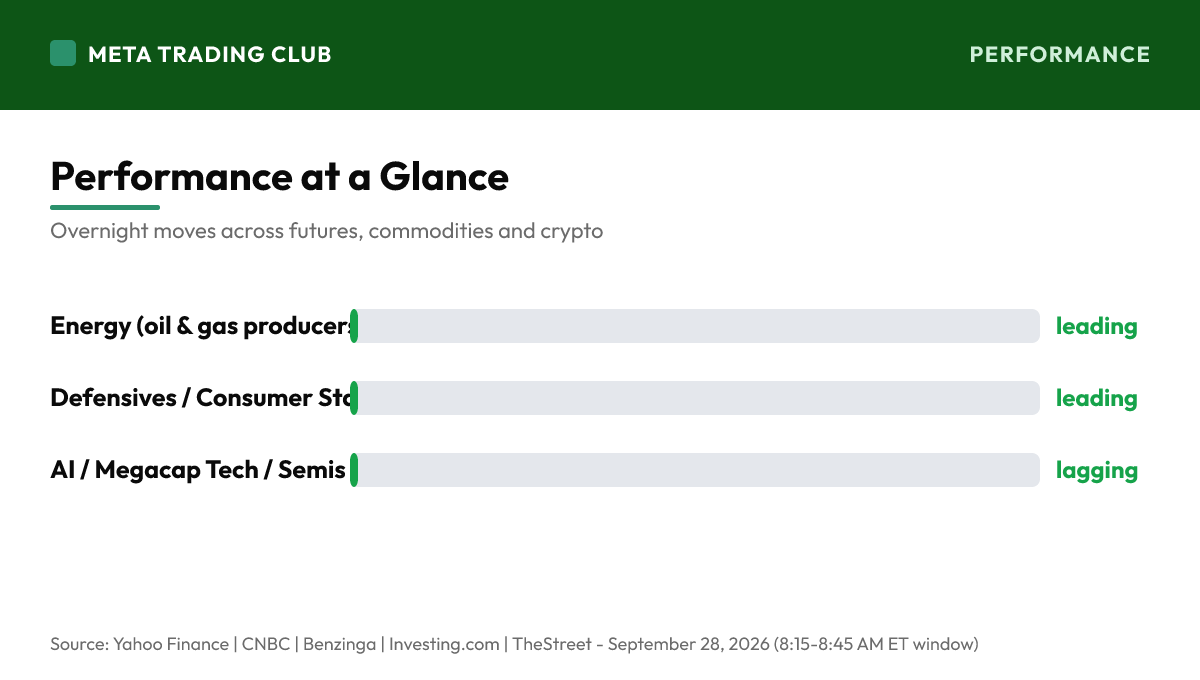
Performance at a Glance
Overnight & Global Markets
Friday was a clean weekly win — the Dow led with a 478-point, 0.93% gain to 51,828.62, the S&P 500 added 0.51% to 7,743.41, and the Nasdaq Composite rose 0.50% to 27,068.72, all shrugging off a mid-week bond sell-off. This morning the tape rotates. Futures are lower and split: Nasdaq-100 -1.05%, S&P 500 -0.54%, Dow -0.48%, Russell 2000 -0.70%. The driver is a two-part macro shock — WTI up roughly 4% above $96 after Trump rejected Iran’s war-ending proposal and a Hormuz deal, and the 10-year crossing 5.2%, a generational high. Higher oil and higher yields together drain the AI trade and the rate-sensitive corners while lifting energy: Meta is down about 3% giving back last week’s Muse-driven run, United Airlines and the carriers are lower on jet-fuel math, and Newmont is off more than 4% as gold falls 3%. This is a rotation, not a broad break — the Dow is holding up best because the money is moving toward energy and defensives. And it is all happening into the heaviest data week in a month: JOLTS Tuesday, ISM Manufacturing and core PCE Wednesday, ISM Services and the September jobs report Friday (Barclays sees +50,000), with a full slate of Fed speakers. Monday is a map day: mark 7,760 above, 7,700 as the pivot, and 7,660 below, and let the open and the data decide which way SPX resolves.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The week opens with a rotation driven by oil and yields. Every major index won last week and Friday closed green, but this morning futures are lower and split — Nasdaq-100 -1.05%, S&P -0.54%, Dow -0.48%, Russell -0.70%. WTI is up roughly 4% above $96 after President Trump rejected Iran’s proposal to end the war and pushed back on a Strait of Hormuz deal, and the 10-year has crossed 5.2%. Higher oil plus higher yields is draining the AI trade and the rate-sensitive corners while lifting energy. This is a reshuffle inside the market, not a broad break.
- The 10-year at 5.2% is the number that matters. A generational-high yield is the single biggest weight on the tape this morning — it’s why Meta and the AI names are selling off, why small caps are lagging, and why gold is down 3%. Rising yields drain high-multiple growth and non-yielding assets first. Into a week stacked with jobs data and Fed speakers, the direction of the 10-year decides whether this rotation deepens or stabilizes. Watch the bond market more closely than any single stock.
- This is the heaviest data week in a month. JOLTS lands Tuesday, ISM Manufacturing and core PCE Wednesday, then ISM Services and the September jobs report Friday, with Barclays looking for just 50,000 nonfarm payrolls after a soft summer. A full slate of Fed speakers — Barkin, Cook, Goolsbee, Kashkari, Williams, Barr, Waller — fills the gaps. The market is trading the rate path all week, and a weak jobs print into a 5.2% 10-year would be the tension that defines it.
Stock-Specific
- Meta (META) is the AI-trade tell. It’s down about 3% premarket, giving back part of last week’s roughly 13% run tied to its Muse personal-AI-agent news, as the whole AI complex sells off on the yield spike. When the strongest name of last week is the one leaking hardest this morning, treat it as the highest-beta read on rates — not a company-specific story. If Meta and the AI leaders stabilize after the open, the pullback has a floor; if they keep leaking, the tape has no leader.
- The airlines are feeling the oil math directly. United Airlines (UAL) and the other carriers are lower premarket as WTI’s 4% jump above $96 raises the jet-fuel bill — a clean, mechanical read-through from the Iran-driven oil premium. It’s the flip side of the energy rally: the same headline lifting oil producers is pressuring the fuel-sensitive names. Watch the airlines as a real-time gauge of how sticky the oil premium is; they’ll lead the relief if crude fades.
- Newmont (NEM) shows the yield squeeze on gold. It’s off more than 4% as the price of gold falls 3%, with a 5.2% 10-year raising the opportunity cost of holding a non-yielding asset. Gold falling in a risk-off tape is the counterintuitive tell that this is a yields story, not a fear story — when even the classic haven leaks under rising rates, it confirms the 10-year, not geopolitics, is in the driver’s seat this morning.
Global and Macro
- Oil is the geopolitical wildcard. WTI up roughly 4% above $96 on Trump’s rejection of Iran’s war-ending proposal and a Hormuz deal is the engine of the morning’s rotation. Higher crude lifts energy, pressures airlines and consumers, and feeds the inflation-and-yield loop that keeps the Fed cautious. If oil holds above $96 into the jobs week, it keeps upward pressure on the 10-year and on every rate-sensitive corner of the tape. This is the headline to watch through the session — it can reverse the whole rotation if it fades.
- The macro backdrop is higher-for-longer meeting a soft labor read. The 10-year at a generational high, oil firming, and a jobs report Friday that Barclays sees at just +50,000 sets up the week’s core tension: sticky inflation pressure from oil against a cooling labor market. That’s the hardest backdrop for the Fed and the tape — it argues against fast cuts while growth signals soften. The equity rotation this morning is the market starting to price that tension before the data confirms it.
TECHNICAL ANALYSIS
S&P 500 Key Levels
- The S&P closed Friday at 7,743.41 and futures point the open back under it, so the first battle is the 7,700 pivot. That round level is where the down open likely tests — hold above it and the rotation is orderly, a reshuffle rather than a break. Reclaiming 7,760 on the upside would say Friday’s strength is still intact and the oil-and-yield scare was a headfake. Don’t chase either direction into the open; let cash trade and see which side of 7,700 the tape defends before you commit.
- First support is 7,700, then 7,660 — the line that keeps the structure from unwinding toward 7,600. Lose 7,660 with the 10-year pressing over 5.2% and the AI trade still leaking, and the pullback turns into a real trend down, not a rotation. Above, 7,760 is the reclaim and 7,800 is the level that would say the rotation failed entirely. Mark 7,760 above and 7,660 below — inside is chop, outside is the real signal on whether the yield spike breaks the tape.
Sector and Sentiment
- The leadership tell this morning is energy up, AI down. Meta and the megacap tech names are leaking hardest while energy and defensives catch the rotation bid — the Dow holding up better than the Nasdaq is the proof this is a reshuffle, not a broad exit. For the pullback to stabilize, you want to see the AI leaders find a floor after the open. Until they do, treat index-level weakness as a rotation you trade tactically, not a trend to fade blindly.
- The VIX jumping 8.75% to 16.17 says the options market is waking up. It’s still a low absolute reading, but fear is being repriced off a complacent base right as a heavy data week begins. A rising VIX into JOLTS, ISM and Friday’s jobs report means the market is starting to pay for protection. Practically: respect that the calm can keep unwinding if the data disappoints, keep the 10-year on your screen, and let SPX prove its levels on real trade before you trust either side.
TODAY’S ECONOMIC CALENDAR
Key Releases (ET)
- Monday itself is light on data — the week’s weight is ahead. JOLTS job openings land Tuesday, ISM Manufacturing and August core PCE Wednesday, and the marquee prints — ISM Services and the September jobs report — hit Friday, with Barclays looking for just 50,000 nonfarm payrolls. That makes today a positioning day: the tape is setting up for the data, not reacting to it. Watch how the market carries the oil-and-yield rotation into the first real read, JOLTS, tomorrow morning.
- Fed speakers fill the calendar all week. Barkin, Cook, Goolsbee, Kashkari, Williams, Barr and Waller are all on the docket, and with the 10-year at a generational high, any hawkish nuance on the rate path will move yields — and yields are moving this tape. Let the rates reaction guide the read: if Fedspeak and the data lean toward higher-for-longer and the 10-year presses further over 5.2%, the rate-sensitive laggards leak more. If yields settle, the rotation gets a chance to stabilize.
Earnings Today
- The earnings calendar is quiet at the start of the week, which is why macro — oil, yields and the jobs data — dominates the tape. With no major single-name reports to anchor the session, the market is trading the rotation and the rate path, not corporate results. That leaves the AI trade’s stability as the key equity question: can the megacap names that led last week find a floor under a 5.2% 10-year, or does the yield spike keep capping them?
- Treat earnings as texture this week and trade the macro. The moves that matter are macro-driven — energy up on oil, airlines down on fuel, gold down on yields, AI down on rates. Where the earnings backdrop matters is as a check on whether growth can keep justifying multiples with the 10-year at a generational high. That’s the tension underneath the rotation, and Friday’s jobs report is the release most likely to resolve which way it breaks.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,760 — the reclaim. This is the level that says Friday’s strength is still intact and the oil-and-yield scare was a headfake. Reclaim it AND hold it with the AI names stabilizing and the tape opens the door back toward 7,800 and the highs. But futures point lower into a heavy data week, so don’t chase a bounce toward 7,760 unless breadth is confirming it. Make price take and hold the level on real strength before you trust the long side into the jobs report.
- SPX 7,700 — the pivot. The round level the down open likely tests, just under Friday’s 7,743 close. Hold above it and the rotation is orderly — a reshuffle inside the market rather than a break. This is the ‘let it prove itself’ zone where a rotating tape tends to chop as energy pulls up and AI pulls down. The real signal is which side SPX leaves 7,700 on as the session develops and the rates reaction sets in. Patience beats prediction inside the range.
- SPX 7,660 — the line that keeps the structure. Lose it with the 10-year pressing over 5.2% and the AI trade still leaking, and the pullback turns from a rotation into a real trend down toward 7,600. Below 7,660 the market is failing its test into the data week and the job flips toward capital preservation. This is the number that separates an orderly rotation from a rally giving itself back — mark it, and respect it if it goes.
Bull case: Oil’s premium fades, the 10-year settles back from 5.2%, and the AI names find a floor after the open. SPX reclaims 7,760 and works back toward 7,800, energy’s leadership broadens rather than coming at tech’s expense, and the market carries an orderly, two-way tape into Tuesday’s JOLTS. In this scenario the rotation was a healthy reshuffle, Friday’s weekly win still stands, and the yield spike gets treated as a scare that stabilized rather than a regime change into the jobs report.
Bear case: The oil premium sticks above $96, the 10-year presses further over 5.2%, and the AI trade keeps leaking. SPX loses the 7,700 pivot and then 7,660 into a give-back toward 7,600, small caps and gold miners keep leaking, and a weak JOLTS or a soft Friday jobs print confirms higher-for-longer against a cooling labor market. In this scenario Monday’s rotation was the front edge of a real pullback, and a generational-high 10-year finally caps the AI-led tape into the back half of the week.
Premarket Movers
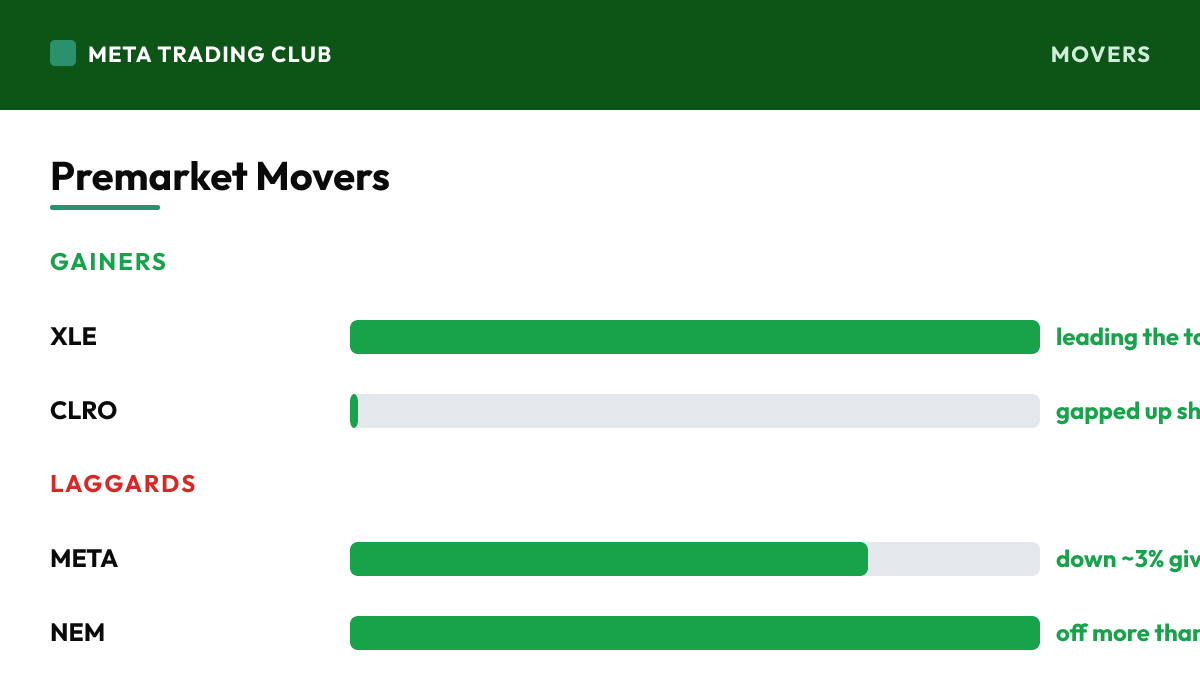
Gainers
| XLE | Energy Sector (oil & gas) | leading the tape as WTI jumps 4% above $96 on Iran tension | Energy is the one clearly green corner this morning as WTI runs roughly 4% above $96 on the Iran-Hormuz war premium. The whole complex is catching a rotation bid as money leaves high-multiple tech for the sector that benefits directly from higher crude. It’s the leadership of the day, but a macro- and headline-driven one — track it as a rotation tell, not a durable trend, because energy can lead a risk-off session and reverse fast if the oil premium fades. |
| CLRO | ClearOne | gapped up sharply premarket on heavy volume | One of the session’s biggest idiosyncratic premarket movers, gapping up hard on a volume spike. It’s a small-cap, single-name story with no read-through to the broad tape — the kind of isolated momentum move that shows up on a rotation morning while the index trades yields and oil. Mentioned as a notable mover, but treat it as texture: the market’s real story today is the macro rotation, not the small-cap gappers. |
Laggards
| META | Meta Platforms | down ~3% giving back last week’s run as the AI trade sells off | Down about 3% premarket, giving back part of last week’s roughly 13% run tied to its Muse personal-AI-agent news, as the whole AI complex sells off on the 10-year crossing 5.2%. It’s the AI-trade tell: when the strongest name of last week leaks hardest this morning, it’s a read on rates, not the company. If Meta and the megacap AI names stabilize after the open, the pullback has a floor; if they keep leaking, the tape has no leader to lean on. |
| NEM | Newmont | off more than 4% as gold falls 3% under a 5.2% 10-year | Down more than 4% as the price of gold falls 3%, with a generational-high 10-year raising the opportunity cost of holding a non-yielding asset. Gold leaking in a risk-off tape is the counterintuitive tell that this is a yields story, not a fear story — when even the classic haven falls under rising rates, it confirms the 10-year, not the Iran headline, is in the driver’s seat this morning. |
Risks Into the Open
- Primary risk: fading the rotation too early. Energy is up and AI is down, but this is a fast, macro-driven reshuffle, not a clean trend. The mistake is shorting the AI leaders into the hole or chasing energy at the highs without confirmation — a rotation this sharp can reverse hard if the oil premium fades or yields settle. Let SPX hold or lose 7,700 on real trade before you act, and watch whether the AI names find a floor after the open rather than assuming the leak continues.
- The 10-year over 5.2% is the ceiling risk for the week. A generational-high yield is draining the AI trade, the small caps and gold this morning, and it’s happening before the week’s real data. If JOLTS, ISM or Friday’s jobs report lean toward higher-for-longer and the 10-year presses further, the rate-sensitive corners leak more and even the megacap leadership can’t hold. The regime is still elevated rates — a push further over 5.2% puts the ceiling right back over the whole tape.
- Event risk is stacked into a single week. JOLTS Tuesday, ISM and core PCE Wednesday, ISM Services and the jobs report Friday, plus a full slate of Fed speakers — any one of them can whip the 10-year and the tape. The VIX jumping to 16.17 says the market is already starting to pay for protection. The risk is treating Monday’s quiet-on-data session as calm; it’s a positioning day into a gauntlet, and a weak jobs print into a 5.2% 10-year is exactly the surprise that isn’t fully priced.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Monday, September 28, 2026, S&P 500 futures are at 7,743.41 (+0.51%), with the VIX near 16.17. The stock market today is opening the week with a rotation, not a rally. Friday the tape finished green across the board — the Dow ran 478 points, or 0.93%, to 51,828.62, the S&P 500 added 0.51% to 7,743.41, and the Nasdaq Composite rose 0.50% to 27,068.72 — and every major index booked a weekly win. This morning that momentum flips. Futures are lower and the split is the tell: Nasdaq-100 futures are down about 1.05%, S&P 500 futures off 0.54%, Dow futures down 0.48%, and Russell 2000 futures off 0.70%. Tech is leading the way down while energy leads up. The reason is sitting in two places on the screen — the 10-year yield and the oil tape. WTI is up roughly 4% and back above $96 after President Trump rejected Iran’s proposal to end the war and pushed back on a Strait of Hormuz deal, adding a fresh war premium to crude. At the same time the 10-year has crossed 5.2%, a generational high, and rising yields are draining the same rate-sensitive and high-multiple corners that led Friday. Meta is down about 3% premarket, giving back part of last week’s 13% run on its Muse AI-agent news, as the whole AI trade sells off. United Airlines and the other carriers are lower on the jet-fuel math from higher oil. Newmont is off more than 4% as gold falls 3% under the weight of a 5.2% yield. That is the map: oil and defensives up, AI and rate-sensitive down. And it is happening into the most important week of data in a month — JOLTS Tuesday, ISM Manufacturing and core PCE Wednesday, then ISM Services and the September jobs report Friday, with Barclays looking for just 50,000 nonfarm payrolls. Layer in a full slate of Fed speakers — Barkin, Cook, Goolsbee, Kashkari, Williams, Barr, Waller — and you have a week that trades the rate path, not the headline. So Monday is a map day, not a chase day. Mark where the lines are before the data hits: SPX 7,700 is the pivot the open rotates around, 7,760 is the reclaim that says Friday’s strength is still intact, and 7,660 is the line that keeps the structure from unwinding toward 7,600. No alignment, no trade.
What is the biggest catalyst for the market today?
The week opens with a rotation driven by oil and yields. Every major index won last week and Friday closed green, but this morning futures are lower and split — Nasdaq-100 -1.05%, S&P -0.54%, Dow -0.48%, Russell -0.70%. WTI is up roughly 4% above $96 after President Trump rejected Iran’s proposal to end the war and pushed back on a Strait of Hormuz deal, and the 10-year has crossed 5.2%. Higher oil plus higher yields is draining the AI trade and the rate-sensitive corners while lifting energy. This is a reshuffle inside the market, not a broad break.
What key levels should traders watch today?
SPX 7,760 — the reclaim. This is the level that says Friday’s strength is still intact and the oil-and-yield scare was a headfake. Reclaim it AND hold it with the AI names stabilizing and the tape opens the door back toward 7,800 and the highs. But futures point lower into a heavy data week, so don’t chase a bounce toward 7,760 unless breadth is confirming it. Make price take and hold the level on real strength before you trust the long side into the jobs report. SPX 7,700 — the pivot. The round level the down open likely tests, just under Friday’s 7,743 close. Hold above it and the rotation is orderly — a reshuffle inside the market rather than a break. This is the ‘let it prove itself’ zone where a rotating tape tends to chop as energy pulls up and AI pulls down. The real signal is which side SPX leaves 7,700 on as the session develops and the rates reaction sets in. Patience beats prediction inside the range. SPX 7,660 — the line that keeps the structure. Lose it with the 10-year pressing over 5.2% and the AI trade still leaking, and the pullback turns from a rotation into a real trend down toward 7,600. Below 7,660 the market is failing its test into the data week and the job flips toward capital preservation. This is the number that separates an orderly rotation from a rally giving itself back — mark it, and respect it if it goes.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – September 28, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.