Tuesday, September 29, 2026 · 8:45 AM ET · MTC Market Intelligence
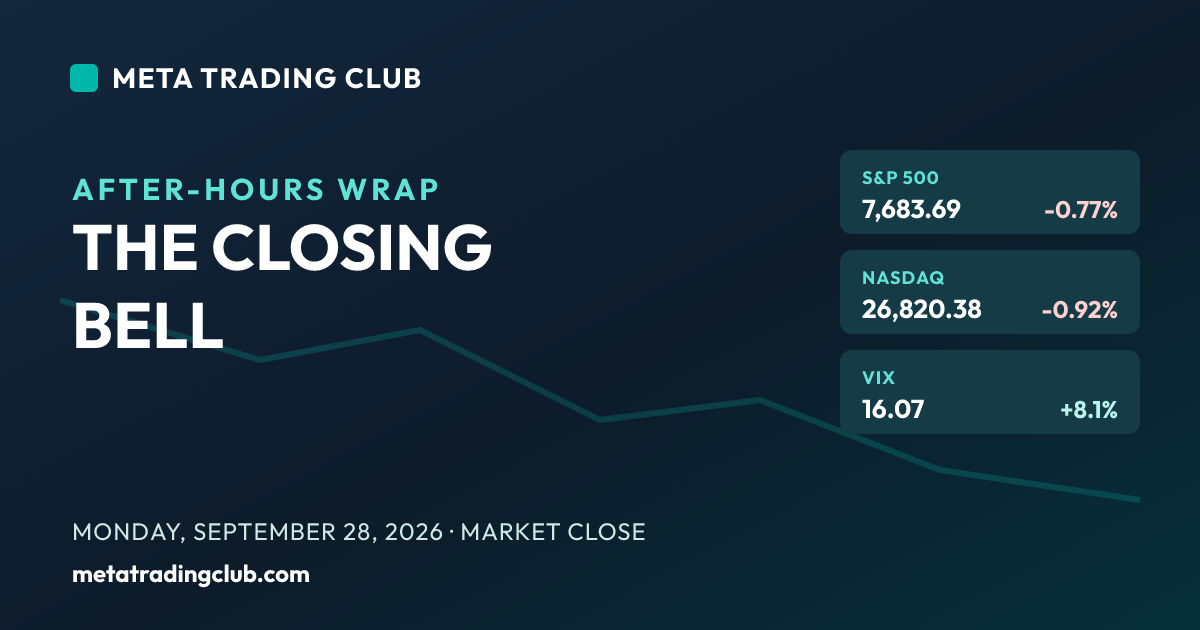
The stock market today is trying to bounce, but the reason matters more than the move. Monday the tape sold off across the board — the Dow dropped 347 points, or 0.67%, to 51,481.51, the S&P 500 slid 0.77% to 7,683.69, and the Nasdaq Composite fell 0.92% to 26,820.38 — as Treasury yields kept climbing to start the week. This morning futures are green: S&P 500 futures are up about 0.2%, Nasdaq-100 futures lead at roughly +0.4%, Russell 2000 futures are up about 0.14%, and only Dow futures are slightly lower. But look at what’s driving it. WTI is down about 1.7% and back near $91 after President Trump denied offering Iran sanctions relief — calling the reports a hoax — while Tehran signaled it’s ready for talks, deflating the war premium that spiked crude on Monday. Easing oil is letting the chips and megacap names catch a bid: Nvidia is regaining momentum premarket and Micron is up about 1.7% ahead of its report after Wednesday’s close. That’s the relief. Here’s the regime it’s happening inside: the Fed already raised rates 25 basis points this month — its first hike in three years — and the market is now pricing roughly a 70% chance of another hike at the October meeting, to 4-4.25%. The 10-year is holding near 5.24%, close to a generational high. So this is a relief bounce on easing oil, not a change in the rate story. And it runs straight into the first real data of the week: JOLTS job openings and September consumer confidence both land at 10:00 AM ET, ahead of ISM Manufacturing and core PCE Wednesday and the September jobs report Friday. That’s the lesson in the tape today — a green open after a red day is a reaction, not confirmation. It becomes real when price reclaims and holds the level it lost. SPX 7,700 is the pivot the open tests, 7,743 is the reclaim that undoes Monday’s damage, and 7,640 is the shelf that keeps the selloff from extending toward 7,600. No alignment, no trade.
Market Snapshot
| Instrument | Level | Change | Note |
|---|---|---|---|
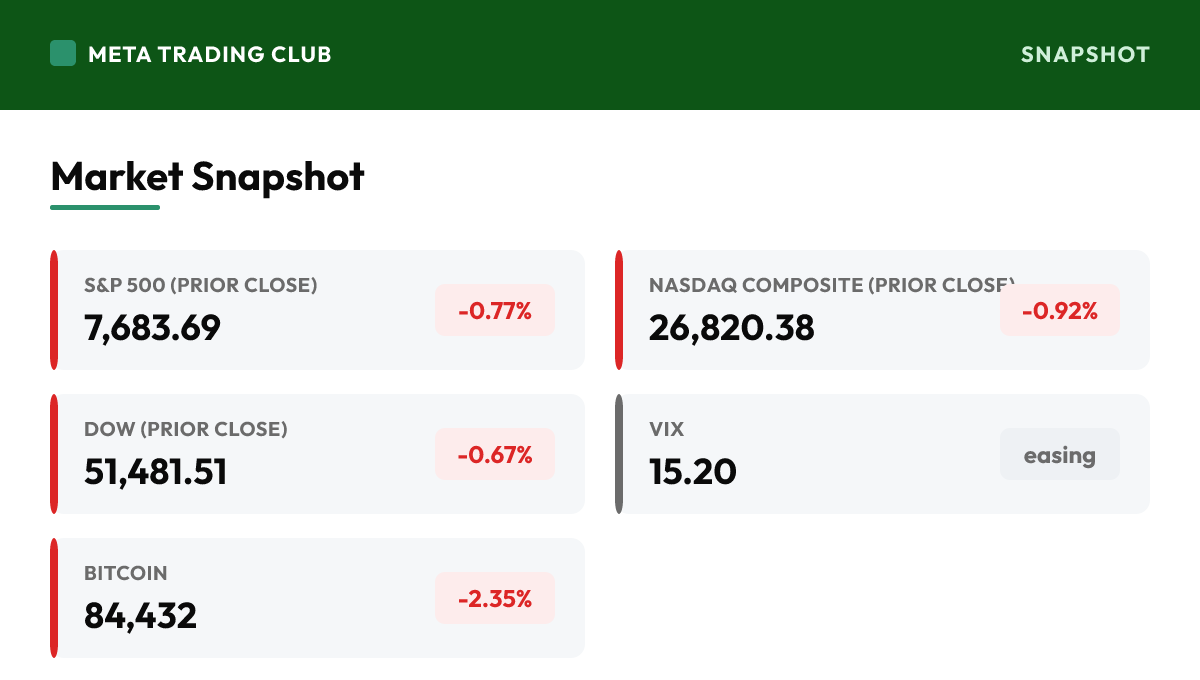
| S&P 500 (prior close) | 7,683.69 | -0.77% | Closed Monday at 7,683.69, down 0.77%, as rising Treasury yields pressured the tape all session. That close is the axis this morning: futures point back above it, so the first job of the open is whether cash can reclaim and hold 7,700, then 7,743. A red Monday into a green Tuesday is the classic setup where the relief looks convincing early — the level, not the futures print, tells you if it’s real. |
| Nasdaq Composite (prior close) | 26,820.38 | -0.92% | Fell 0.92% Monday to 26,820.38, the weakest major as high-multiple growth felt the yield spike first. This morning it’s the epicenter of the rebound — Nasdaq-100 futures lead the majors at about +0.4% as oil eases and the chips catch a bid. When the group that led down is the one bouncing hardest, treat it as the highest-beta read on whether the relief sticks, not proof the pressure is gone. |
| Dow (prior close) | 51,481.51 | -0.67% | Dropped 347 points Monday, off 0.67% to 51,481.51, as the blue chips leaked with the broad tape. This morning Dow futures are the one major slightly in the red while tech bounces — the mirror image of a rotation that keeps flipping. When the Dow lags a tech-led bounce, it says the move is being led by the same high-beta names that fell hardest, not by broad participation. |
| S&P 500 Futures | — | +0.20% | Up about 0.2% this morning, pointing the cash open back above Monday’s 7,683 close. Don’t over-read the exact print — the signal is that easing oil is letting the tape try to stabilize. Watch whether the index can reclaim and hold 7,700 once cash trades: the futures give you the direction, the reaction at the level tells you whether the bounce is a reaction or the start of a real recovery. |
| Nasdaq-100 Futures | — | +0.40% | Up about 0.4%, the strongest major as crude cools and the chips lead the rebound — Nvidia regaining momentum and Micron up about 1.7% ahead of Wednesday’s report. High-multiple growth bounces first when a headline pressure fades, but it’s also the first to roll over if yields press again. The Nasdaq is the tell: if the chips can hold their gains through the 10am data, the relief has legs. |
| Dow Futures | — | -0.10% | Down about 0.1%, the lone major slightly lower as money leans back into the tech and chip names that fell hardest Monday. The Dow lagging a tech-led bounce is the honest signal this morning: the rebound is narrow and high-beta, not broad. Watch whether participation widens through the open — if the Dow joins, the bounce is healthier; if it keeps lagging, the move is running on a thin group. |
| Russell 2000 Futures | — | +0.14% | Up about 0.14%, small caps trying to base after Monday’s leak as oil eases. But the most rate-sensitive corner of the market still trades under a 5.24% 10-year and a Fed that just hiked — a modest green print isn’t a green light. If the Russell can’t build on the bounce with the data still ahead, it says the market is still bracing for higher-for-longer, not betting on relief. |
| VIX | 15.20 | easing | Holding around 15 and easing back off Monday’s pop as crude cools and futures steady. It’s a low absolute reading, and the direction this morning says the options market is letting some of yesterday’s fear out. But a low VIX into a stacked data week — JOLTS and confidence today, ISM and PCE Wednesday, jobs Friday — is complacency to respect, not to trust. Calm can reprice fast if the 10am prints disappoint. |
| WTI Crude | 91.04 | -1.68% | Down about 1.7% and back near $91 after President Trump denied offering Iran sanctions relief, calling the reports a hoax, while Tehran signaled it’s ready for talks — deflating the war premium that spiked crude on Monday. This is the engine of the morning’s relief: cooling oil eases the inflation-and-yield pressure and lets the rate-sensitive tape breathe. If crude keeps rolling over, it takes some heat off the 10-year; if the Iran headline flips again, the whole bounce is at risk. |
| 10-Yr Yield | 5.24% | higher | Holding near 5.24%, close to a generational high, and the single most important number on the screen. The Fed already hiked 25 basis points this month and the market prices roughly a 70% chance of another hike in October — yields aren’t climbing on a fluke, they’re pricing a tightening Fed. Everything about this morning’s bounce is happening in spite of the 10-year, not because of it. Until yields ease, the ceiling stays over the rate-sensitive tape. |
| Bitcoin | 84,432 | -2.35% | Off about 2.4% near $84,430, leaking even as equities try to bounce — a reminder that with rates at a generational high, the highest-beta risk assets stay under pressure. Crypto slipping while stocks rebound is a split-tape signal: appetite is selective, not broad. Treat Bitcoin’s weakness as a caution flag on how much risk the market is really willing to carry into the week’s data, not as an all-clear. |
Charts to Watch
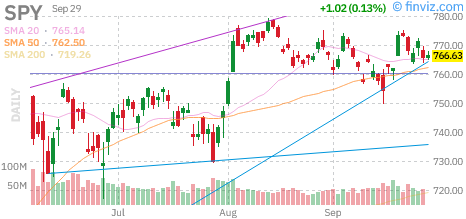
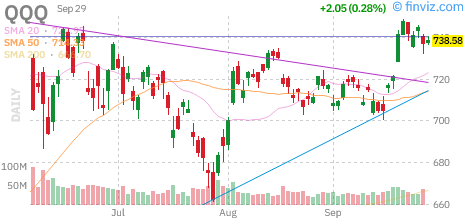
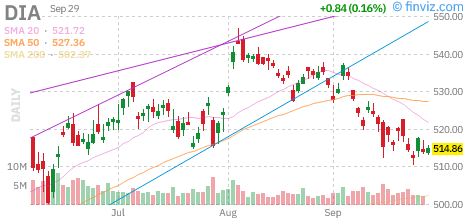
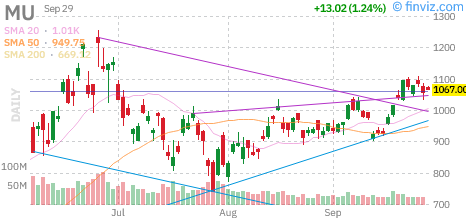
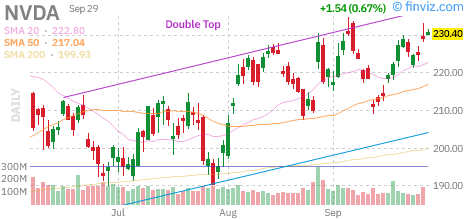
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
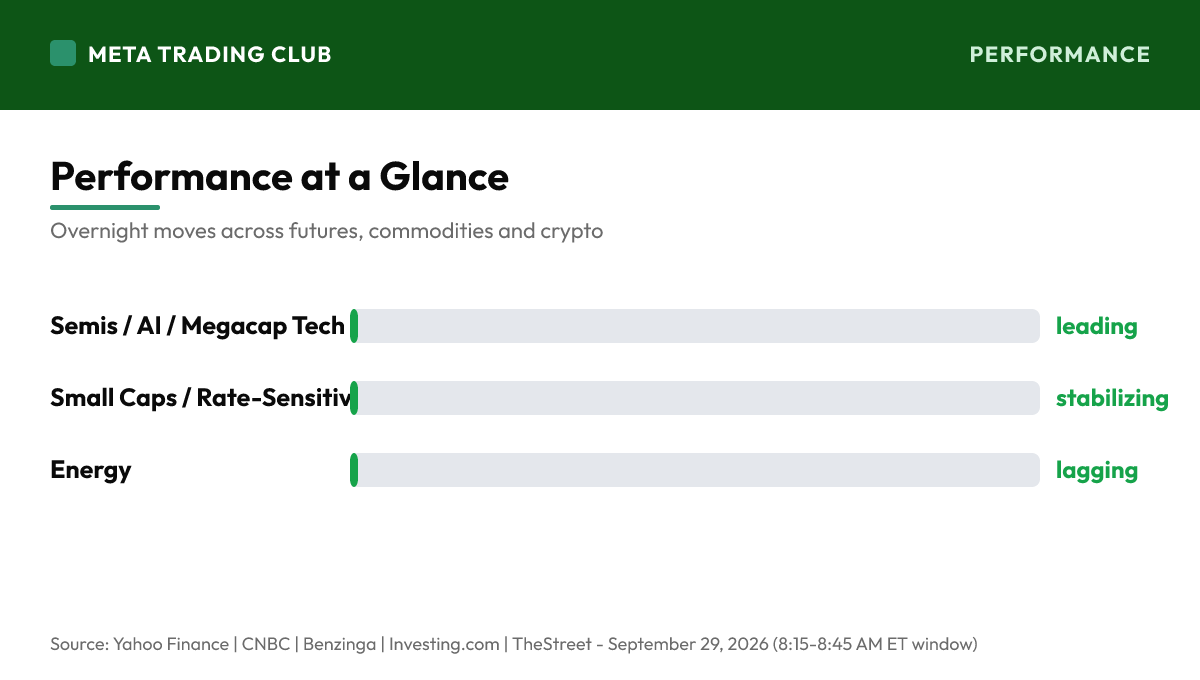
Performance at a Glance
Overnight & Global Markets
Monday was a clean risk-off session — the Dow fell 347 points, or 0.67%, to 51,481.51, the S&P 500 slid 0.77% to 7,683.69, and the Nasdaq Composite dropped 0.92% to 26,820.38, all pressured by Treasury yields climbing to start the week. This morning the tape bounces, and the split is the tell: Nasdaq-100 futures lead at about +0.4%, S&P 500 futures are up roughly 0.2%, Russell 2000 futures are up about 0.14%, and Dow futures are the lone major slightly lower. The driver is oil, not a change in the rate story — WTI is down about 1.7% back near $91 after Trump denied offering Iran sanctions relief and Tehran signaled openness to talks, deflating Monday’s war premium. Easing crude lets the chips lead the rebound: Nvidia is regaining momentum and Micron is up about 1.7% ahead of Wednesday’s report. But the regime hasn’t moved — the Fed hiked 25 basis points this month, the market prices roughly a 70% chance of another October hike, and the 10-year holds near 5.24%. This is a relief bounce on cooling oil, running straight into the first real data of the week: JOLTS job openings and September consumer confidence at 10:00 AM ET, ahead of ISM and core PCE Wednesday and the jobs report Friday. Today is a lesson in reaction versus confirmation: mark 7,743 above, 7,700 as the pivot, and 7,640 below, and let price prove whether the bounce is real before you trust it.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The tape bounces on easing oil, not a change in the rate story. Monday sold off as yields climbed; this morning futures are green — Nasdaq-100 +0.4%, S&P +0.2%, Russell +0.14%, with only Dow futures slightly lower — because WTI is down about 1.7% near $91. President Trump denied offering Iran sanctions relief, calling the reports a hoax, while Tehran signaled it’s ready for talks, deflating Monday’s war premium. Cooling crude is letting the chips and megacap names catch a bid. But the relief is narrow and high-beta — read it as a reaction, not confirmation the pressure is gone.
- The Fed is now the story under everything. The central bank raised rates 25 basis points this month — its first hike in three years — and the market prices roughly a 70% chance of another hike at the October meeting, to 4-4.25%. The 10-year is holding near 5.24%, close to a generational high. That’s why a green premarket doesn’t erase the risk: the regime is tightening, not easing. Watch the bond market more closely than any single stock — if yields press higher again, the rate-sensitive corners that led Monday down come right back under pressure.
- The first real data of the week hits at 10:00 AM ET. JOLTS job openings and the September consumer confidence reading both land this morning, ahead of ISM Manufacturing and core PCE Wednesday and the September jobs report Friday. That makes the bounce fragile: it’s running on an oil headline into a labor and confidence print that can reprice the rate path in seconds. Today is a positioning day — how the tape carries the relief into the 10am data is the first honest test of whether buyers actually want this level.
Stock-Specific
- The chips are the bounce tell. Nvidia (NVDA) is regaining momentum premarket and Micron (MU) is up about 1.7% ahead of its report after Wednesday’s close, leading the semis higher as oil eases. When the group that fell hardest Monday is the one bouncing first, treat it as the highest-beta read on risk appetite this morning. If the chips can hold their gains through the 10am data, the relief has a foundation; if they fade, the tech-led bounce has no anchor and the tape rolls back over.
- Nike (NKE) headlines the earnings tape, trading roughly flat premarket ahead of its report. It’s the marquee single-name read on the consumer into a session where September confidence data also lands — a useful cross-check on how the household is holding up with rates this high. Watch the guidance and the margin commentary more than the headline number; in a higher-for-longer tape, the read on demand and pricing power matters more than a one-quarter beat or miss.
- CarMax (KMX) and Concentrix (CNXC) report premarket, with Uranium Energy (UEC) also on the docket. CarMax is the cleaner macro read of the group — used-car demand and financing are directly rate-sensitive, so the commentary is a window into how a 5.24% 10-year is hitting the consumer’s big-ticket appetite. These aren’t tape-movers on their own, but they add texture to the day’s real question: whether demand is holding up as the Fed keeps tightening.
Global and Macro
- Oil is the swing factor again, just in the other direction. WTI down about 1.7% near $91 on Trump’s denial of Iran sanctions relief and Tehran’s openness to talks is the engine of the morning’s relief — cooling crude eases the inflation-and-yield loop that pressured the tape Monday. But this is a headline that has now moved the market both ways in 48 hours. If the Iran story flips again and crude re-spikes, the energy-up, tech-down rotation snaps right back. Watch oil as the real-time gauge of whether this bounce can hold.
- The macro backdrop is a tightening Fed meeting a data-heavy week. A 25bp hike already delivered, roughly 70% odds of another in October, and a 10-year near 5.24% set the tension: this is the first Fed hiking cycle in three years, and it’s colliding with JOLTS and confidence today, ISM and PCE Wednesday, and Friday’s jobs report. That’s the hardest backdrop for the tape — the market is pricing more tightening while it waits to see if the labor market is cracking. The equity bounce this morning is relief on oil, not a bet that the rate path has changed.
TECHNICAL ANALYSIS
S&P 500 Key Levels
- The S&P closed Monday at 7,683.69 and futures point the open back above it, so the first battle is the 7,700 pivot. That round level is where the green open likely tests — reclaim it and hold, and the bounce has a base. Push through to 7,743 — Friday’s close — and Monday’s damage is effectively undone, which is the level that turns a reaction into a real recovery. Don’t chase the gap up; let cash trade and prove it can hold 7,700 before you trust the long side into the 10am data.
- First support is 7,640 — the shelf just under Monday’s close that keeps the selloff from extending. Lose 7,640 with the 10-year near 5.24% and the chips fading, and the bounce fails and the tape opens toward 7,600. Above, 7,743 is the reclaim and 7,760 is the level that would say Monday was a one-day scare. Mark 7,743 above and 7,640 below — inside is chop, outside is the real signal on whether buyers or the yield ceiling win this morning.
Sector and Sentiment
- The leadership tell this morning is chips up, energy down — the exact reverse of Monday. Nvidia and Micron are leading the megacap bounce while energy gives back yesterday’s oil-driven gains. That flip in 24 hours is the proof of how headline-driven this tape is right now. For the bounce to be more than a reaction, you want to see participation widen beyond the chips — the Dow lagging says the move is still narrow. Trade it tactically off the levels, not as a trend you assume will hold.
- The VIX easing back toward 15 says the options market is letting some of Monday’s fear out — but a low VIX into a stacked data week is complacency, not calm. JOLTS and confidence at 10am, ISM and PCE Wednesday, jobs Friday: any one can reprice the rate path and wake volatility right back up. Practically: respect that the quiet can flip fast, keep the 10-year on your screen as the real driver, and let SPX prove its levels on real trade before you trust either side of the tape.
TODAY’S ECONOMIC CALENDAR
Key Releases (ET)
- The morning’s weight lands at 10:00 AM ET: JOLTS job openings for August and the September consumer confidence reading hit together. JOLTS is a direct read on labor demand and confidence gauges how the household is holding up with rates this high — both feed straight into the rate path the market is trading all week. Watch how the tape carries the oil-driven bounce into these prints; a soft labor read into a 5.24% 10-year is exactly the kind of surprise that can flip the morning’s relief in seconds.
- The rest of the week is stacked behind today. ISM Manufacturing and August core PCE land Wednesday, and the marquee prints — ISM Services and the September jobs report — hit Friday. With the Fed already hiking and roughly 70% odds priced for another October move, every one of these is a referendum on how much further the central bank goes. Let the rates reaction guide the read: if the data leans hot and the 10-year presses higher, the rate-sensitive laggards leak again; if it softens, the bounce gets room to build.
Earnings Today
- Nike (NKE) headlines the reports, with CarMax (KMX), Concentrix (CNXC) and Uranium Energy (UEC) also on the docket. Nike and CarMax are the useful macro reads — both are windows into consumer demand into a session where September confidence data also lands. In a higher-for-longer tape, the guidance and the demand commentary matter more than the headline number: the market wants to know whether the household is still spending with a 5.24% 10-year, not just whether the quarter beat.
- Treat earnings as texture and trade the macro today. The moves that matter are macro-driven — chips up on easing oil, energy down as crude cools, the whole tape hostage to the 10am data and the 10-year. Where earnings matter is as a check on whether demand can hold up as the Fed keeps tightening. That’s the tension underneath the bounce, and Friday’s jobs report is the release most likely to resolve which way it breaks.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,743 — the reclaim. This is Friday’s close and the level that turns this morning’s bounce from a reaction into a real recovery. Reclaim it AND hold it with the chips leading and the tape opens the door back toward 7,760 and higher. But futures are only modestly green on an oil headline into a data-heavy morning, so don’t chase a gap toward 7,743 unless breadth is confirming it. Make price take and hold the level on real strength before you trust the long side into the 10am prints.
- SPX 7,700 — the pivot. The round level the green open likely tests, just above Monday’s 7,683 close. Reclaim and hold it and the bounce has a base — a reaction that’s starting to earn confirmation. This is the ‘let it prove itself’ zone where a headline-driven tape tends to chop as oil pulls one way and yields pull the other. The real signal is which side SPX leaves 7,700 on once cash trades and the 10am data hits. Patience beats prediction inside the range.
- SPX 7,640 — the shelf that keeps the selloff contained. Lose it with the 10-year near 5.24% and the chips fading, and the bounce fails and the tape opens toward 7,600. Below 7,640 the market is rejecting the relief and the job flips toward capital preservation — a failed bounce after a red day is often the start of the next leg down, not a base. This is the number that separates a real recovery attempt from a dead-cat pop — mark it, and respect it if it goes.
Bull case: Oil keeps rolling over, the 10-year eases back from 5.24%, and the chips hold their bid through the 10am data. SPX reclaims 7,700 and pushes to 7,743, participation widens beyond the megacap names as the Dow joins, and a benign JOLTS and confidence read lets the market carry an orderly, two-way tape into Wednesday’s ISM and PCE. In this scenario the relief bounce earns its confirmation, Monday’s selloff was a one-day yield scare, and the tape stabilizes instead of rolling back over into the jobs report.
Bear case: The Iran headline flips and crude re-spikes, or the 10am data leans hot and the 10-year presses higher over 5.24%. SPX fails to hold 7,700, loses the 7,640 shelf, and opens toward 7,600 as the chips give back the bounce and the Dow keeps lagging. A soft labor read into a tightening Fed confirms higher-for-longer against a cooling economy — the hardest backdrop for the tape. In this scenario this morning’s green open was a reaction that never confirmed, and the yield ceiling caps the market right back into the week’s data.
Premarket Movers
Gainers
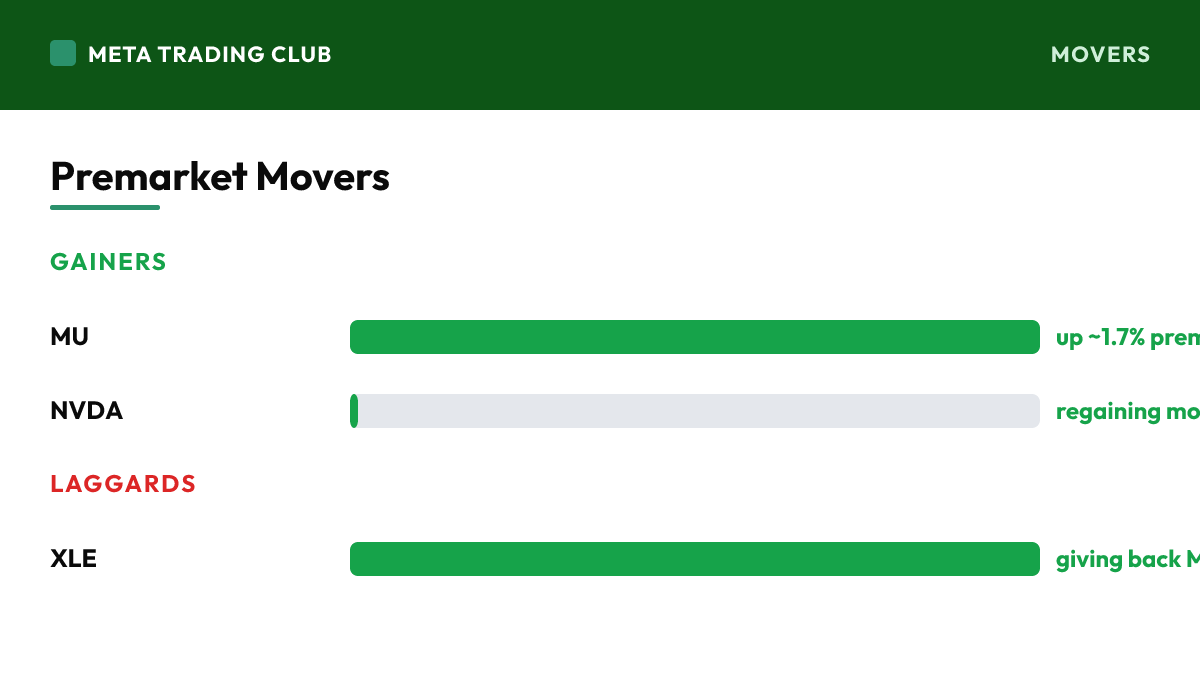
| MU | Micron Technology | up ~1.7% premarket ahead of Wednesday’s report, leading the chip rebound | Up about 1.7% premarket as the semis lead this morning’s bounce, with its own report due after Wednesday’s close adding a catalyst. Micron rising as oil eases is the high-beta tell on risk appetite — the chips fell hardest Monday and are bouncing first now. Watch whether it holds the gain through the 10am data: chip strength that sticks gives the tech-led bounce a foundation, while a fade would say the relief is running on air. |
| NVDA | Nvidia | regaining momentum premarket as easing oil lets the AI trade catch a bid | Regaining momentum this morning as cooling crude and steadier yields let the AI trade breathe after Monday’s leak. Nvidia is the epicenter of the megacap bounce — when it leads higher, the whole Nasdaq tends to follow, and when it rolls over, the tape has no leader. Treat it as the single best read on whether this morning’s relief has legs, and keep it on the screen against the 10-year all session. |
Laggards
| XLE | Energy Sector (oil & gas) | giving back Monday’s gains as WTI drops ~1.7% back near $91 | The reverse of Monday’s rotation. WTI down about 1.7% near $91 on Trump’s denial of Iran sanctions relief and Tehran’s openness to talks is pulling the energy complex lower — yesterday’s leader is today’s laggard. It’s the cleanest proof of how headline-driven this tape is: the same geopolitical story cuts both ways in 48 hours. Track energy as the swing tell — if the Iran headline flips again and crude re-spikes, this group leads and the tech bounce is at risk. |
Risks Into the Open
- Primary risk: trusting the bounce before it confirms. Futures are green on an oil headline, but the move is narrow — chips leading, the Dow lagging — and it runs straight into the 10am data. The mistake is chasing the gap up as if the pressure is gone. A relief bounce after a red day can fade the second the Iran story flips or JOLTS disappoints. Let SPX reclaim and hold 7,700 on real trade before you act, and watch whether the chips keep their bid rather than assuming the recovery is underway.
- The 10-year near 5.24% is the ceiling risk for the week. The Fed already hiked this month and the market prices roughly 70% odds of another October move — this is a tightening cycle, and yields aren’t climbing on a fluke. The whole bounce is happening in spite of the rate story, not because of it. If today’s data or the week’s ISM and jobs prints lean hot and the 10-year presses higher, the rate-sensitive corners leak again and even the chip leaders can’t hold. The regime is elevated-and-rising rates — respect the ceiling.
- Event risk is front-loaded into today and stacked all week. JOLTS and confidence at 10am, ISM and core PCE Wednesday, ISM Services and the jobs report Friday — any one can whip the 10-year and the tape. The VIX easing toward 15 says the market is already relaxing off Monday’s fear, which is exactly the complacency that gets punished by a surprise. The risk is treating this bounce as calm; it’s a headline-driven relief move into a data gauntlet, and a hot or soft print into a 5.24% 10-year is the surprise that isn’t fully priced.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Tuesday, September 29, 2026, S&P 500 futures are at 7,683.69 (-0.77%), with the VIX near 15.20. The stock market today is trying to bounce, but the reason matters more than the move. Monday the tape sold off across the board — the Dow dropped 347 points, or 0.67%, to 51,481.51, the S&P 500 slid 0.77% to 7,683.69, and the Nasdaq Composite fell 0.92% to 26,820.38 — as Treasury yields kept climbing to start the week. This morning futures are green: S&P 500 futures are up about 0.2%, Nasdaq-100 futures lead at roughly +0.4%, Russell 2000 futures are up about 0.14%, and only Dow futures are slightly lower. But look at what’s driving it. WTI is down about 1.7% and back near $91 after President Trump denied offering Iran sanctions relief — calling the reports a hoax — while Tehran signaled it’s ready for talks, deflating the war premium that spiked crude on Monday. Easing oil is letting the chips and megacap names catch a bid: Nvidia is regaining momentum premarket and Micron is up about 1.7% ahead of its report after Wednesday’s close. That’s the relief. Here’s the regime it’s happening inside: the Fed already raised rates 25 basis points this month — its first hike in three years — and the market is now pricing roughly a 70% chance of another hike at the October meeting, to 4-4.25%. The 10-year is holding near 5.24%, close to a generational high. So this is a relief bounce on easing oil, not a change in the rate story. And it runs straight into the first real data of the week: JOLTS job openings and September consumer confidence both land at 10:00 AM ET, ahead of ISM Manufacturing and core PCE Wednesday and the September jobs report Friday. That’s the lesson in the tape today — a green open after a red day is a reaction, not confirmation. It becomes real when price reclaims and holds the level it lost. SPX 7,700 is the pivot the open tests, 7,743 is the reclaim that undoes Monday’s damage, and 7,640 is the shelf that keeps the selloff from extending toward 7,600. No alignment, no trade.
What is the biggest catalyst for the market today?
The tape bounces on easing oil, not a change in the rate story. Monday sold off as yields climbed; this morning futures are green — Nasdaq-100 +0.4%, S&P +0.2%, Russell +0.14%, with only Dow futures slightly lower — because WTI is down about 1.7% near $91. President Trump denied offering Iran sanctions relief, calling the reports a hoax, while Tehran signaled it’s ready for talks, deflating Monday’s war premium. Cooling crude is letting the chips and megacap names catch a bid. But the relief is narrow and high-beta — read it as a reaction, not confirmation the pressure is gone.
What key levels should traders watch today?
SPX 7,743 — the reclaim. This is Friday’s close and the level that turns this morning’s bounce from a reaction into a real recovery. Reclaim it AND hold it with the chips leading and the tape opens the door back toward 7,760 and higher. But futures are only modestly green on an oil headline into a data-heavy morning, so don’t chase a gap toward 7,743 unless breadth is confirming it. Make price take and hold the level on real strength before you trust the long side into the 10am prints. SPX 7,700 — the pivot. The round level the green open likely tests, just above Monday’s 7,683 close. Reclaim and hold it and the bounce has a base — a reaction that’s starting to earn confirmation. This is the ‘let it prove itself’ zone where a headline-driven tape tends to chop as oil pulls one way and yields pull the other. The real signal is which side SPX leaves 7,700 on once cash trades and the 10am data hits. Patience beats prediction inside the range. SPX 7,640 — the shelf that keeps the selloff contained. Lose it with the 10-year near 5.24% and the chips fading, and the bounce fails and the tape opens toward 7,600. Below 7,640 the market is rejecting the relief and the job flips toward capital preservation — a failed bounce after a red day is often the start of the next leg down, not a base. This is the number that separates a real recovery attempt from a dead-cat pop — mark it, and respect it if it goes.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – September 29, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.