Monday, October 19, 2026 · 8:45 AM ET · MTC Market Intelligence
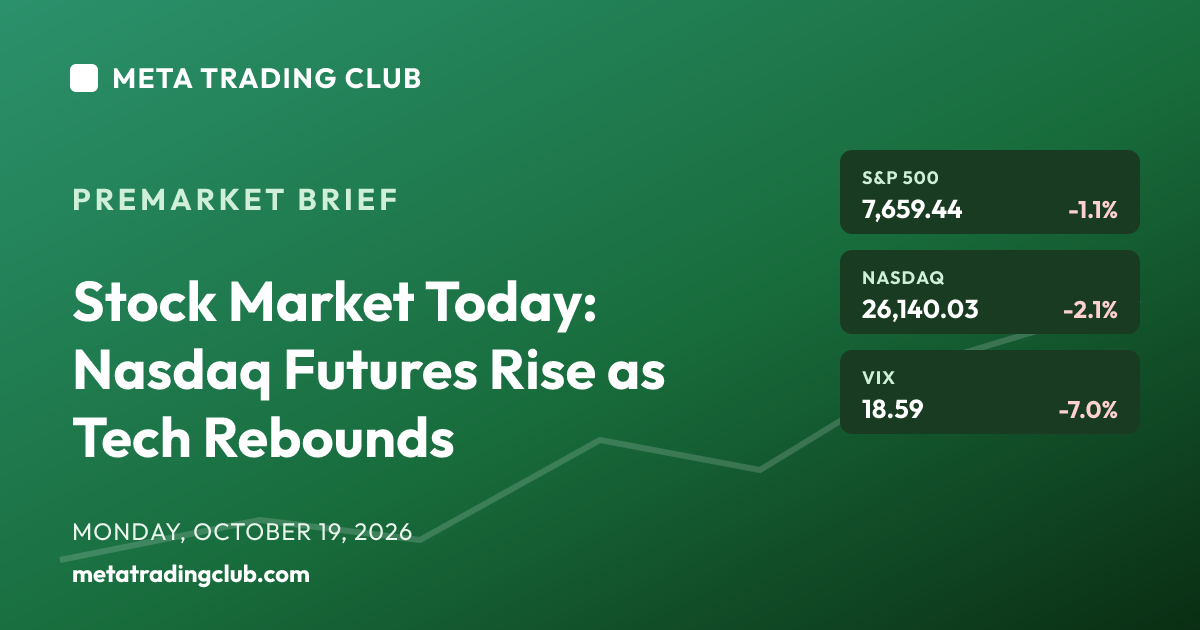
The stock market today is trying to bounce back from a bruising week — and the whole read is whether this is a real reclaim or a relief pop into the biggest earnings week of the quarter. Friday closed ugly: the Nasdaq Composite dropped 2.1% to 26,140.03, the S&P 500 fell 1.1% to 7,659.44, and the Dow slipped 0.34% to 52,002.41, capping the Nasdaq’s worst week since June as investors bailed on AI and chip names over doubts about capex and returns. This morning the tape flips: Nasdaq futures lead, up about 1.1%, S&P 500 futures are higher around +0.49%, and Dow futures sit essentially flat, down about 0.05%. The leadership reversal is the tell — last week value held up while tech got hit; today the dip-buyers are back in the exact names that got hammered. Chips are driving it: Intel is up about 4% after a JPMorgan upgrade to neutral, Micron is up about 3% as memory rebounds, and Datadog is up about 3% on a Bernstein upgrade. Cleveland-Cliffs leads the tape, up more than 10% on a clean earnings beat. Two things are helping risk appetite heal: the 10-year has eased to about 5.08%, backing off its recent 5.3% peak, and the VIX has cooled to roughly 18.6 from Friday’s 19.98 as oil slides on eased Russia sanctions. But this is a quiet-catalyst Monday hiding a loud week. The Fed is in its pre-meeting blackout from October 17 to 29, so no officials speak, and the only data today is the NAHB Housing Market Index at 10:00 AM ET. The real event is earnings: 70 S&P 500 companies report this week, headlined by Netflix and GM on Tuesday and the main event — Meta and Tesla, plus IBM, Lam Research and Texas Instruments — Wednesday after the close. That’s when the AI trade gets graded. Mark SPX 7,700 as the first reclaim level above Friday’s close, 7,660 as the pivot the bounce has to defend, and 7,590 as the deeper floor that decides whether the selloff is over or just paused. A bounce isn’t a trend until the level holds. No alignment, no trade.
Market Snapshot
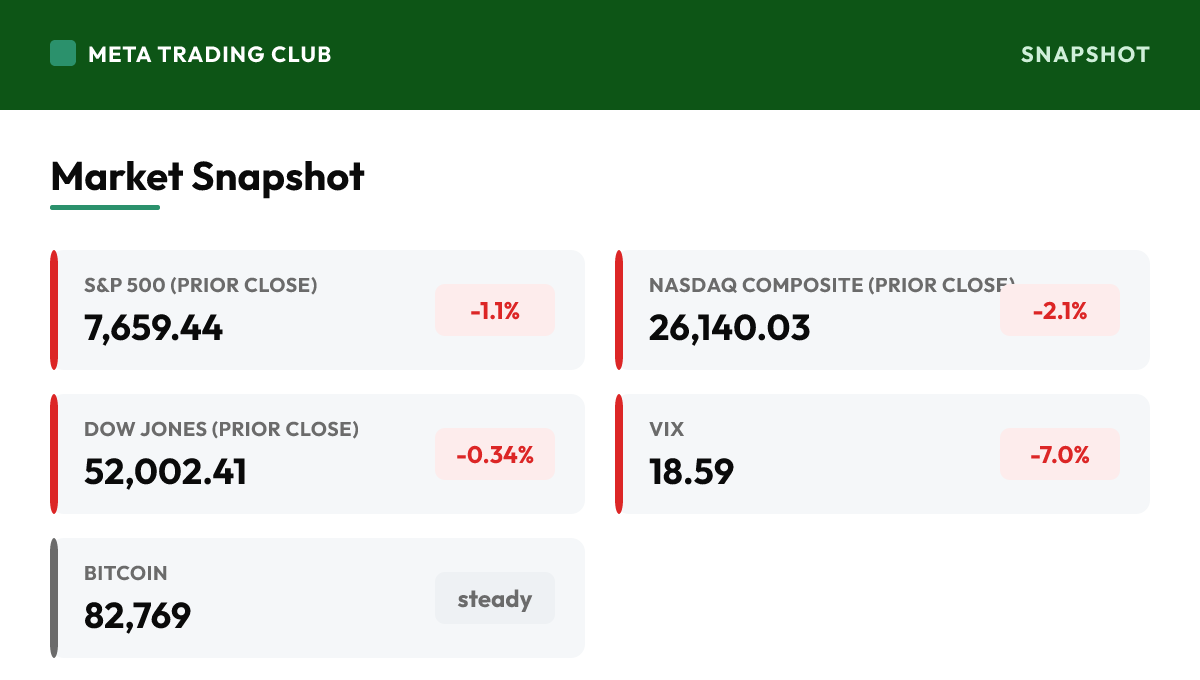
| Instrument | Level | Change | Note |
|---|---|---|---|
| S&P 500 (prior close) | 7,659.44 | -1.1% | Fell 84.62 points, or 1.1%, Friday to 7,659.44 as the AI selloff dragged the index to its worst week since June. This morning S&P 500 futures are up about 0.49% — a solid bounce, but it has to prove itself. The level that matters is 7,700: the first reclaim above Friday’s close that would say buyers are back in control. Below that, 7,660 is the pivot the bounce must defend; lose it and fail to reclaim and this is a relief pop, not a turn. Let the index hold the level before you trust the rebound. |
| Dow Jones (prior close) | 52,002.41 | -0.34% | The most resilient of the three Friday — down just 0.34% to 52,002.41 while tech got crushed, holding the 52,000 line. This morning Dow futures are essentially flat, down about 0.05%, and that is the tell: today’s bid is in tech, not blue chips. Last week value held while growth sold off; today the leadership reverses. A Dow that idles while the Nasdaq rips is the opposite of last week’s tape — watch whether the rotation back into growth has staying power or fades into the open. |
| Nasdaq Composite (prior close) | 26,140.03 | -2.1% | The epicenter of the damage — down 572.99 points, or 2.1%, Friday to 26,140.03 as investors dumped AI and chip names on capex and return-on-investment doubts, sealing the worst week since June. This morning Nasdaq futures lead, up about 1.1%, as Intel, Micron and the memory names bounce. This is the whole question of the day: is the chip rebound real demand returning, or oversold dip-buyers front-running Wednesday’s Meta and Tesla prints? The group that led the decline now has to lead the repair — and earnings, not futures, settle it. |
| Russell 2000 (prior close) | — | N/A | Small caps are the risk-appetite gauge today. With the 10-year easing back to about 5.08% off its 5.3% peak, the Russell’s heavy borrowing-cost burden gets a little lighter, so watch whether it joins the tech bounce or lags. A Russell that leads says the market believes rates have topped and risk is genuinely healing; a Russell that drags says the bounce is narrow and chip-specific, not broad. Treat it as the breadth tell that tells you whether this is a real turn or a one-sector pop. |
| VIX | 18.59 | -7.0% | Cooled about 7% to 18.59 from Friday’s 19.98 close as futures stabilized and the panic bid drained out of the tape. That’s a meaningful drop, but 18.6 is still elevated — the market isn’t calm, it’s catching its breath ahead of a huge earnings week. Watch for a push back above 20 if Wednesday’s Meta or Tesla prints disappoint, or a slide under 17 if the chip bounce holds and earnings cooperate. A VIX in the high teens says uncertainty, not resolution: respect that the tape can still whip. |
| WTI Crude | — | lower | Sliding lower this morning as President Trump eased sanctions on Russian oil, loosening the supply picture and pulling crude off its recent highs. Oil coming down is a quiet tailwind for the inflation story — softer energy takes a little pressure off headline CPI and, by extension, off the yield picture. It’s not today’s driver, but it fits the morning’s risk-on shape: easing oil, easing yields, and a bid back into growth. Treat crude as a supportive cross-check on the rate narrative rather than the main event. |
| 10-Yr Treasury | 5.08% | easing | Easing to about 5.08%, backing off a recent peak near 5.3%, and that retreat is a big part of why risk is bid this morning. A lower 10-year loosens the lid on growth and the most rate-sensitive AI names — the same names that got hit last week. As long as yields keep drifting lower, the tech bounce has a tailwind; a reversal back toward 5.3% would tighten the screws again and threaten the rebound. Watch the 10-year as the referee on whether the chip bid can hold through the week. |
| Bitcoin | 82,769 | steady | Trading near $82,769 ahead of the open as the yield retreat and firmer stock futures steadied risk appetite. Crypto’s tone tracks the broader bounce — when yields ease and equity futures rise, the risk-on bid reaches Bitcoin too. But like the equity rebound, it’s tentative: a reclaim and hold back above $85K would say risk appetite is genuinely healing into earnings week, while a slide back under $80K would flag that last week’s caution hasn’t fully cleared. A steadying read, not an all-clear. |
Charts to Watch
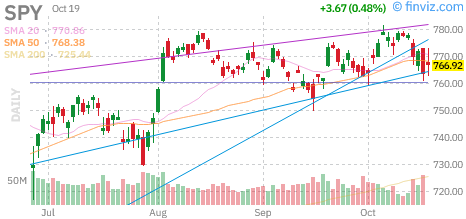
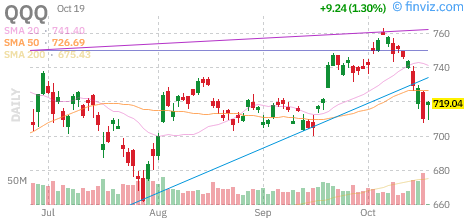
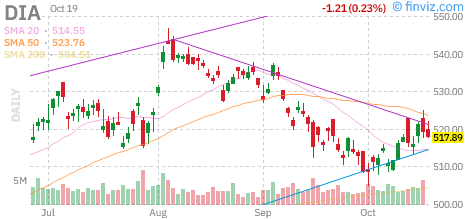
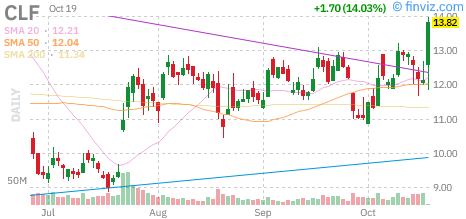
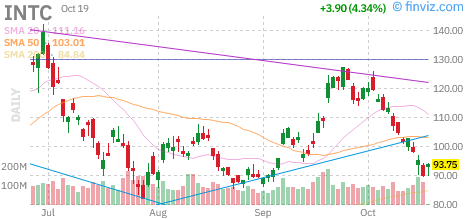
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
Overnight & Global Markets
Friday closed the book on an ugly week: the Nasdaq Composite dropped 572.99 points (-2.1%) to 26,140.03, the S&P 500 fell 84.62 (-1.1%) to 7,659.44, and the Dow slipped 175.28 (-0.34%) to 52,002.41, with both the S&P and Nasdaq posting their worst week since June as investors bailed on AI and chip names over doubts about the sector’s massive capex and returns. This morning the tape reverses: Nasdaq futures lead, up about 1.1%, S&P 500 futures are up about 0.49%, and Dow futures are essentially flat, down about 0.05%. The leadership flip is the story — the group that led the decline is leading the repair. Chips are driving it: Intel is up about 4% on a JPMorgan upgrade to neutral (CEO Lip-Bu Tan’s execution cited), Micron is up about 3% as memory rebounds, and Datadog is up about 3% on a Bernstein upgrade to outperform. Cleveland-Cliffs leads the whole tape, up more than 10% after beating on earnings (28 cents vs. a 21-cent estimate). Two tailwinds are helping: the 10-year has eased to about 5.08% off a 5.3% peak, and the VIX has cooled to about 18.6 from Friday’s 19.98, with oil sliding as Trump eased Russia sanctions. But this is a quiet Monday ahead of a loud week. The Fed is in blackout (Oct 17-29), so no officials speak, and the only data is the NAHB Housing Market Index at 10:00 AM ET. The real event is earnings: 70 S&P 500 companies report this week, headlined by Netflix and GM Tuesday and the main event — Meta, Tesla, IBM, Lam Research and Texas Instruments — Wednesday after the close. Mark SPX 7,700 as the first reclaim, 7,660 as the pivot to defend, and 7,590 as the deeper floor. A bounce isn’t a trend until the level holds. No alignment, no trade.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The tape is bouncing back from its worst week since June, and the leadership flip is the whole read. Last week value held while AI and chip names got dumped on capex and return-on-investment doubts; this morning Nasdaq futures lead up about 1.1% while Dow futures sit flat. Chips are driving it — Intel up about 4% on a JPMorgan upgrade to neutral, Micron up about 3% on a memory rebound, Datadog up about 3% on a Bernstein upgrade. The group that led the decline is leading the repair. The question is whether that’s real demand returning or oversold dip-buyers front-running Wednesday’s earnings. Futures don’t answer it; the numbers do.
- Two tailwinds are helping risk appetite heal. The 10-year has eased to about 5.08%, backing off a recent 5.3% peak, which loosens the lid on the rate-sensitive growth names that got hit hardest. And the VIX has cooled to about 18.6 from Friday’s 19.98 as oil slides — President Trump eased sanctions on Russian oil, loosening the supply picture and pulling crude lower, which is a quiet tailwind for the inflation story. Easing oil, easing yields, and a bid back into growth is a coherent risk-on shape — but 18.6 on the VIX is still elevated, so respect that the tape can whip into a heavy earnings week.
- This is a quiet-catalyst Monday hiding a loud week. The Fed is in its pre-meeting blackout from October 17 to 29, so no officials speak, and the only data today is the NAHB Housing Market Index at 10:00 AM ET. The real event is earnings: 70 S&P 500 companies report this week, headlined by Netflix and GM on Tuesday and the main event — Meta and Tesla, plus IBM, Lam Research and Texas Instruments — Wednesday after the close. That’s when the AI trade actually gets graded. Next week brings Q3 GDP, September PCE and the FOMC decision on October 27-28. Don’t over-trade a thin-catalyst Monday into a week where Wednesday night decides the tone.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,700 — the first reclaim. This is the level just above Friday’s 7,659.44 close that the bounce has to take and hold to say buyers are genuinely back in control, not just covering shorts. Futures point to an open testing this zone, so don’t chase the gap into 7,700 on an oversold open — make the market prove it can hold above it on real volume before you trust the long. A rebound that stalls right at 7,700 and rolls over is exactly where relief-rally chasers get trapped ahead of earnings week. Let the index earn the reclaim; don’t predict it.
- SPX 7,660 — the pivot the bounce must defend. This is Friday’s closing area and the bull/bear line for the day: hold above it and the rebound stays intact and can work toward 7,700; lose it and fail to reclaim and this morning’s green is a relief pop fading, not a turn. On a bounce tape the index can gap up and then drift, so trust strength only if 7,660 holds as support on the first pullback. The real signal is which side of this pivot SPX settles on once the opening surge cools — a hold builds the case for the rebound, a loss warns the selloff isn’t finished.
- SPX 7,590 — the deeper floor. The must-hold support below the pivot, and the level that decides whether a failed bounce is a quick shakeout or the resumption of last week’s selloff. If the chip bid fades and yields reverse back toward 5.3%, 7,590 is where dip-buyers have to step up to keep the larger structure intact. Lose 7,590 and the tape is no longer ‘rebound in progress’ — it’s ‘the worst week since June has a sequel,’ and that’s a heavier game into Wednesday’s earnings. Mark it, respect it, and let price confirm. Don’t guess the bottom; let the level tell you whether the weakness is a dip or a trend.
Premarket Movers
Gainers
| CLF | Cleveland-Cliffs | up more than 10% premarket on a clean Q3 earnings beat | Leading the whole tape, up more than 10% after beating on earnings (28 cents vs. a 21-cent estimate). This is a catalyst-driven move on real numbers, not a tape move — Cleveland-Cliffs is rising on its own print while the broader bounce plays out around it. Treat it as a single-stock story and trade it on its own levels: a double-digit earnings gap can give back fast if the market fades the move, so let the stock prove the pop holds rather than chasing the headline into the open. It’s also a useful breadth tell — old-economy names with real beats getting rewarded says capital is rotating back into risk, not just chasing beaten-down chips. |
| INTC | Intel | up about 4% premarket on a JPMorgan upgrade to neutral | Up about 4% this morning after JPMorgan lifted the chipmaker to neutral from underweight, citing better execution under CEO Lip-Bu Tan. It’s one of the names driving the semiconductor bounce that’s leading the whole tape, so read it as both a single-stock upgrade story and a tell on the group. An analyst upgrade is a sentiment catalyst, not a fundamental shift, so don’t confuse a broker’s rating change with a turn in the business — trade the reaction and the level, not the upgrade headline. If the chip bid holds into the open, Intel’s move adds credibility to the rebound; if it fades, the whole semi bounce is on watch. |
Laggards
| MU | Micron | a rebound name to watch rather than a decliner — up about 3% premarket | Not a loser this morning — up about 3% as memory and storage names rebound after last week’s rout — but it is the name to watch as the swing factor for the whole chip bounce. Micron led the memory selloff and is now leading the memory repair, which makes it the cleanest read on whether the semiconductor bid is real demand returning or just an oversold snapback. Trade it on its own levels and treat it as the barometer for the group: if Micron holds its gains into the open and through the week, the chip rebound has legs; if it rolls over, the whole AI-and-memory bounce is suspect heading into Wednesday’s earnings. |
Risks Into the Open
- Primary risk today: chasing the bounce before it proves itself. After the worst week since June, a green futures tape makes you want to pile back into the chips that got hammered. But a relief bounce during an unresolved AI-doubt narrative traps the people who chase it — futures bouncing doesn’t answer the capex-and-returns questions that caused the selloff. The discipline is to let SPX reclaim 7,700 and hold 7,660 before you trust the turn. A bounce isn’t a trend until the level holds, and a big green gap after a bad week is a reaction, not a resolution.
- The structural risk is Wednesday, not today. This is a quiet-catalyst Monday — Fed in blackout, only the NAHB index on the data card — sitting in front of the biggest earnings week of the quarter. Meta and Tesla report Wednesday after the close, alongside IBM, Lam Research and Texas Instruments, and that’s when the AI trade actually gets graded. The trap is building a big position on a thin-catalyst Monday and getting caught offside when Wednesday night resets the tone. Keep size honest early in the week and let the real event come to you rather than pre-positioning for it.
- The company-specific risk is trading the chip bounce as a group instead of name by name. Intel is up on an upgrade, Micron on a memory rebound, Cleveland-Cliffs on an actual earnings beat — three different catalysts, three different qualities of move. An analyst upgrade is sentiment; an earnings beat is a number. Don’t lump them together and assume the whole complex is healthy. Price each name on its own catalyst and its own level, and watch whether the semis can hold their gains into the open as the real tell on breadth. Confirmation over conviction, especially on a bounce.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Monday, October 19, 2026, S&P 500 futures are at 7,659.44 (-1.1%), with the VIX near 18.59. The stock market today is trying to bounce back from a bruising week — and the whole read is whether this is a real reclaim or a relief pop into the biggest earnings week of the quarter. Friday closed ugly: the Nasdaq Composite dropped 2.1% to 26,140.03, the S&P 500 fell 1.1% to 7,659.44, and the Dow slipped 0.34% to 52,002.41, capping the Nasdaq’s worst week since June as investors bailed on AI and chip names over doubts about capex and returns. This morning the tape flips: Nasdaq futures lead, up about 1.1%, S&P 500 futures are higher around +0.49%, and Dow futures sit essentially flat, down about 0.05%. The leadership reversal is the tell — last week value held up while tech got hit; today the dip-buyers are back in the exact names that got hammered. Chips are driving it: Intel is up about 4% after a JPMorgan upgrade to neutral, Micron is up about 3% as memory rebounds, and Datadog is up about 3% on a Bernstein upgrade. Cleveland-Cliffs leads the tape, up more than 10% on a clean earnings beat. Two things are helping risk appetite heal: the 10-year has eased to about 5.08%, backing off its recent 5.3% peak, and the VIX has cooled to roughly 18.6 from Friday’s 19.98 as oil slides on eased Russia sanctions. But this is a quiet-catalyst Monday hiding a loud week. The Fed is in its pre-meeting blackout from October 17 to 29, so no officials speak, and the only data today is the NAHB Housing Market Index at 10:00 AM ET. The real event is earnings: 70 S&P 500 companies report this week, headlined by Netflix and GM on Tuesday and the main event — Meta and Tesla, plus IBM, Lam Research and Texas Instruments — Wednesday after the close. That’s when the AI trade gets graded. Mark SPX 7,700 as the first reclaim level above Friday’s close, 7,660 as the pivot the bounce has to defend, and 7,590 as the deeper floor that decides whether the selloff is over or just paused. A bounce isn’t a trend until the level holds. No alignment, no trade.
What is the biggest catalyst for the market today?
The tape is bouncing back from its worst week since June, and the leadership flip is the whole read. Last week value held while AI and chip names got dumped on capex and return-on-investment doubts; this morning Nasdaq futures lead up about 1.1% while Dow futures sit flat. Chips are driving it — Intel up about 4% on a JPMorgan upgrade to neutral, Micron up about 3% on a memory rebound, Datadog up about 3% on a Bernstein upgrade. The group that led the decline is leading the repair. The question is whether that’s real demand returning or oversold dip-buyers front-running Wednesday’s earnings. Futures don’t answer it; the numbers do.
What key levels should traders watch today?
SPX 7,700 — the first reclaim. This is the level just above Friday’s 7,659.44 close that the bounce has to take and hold to say buyers are genuinely back in control, not just covering shorts. Futures point to an open testing this zone, so don’t chase the gap into 7,700 on an oversold open — make the market prove it can hold above it on real volume before you trust the long. A rebound that stalls right at 7,700 and rolls over is exactly where relief-rally chasers get trapped ahead of earnings week. Let the index earn the reclaim; don’t predict it. SPX 7,660 — the pivot the bounce must defend. This is Friday’s closing area and the bull/bear line for the day: hold above it and the rebound stays intact and can work toward 7,700; lose it and fail to reclaim and this morning’s green is a relief pop fading, not a turn. On a bounce tape the index can gap up and then drift, so trust strength only if 7,660 holds as support on the first pullback. The real signal is which side of this pivot SPX settles on once the opening surge cools — a hold builds the case for the rebound, a loss warns the selloff isn’t finished. SPX 7,590 — the deeper floor. The must-hold support below the pivot, and the level that decides whether a failed bounce is a quick shakeout or the resumption of last week’s selloff. If the chip bid fades and yields reverse back toward 5.3%, 7,590 is where dip-buyers have to step up to keep the larger structure intact. Lose 7,590 and the tape is no longer ‘rebound in progress’ — it’s ‘the worst week since June has a sequel,’ and that’s a heavier game into Wednesday’s earnings. Mark it, respect it, and let price confirm. Don’t guess the bottom; let the level tell you whether the weakness is a dip or a trend.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – October 19, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.