Wednesday, September 16, 2026 · 8:45 AM ET · MTC Market Intelligence
The stock market today is holding its breath. This is Fed decision day — the FOMC lands at 2 PM ET, and for the first time in this whole cycle the market is bracing for a HIKE, not a cut. CME FedWatch has it around 92–93% for a 25bp move to 3.75%–4.00%, which would be the first rate increase since 2023. Futures are barely moving into it: S&P 500 futures +0.07%, Nasdaq-100 +0.08%, Dow roughly flat. That’s not calm — that’s paralysis. Underneath the flat tape, the pressure is real: the 10-year Treasury yield touched 5.04% overnight, its highest since 2007, and WTI crude is back above $103, up 2.2%, keeping the inflation-and-yield loop alive. That’s exactly the combination — yields at a 19-year high, oil over $100 — that is forcing the Fed’s hand. Stocks fell into the decision: Tuesday the Dow lost 328 points (-0.63%) to 52,093, the S&P slipped 0.45% to 7,585.73, and the Nasdaq dropped 0.78%. The one thing holding the tape up is AI and semis — AMD, Qualcomm, and the optical names kept the downside contained Tuesday, and that narrow leadership is the only real bid. Here’s the frame most traders will get wrong today: the hike is already priced. The trade isn’t the 2 PM headline — it’s the 2:30 PM Powell press conference and the dot plot. That’s where the surprise lives, and that’s where the range breaks. So the job this morning is simple: don’t predict the decision. Mark your levels, sit on your hands into 2 PM, and trade the reaction. No alignment, no trade.
Market Snapshot
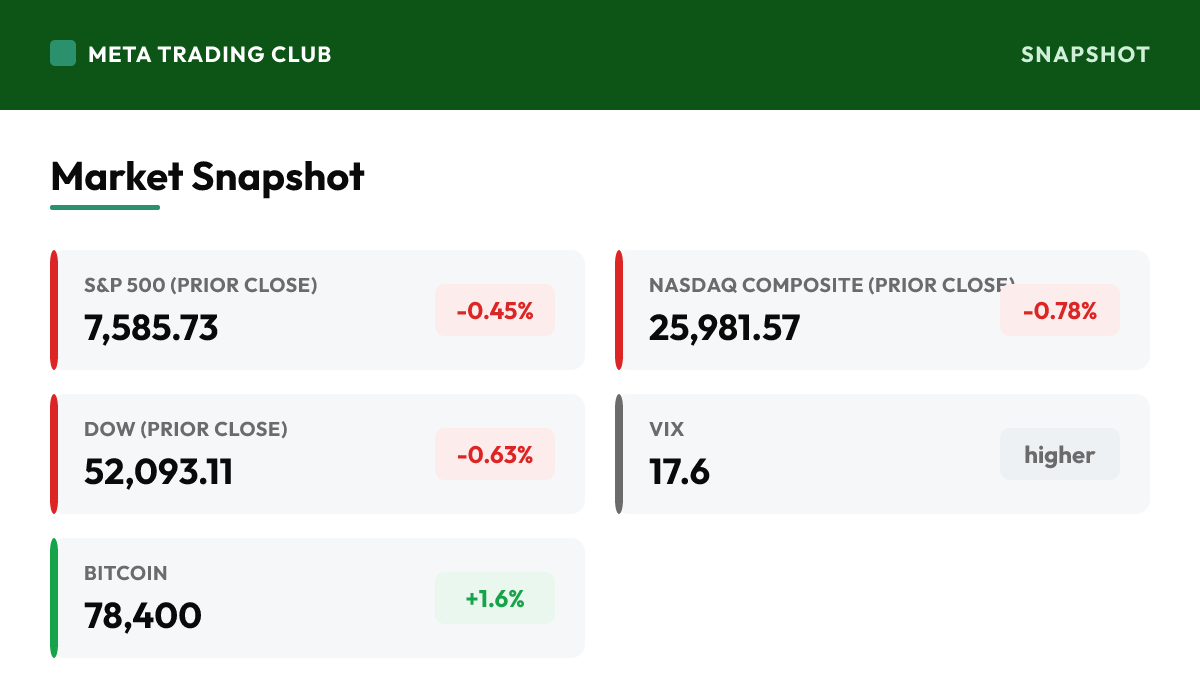
| Instrument | Level | Change | Note |
|---|---|---|---|
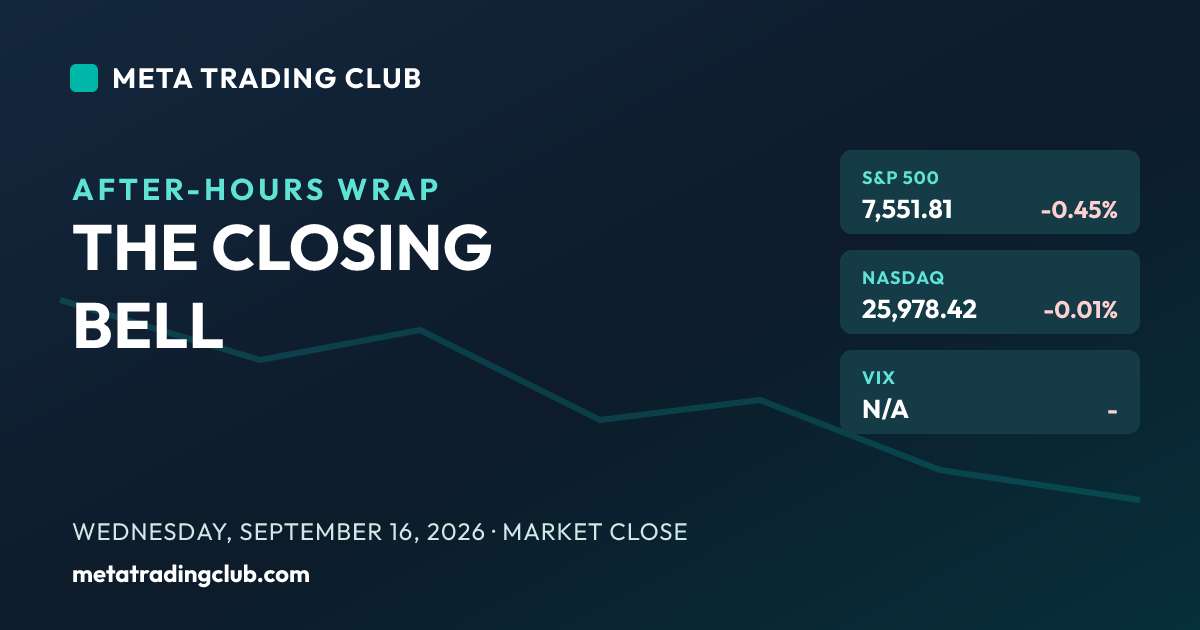
| S&P 500 (prior close) | 7,585.73 | -0.45% | Fell 0.45% Tuesday to 7,585.73, a third straight drift lower into the Fed. The tape isn’t breaking down, it’s coiling — buyers won’t commit and sellers won’t press until 2 PM tells them what the Fed actually did. That close is the pivot every reaction today swings around. |
| Nasdaq Composite (prior close) | 25,981.57 | -0.78% | Eased 0.78% Tuesday to 25,981.57, the softest of the majors as a 5% 10-year keeps pressure on long-duration growth. Semis are the only thing keeping the growth tape from cracking outright — if AI leadership wobbles after the Fed, the Nasdaq has the most to give back. |
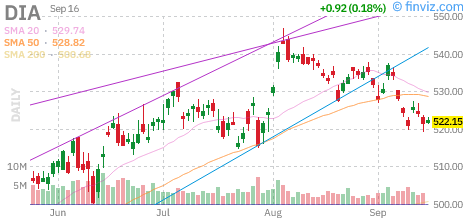
| Dow (prior close) | 52,093.11 | -0.63% | Dropped 328.09 points, or 0.63%, Tuesday to 52,093.11 as high yields and $100 oil wore on the cyclical names. The rate-sensitive corner of the Dow — homebuilders, industrials, anything that borrows — is the most exposed to a hawkish dot plot this afternoon. |
| S&P 500 Futures | — | +0.07% | Barely green, up 0.07% — a flat tape is exactly what you’d expect when a hike is 92% priced and everyone is waiting on the same 2 PM print. Don’t read direction into the premarket drift. The real move is the reaction to the decision and the presser, not the open. |
| Dow Futures | — | flat | Little changed into the decision. The cyclical, rate-sensitive index has the most to lose if the dot plot signals more hikes to come — and the most to gain if Powell frames this as the last one. Flat now, two-way risk at 2 PM. |
| Nasdaq-100 Futures | — | +0.08% | Up 0.08%, nominally leading on the back of resilient semis. But with the 10-year at a 19-year high, treat any tech bid as fragile until yields actually roll over. Growth is the most rate-sensitive corner into a hawkish Fed — the highest beta to the reaction, up or down. |
| VIX | 17.6 | higher | Up roughly 11% near 17.6 as the tape prices in the binary at 2 PM. That’s nervous, not panicked — no capitulation, just a market bracing for a known catalyst. Expect the fear gauge to snap in one direction fast once the decision and dot plot hit. |
| WTI Crude | 103.57 | +2.2% | Up 2.2% above $103.50, with Brent back over $107. Crude climbing right into the Fed is the whole problem in one line — energy is keeping inflation hot, and hot inflation is what forced the hike. Until oil cools, the rate ceiling over stocks stays firmly in place. |
| 10-Yr Yield | 5.04% | higher | Touched 5.04% overnight, its highest since 2007. This is the single most important number on the screen today. A 5% 10-year is the ceiling on every rally — and if the dot plot signals still more hikes, this yield goes higher and the pressure on stocks intensifies. |
| Bitcoin | 78,400 | +1.6% | Up about 1.6% near $78,400, catching a modest risk bid overnight. Crypto firming while equities sit flat is a small tell that not all risk appetite is dead — but with yields at cycle highs, treat it as a bounce, not a trend, until after the Fed. |
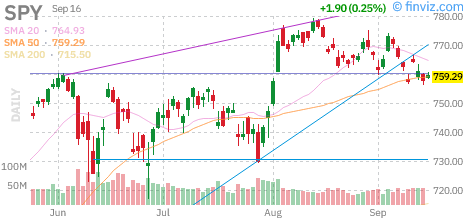
Charts to Watch
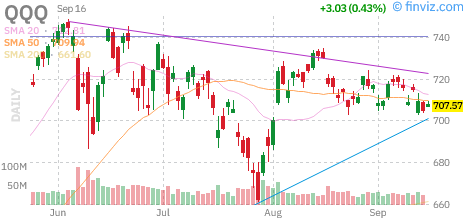
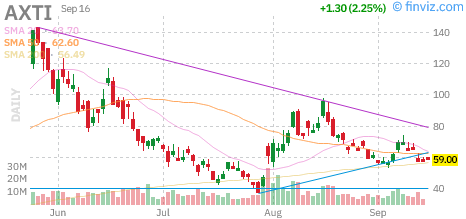
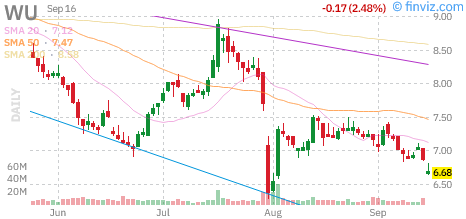
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
Overnight & Global Markets
Tuesday extended the grind lower into the decision: the Dow fell 328.09 points, or 0.63%, to 52,093.11, the S&P 500 slipped 0.45% to 7,585.73, and the Nasdaq Composite eased 0.78% to 25,981.57, all pressured by the 10-year touching a 19-year high near 5.04% and WTI crude pushing back over $103.50. This morning the tape is dead flat — S&P futures +0.07%, Nasdaq-100 +0.08%, Dow roughly unchanged — because the FOMC decision at 2 PM ET is 92% priced for a 25bp hike to 3.75%–4.00%, the first increase since 2023. The only thing containing the downside is AI and semiconductor leadership; AMD, Qualcomm, and the optical names held up Tuesday and are the one clean bid under a nervous market. The setup is a coiled spring: yields and oil are forcing a hawkish Fed, the decision is already in the price, and the actual volatility waits for the 2:30 PM press conference and the dot plot. This morning is about preparation, not prediction.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The Fed is the entire day. The FOMC decision lands at 2 PM ET, and markets price roughly a 92–93% chance of a 25bp hike to a 3.75%–4.00% target range — the first rate increase since 2023. This isn’t a close call in the market’s mind; the decision itself is close to fully priced. What is not priced is the path: the meeting comes with the updated Summary of Economic Projections and the dot plot, and Powell’s press conference at 2:30. Whether the Fed frames this as one-and-done or the start of a series is the real market-moving variable, not the hike itself.
- The reason the Fed is hiking is sitting right on the screen: the 10-year Treasury yield touched 5.04% overnight, its highest since 2007, and WTI crude is back above $103.50 with Brent over $107. Elevated energy is keeping inflation sticky, and the bond market is pricing tighter policy — the 10-year at a 19-year high is the bond market leaning into a hawkish Fed, not fading it. When the long end is at cycle highs and oil is climbing into a rate decision, equity upside is capped no matter what the 2 PM headline says.
- Stocks came into the decision on the back foot, drifting lower for three sessions as yields climbed. That matters for how to read today: a market that’s already leaned defensive into a known catalyst has less to unwind on a hawkish surprise and more room to relieve on a dovish one. The setup is coiled both ways. The mistake would be to guess the direction ahead of 2 PM — the tape is telling you it doesn’t know either, which is exactly why futures are flat.
Stock-Specific
- AI and semis remain the tape’s only clean leadership. Advanced Micro Devices (AMD) rose about 2% and Qualcomm (QCOM) advanced more than 4% Tuesday, with optical/AI-infrastructure names firm, and that strength is the single reason the S&P and Nasdaq didn’t fall further. In the premarket, the AI-infrastructure theme is still drawing a bid — names tied to AI compute and memory are among the movers as the capex story holds. But lean on this carefully: narrow leadership is a bid, not a foundation.
- Premarket movers are mostly single-name catalysts, not market tells. AXT Inc. (AXTI) is higher on the broader AI-semiconductor recovery bid, and Western Union (WU) is up ahead of its ex-dividend date as buyers reach for the quarterly payout. Rogers Corporation (ROG) is firmer after flagging an investor day and a solid Q3 outlook. These are idiosyncratic — treat them as stock stories, not signals about where the index goes after 2 PM.
- On the downside, Sea Limited (SE) is under pressure premarket on a stack of its own issues: insider share sales by executives, rising Treasury yields weighing on high-multiple growth, competitive pressure from Grab, and a soft recent quarter, all into its annual meeting today. It’s a clean example of what a 5% 10-year does to expensive growth names — the exact vulnerability the whole growth complex carries into a hawkish Fed.
Global and Macro
- The rates and energy markets are driving the regime, not the equity tape. The 10-year at a 19-year high and WTI over $100 are a self-reinforcing loop: higher oil lifts inflation expectations, which lifts yields, which pressures stocks and forces the Fed tighter. Today’s hike is the policy response to that loop. Until either oil cools or yields roll over, that backdrop stays hostile to risk regardless of any single day’s bounce.
- The one number that outranks the hike itself this afternoon is the dot plot. Markets already expect the 25bp move; what they don’t know is how many more the committee is signaling and where it sees the terminal rate. A dot plot that points to additional hikes sends the 10-year higher and pressures stocks; one that frames today as near the end of the road is where the relief comes from. Watch the projections and Powell’s tone at 2:30 — that’s the real catalyst, not the 2 PM line.
TECHNICAL ANALYSIS
S&P 500 Key Levels
- The S&P closed Tuesday at 7,585.73, and that level is the pivot the whole session swings around. Into 2 PM, expect a tight, low-conviction range — the real range break comes on the reaction to the decision and the presser. On the upside, 7,620 is the first hurdle and 7,660 the next; reclaim and hold 7,620 after the Fed and the tape is telling you it can shrug off the hike, with 7,700 back in the conversation. Don’t anticipate that move — let price take the level after 2 PM before you trust it.
- First support is 7,560, then the line that matters: 7,520. Lose 7,520 on a hawkish reaction and the door opens to 7,500 and a deeper risk-off leg as the 10-year presses higher. Above 7,560 the tape stays balanced and the coil resolves higher; below 7,520 the Fed reaction has turned into a trend. Mark 7,620 above and 7,520 below — those two lines frame the entire afternoon. Between them is noise; outside them is the trade.
Sector and Sentiment
- The sentiment tell is the narrow leadership. Semis and a handful of AI names are carrying the tape while everything rate-sensitive lags. That’s a market leaning on its strongest horse into an uncertain event — fine while it works, dangerous if that leadership cracks after 2 PM. Watch whether AMD, Qualcomm, and the optical names hold their bid through the reaction; if they do, dips get bought, and if they don’t, there’s little underneath to catch the index.
- The VIX up ~11% near 17.6 says the market is bracing, not capitulating. There’s a known binary at 2 PM and a presser at 2:30, and the fear gauge is pricing the two-way risk. Practically, that means expect a fast move in one direction once the decision and dot plot hit — and don’t confuse the flat premarket for a quiet day. The quiet is the setup; the volatility is scheduled for the afternoon.
TODAY’S ECONOMIC CALENDAR
Key Releases (ET)
- The FOMC rate decision at 2:00 PM ET is the whole calendar. Markets price ~92% odds of a 25bp hike to 3.75%–4.00%, the first increase since 2023, and the decision comes with the updated Summary of Economic Projections and the dot plot. The Fed chair’s press conference follows at 2:30 PM. Everything else on the tape today is a placeholder until 2 PM — position and risk should be built around that one event, not around the morning drift.
- The variable that actually moves markets this afternoon is the path, not the hike. Watch the dot plot for how many more increases the committee signals and where it pegs the terminal rate, and watch Powell’s tone for whether he leaves the door open or frames today as near the end. The 2-year and 10-year yields will tell you how the bond market reads it in real time — let the rates reaction, not the first headline, guide your read of the equity move.
Earnings Today
- The earnings slate is light and sits in the Fed’s shadow. There are no marquee premarket reports; the notable name is Lennar (LEN), the homebuilder, reporting after today’s close. On a day the Fed is hiking with the 10-year at 5%, a homebuilder print is a timely read on how higher-for-longer rates are hitting housing demand and margins — worth a look after the bell, but not a market driver against the FOMC.
- With the calendar quiet, there’s no earnings catalyst to distract from the main event, which is exactly how the tape wants it. The single-name action this morning is deal-and-dividend noise, not a theme. Keep the focus on rates, oil, and the 2 PM decision — that’s where the day is decided.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,620 — the upside proof after the Fed. This is the first hurdle above Tuesday’s 7,585.73 close. Reclaim it AND hold it on the reaction to the decision and the presser, and the tape is telling you it can absorb the hike — buyers stepping in with the rate move behind them, 7,660 and then 7,700 back in play. But this only counts after 2 PM. Don’t buy the premarket drift toward it; make price take the level once the Fed is out.
- SPX 7,585 / 7,560 — the pivot and the balance line. 7,585.73 is Tuesday’s close and the axis the whole session rotates around; 7,560 is the first support under it. Hold this zone through the reaction and the coil stays balanced, ready to resolve higher. This is the ‘wait and see’ band — into 2 PM the tape lives here, and the real signal is which side it leaves on. Sit on your hands until it picks a direction.
- SPX 7,520 — the invalidation line. Lose it on a hawkish dot plot and the door opens to 7,500 and a deeper risk-off leg as the 10-year presses past 5%. Below 7,520 the Fed reaction has turned into a trend, not a wobble, and the job flips to capital preservation. This is the number that separates a nervous hold from a genuine breakdown — mark it, and respect it if it goes.
Bull case: The 25bp hike lands as expected and Powell frames it as near the end of the road — a dot plot that signals few or no further increases. Yields roll off the 5% highs, the pressure valve opens, and SPX reclaims 7,620 and pushes toward 7,660–7,700 as the rate-sensitive names that got hit hardest lead the relief. Semis hold their bid and leadership broadens. In this scenario, the whole three-day drift into the Fed was positioning for an unknown that turned out to be manageable, and the coil resolves higher once the uncertainty clears.
Bear case: The hike comes with a hawkish dot plot pointing to more increases, the 10-year presses past 5%, and Powell refuses to signal a pause. Growth and rate-sensitive names sell off, semis lose their bid with nothing underneath to catch the tape, and SPX loses 7,560 and then 7,520 into a deeper risk-off leg toward 7,500. In this scenario the market realizes the tightening isn’t over, the inflation-and-yield loop stays intact with oil over $100, and today’s flat open was the calm before a hawkish repricing.
Premarket Movers
Gainers
| AXTI | AXT Inc. | higher on the AI-semiconductor recovery bid | Firmer premarket as the AI-semiconductor complex catches a recovery bid ahead of the Fed. It’s a beta play on the one theme with real leadership right now — AI compute and memory demand — rather than a company-specific catalyst. Treat it as a read on risk appetite inside the semis trade, not a market-wide signal; if the AI bid holds through 2 PM, names like this hold with it. |
| WU | Western Union | up ahead of its ex-dividend date | Rising premarket as buyers reach for the quarterly dividend ahead of the ex-date, with the payout representing a high annualized yield. This is a mechanical, income-driven move, not a statement about the tape — the kind of dividend-capture flow that shows up regardless of what the Fed does. A clean single-name story; don’t read anything macro into it. |
Laggards
| SE | Sea Limited | lower on insider sales, yields, and competition | Under pressure premarket on a stack of its own issues — executive insider share sales, rising Treasury yields weighing on high-multiple growth, competitive pressure from Grab, and a soft recent quarter, all into its annual meeting today. It’s a textbook example of what a 5% 10-year does to expensive growth: the exact vulnerability the whole high-multiple complex carries into a hawkish Fed. |
Risks Into the Open
- Primary risk: the hike is priced, but the path is not. Markets are ~92% positioned for the 25bp move, so the 2 PM headline itself is unlikely to be the shock — the dot plot and Powell’s tone at 2:30 are. A projection that signals more hikes to come sends the 10-year past 5% and pressures stocks; a ‘near the end’ framing is where the relief lives. The mistake today is trading the decision instead of the reaction to it. Wait for the level to confirm.
- The tape is being carried by narrow leadership. Semis and a handful of AI names are the only real bid, doing the work while everything rate-sensitive lags. That’s fine while it holds, but a market leaning on a few horses into a binary event is fragile — if AMD, Qualcomm, and the optical names lose their bid after the Fed, there’s little underneath to catch the index. Watch that leadership through the reaction; it’s the quality check on any bounce.
- The macro backdrop stays hostile until oil cools or yields roll over. WTI over $100 and the 10-year at a 19-year high are a self-reinforcing loop that forced today’s hike and caps every rally. Even a dovish-sounding Powell can’t undo a 5% 10-year and $100 oil in one afternoon. Treat any post-Fed pop that isn’t confirmed by yields actually coming in as a relief move inside a hostile regime, not an all-clear.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Wednesday, September 16, 2026, S&P 500 futures are at 7,585.73 (-0.45%), with the VIX near 17.6. The stock market today is holding its breath. This is Fed decision day — the FOMC lands at 2 PM ET, and for the first time in this whole cycle the market is bracing for a HIKE, not a cut. CME FedWatch has it around 92–93% for a 25bp move to 3.75%–4.00%, which would be the first rate increase since 2023. Futures are barely moving into it: S&P 500 futures +0.07%, Nasdaq-100 +0.08%, Dow roughly flat. That’s not calm — that’s paralysis. Underneath the flat tape, the pressure is real: the 10-year Treasury yield touched 5.04% overnight, its highest since 2007, and WTI crude is back above $103, up 2.2%, keeping the inflation-and-yield loop alive. That’s exactly the combination — yields at a 19-year high, oil over $100 — that is forcing the Fed’s hand. Stocks fell into the decision: Tuesday the Dow lost 328 points (-0.63%) to 52,093, the S&P slipped 0.45% to 7,585.73, and the Nasdaq dropped 0.78%. The one thing holding the tape up is AI and semis — AMD, Qualcomm, and the optical names kept the downside contained Tuesday, and that narrow leadership is the only real bid. Here’s the frame most traders will get wrong today: the hike is already priced. The trade isn’t the 2 PM headline — it’s the 2:30 PM Powell press conference and the dot plot. That’s where the surprise lives, and that’s where the range breaks. So the job this morning is simple: don’t predict the decision. Mark your levels, sit on your hands into 2 PM, and trade the reaction. No alignment, no trade.
What is the biggest catalyst for the market today?
The Fed is the entire day. The FOMC decision lands at 2 PM ET, and markets price roughly a 92–93% chance of a 25bp hike to a 3.75%–4.00% target range — the first rate increase since 2023. This isn’t a close call in the market’s mind; the decision itself is close to fully priced. What is not priced is the path: the meeting comes with the updated Summary of Economic Projections and the dot plot, and Powell’s press conference at 2:30. Whether the Fed frames this as one-and-done or the start of a series is the real market-moving variable, not the hike itself.
What key levels should traders watch today?
SPX 7,620 — the upside proof after the Fed. This is the first hurdle above Tuesday’s 7,585.73 close. Reclaim it AND hold it on the reaction to the decision and the presser, and the tape is telling you it can absorb the hike — buyers stepping in with the rate move behind them, 7,660 and then 7,700 back in play. But this only counts after 2 PM. Don’t buy the premarket drift toward it; make price take the level once the Fed is out. SPX 7,585 / 7,560 — the pivot and the balance line. 7,585.73 is Tuesday’s close and the axis the whole session rotates around; 7,560 is the first support under it. Hold this zone through the reaction and the coil stays balanced, ready to resolve higher. This is the ‘wait and see’ band — into 2 PM the tape lives here, and the real signal is which side it leaves on. Sit on your hands until it picks a direction. SPX 7,520 — the invalidation line. Lose it on a hawkish dot plot and the door opens to 7,500 and a deeper risk-off leg as the 10-year presses past 5%. Below 7,520 the Fed reaction has turned into a trend, not a wobble, and the job flips to capital preservation. This is the number that separates a nervous hold from a genuine breakdown — mark it, and respect it if it goes.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – September 16, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.