Thursday, October 1, 2026 · 8:45 AM ET · MTC Market Intelligence
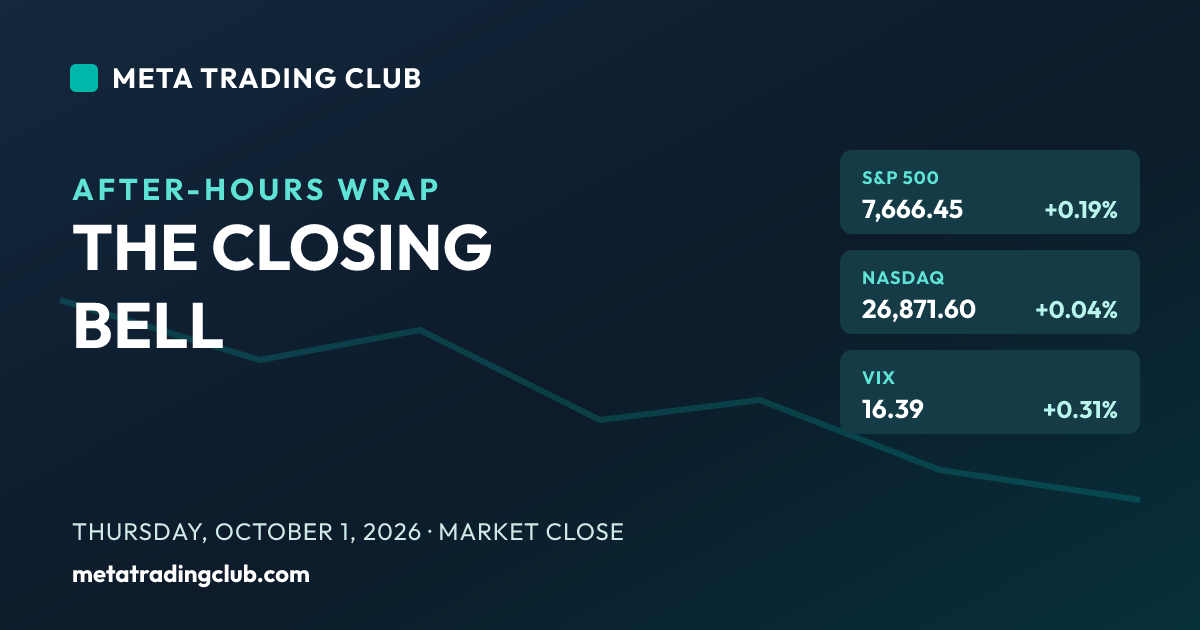
The stock market today is opening the fourth quarter with a split personality — the chips want to run while the bond market is screaming. Wednesday closed September on a soft, two-sided note: the Dow dropped 443.87 points, or 0.86%, to 50,906.05, the S&P 500 eased 0.25% to 7,651.54, and the Nasdaq Composite actually held green, up 0.24% to 26,861.06, as tech and semis absorbed the pressure the broad tape could not. This morning futures are firmly higher and led by the chips — Nasdaq-100 futures up about 0.86%, S&P 500 futures up roughly 0.48%, Dow futures up about 0.26% — on a wave of AI-driven earnings: Micron’s blowout read on memory demand, Accenture up around 17% on a revenue beat, and Alphabet up about 2% after unveiling its most advanced AI model yet. That’s the loud half of the story. The quiet half is louder: the 10-year Treasury yield just pushed to roughly 5.30%, its highest level since 2002, as a global bond rout deepens on sticky inflation and heavy government borrowing. So the setup today is a direct collision — AI euphoria lifting the Nasdaq into a generational-high yield that has been the ceiling over everything rate-sensitive. The data that decides it comes at 10:00 AM ET with ISM Manufacturing, after jobless claims at 8:30. This is a day that rewards patience over reaction: a green gap on AI headlines does not cancel a bond market at 24-year highs. Don’t chase the first candle. SPX 7,700 is the round level the gap has to reclaim and hold, 7,650 is Wednesday’s close and the axis, and 7,600 is the shelf that keeps any fade contained. Nike reports after the close. No alignment, no trade.
Market Snapshot
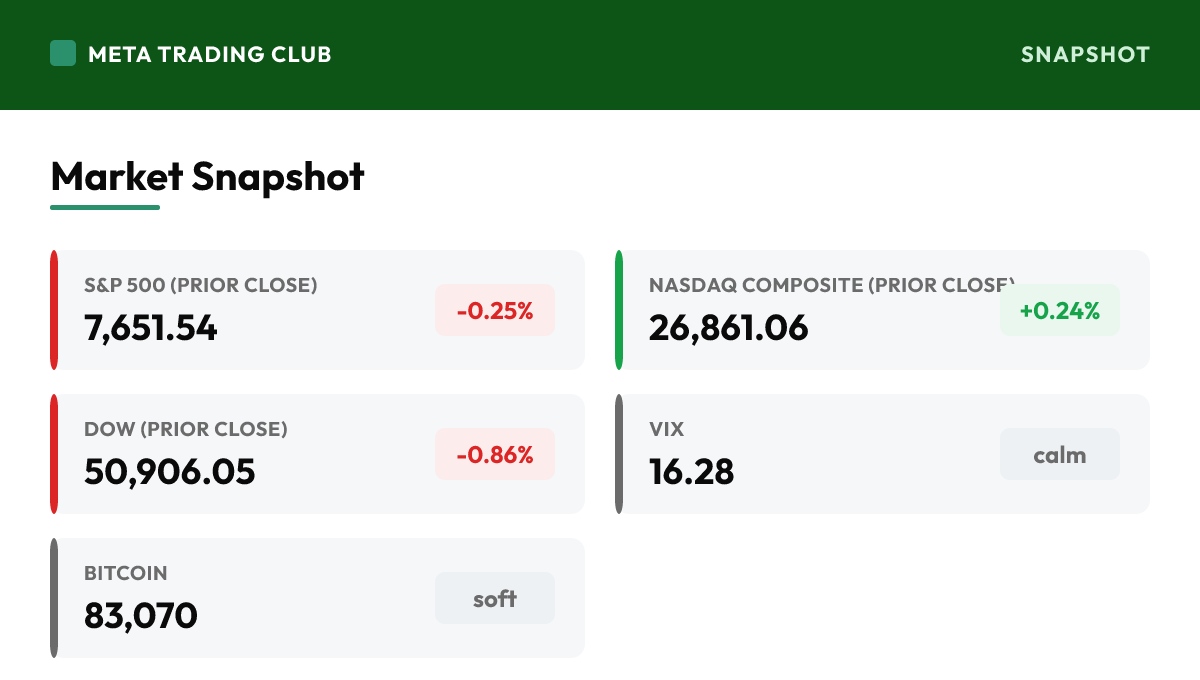
| Instrument | Level | Change | Note |
|---|---|---|---|
| S&P 500 (prior close) | 7,651.54 | -0.25% | Closed Wednesday at 7,651.54, down 0.25%, finishing September soft as the broad tape leaked even with tech holding up. That close is the axis this morning: futures point to a firmer open on AI earnings, so the first job is whether cash can push through and hold 7,700 once the gap settles. Don’t read a green premarket as an all-clear — the 10-year at a 24-year high is still the ceiling. The reaction at the level after the open, not the futures print, tells you whether this gap has legs. |
| Nasdaq Composite (prior close) | 26,861.06 | +0.24% | The relative winner Wednesday, up 0.24% to 26,861.06, as semis and megacap tech absorbed the yield pressure the Dow could not. This morning Nasdaq-100 futures lead the majors at about +0.86% on Micron’s blowout memory read and Alphabet’s new AI model. When high-multiple growth is the clear leader into a generational-high yield backdrop, respect it as real strength but watch the follow-through — the chips are the highest-beta read on whether the AI bid can override the bond rout today. |
| Dow (prior close) | 50,906.05 | -0.86% | The weakest major Wednesday, dropping 443.87 points, or 0.86%, to 50,906.05, as the blue chips leaked hardest with the 10-year climbing. This morning Dow futures are up about 0.26%, a modest steadying, but the value-heavy, rate-sensitive index is exactly where a 5.30% 10-year bites first. A small green print is positioning into the AI tailwind, not broad participation. Watch whether the Dow can widen a bounce after the open or keeps lagging the chips — that gap is the tell on how narrow this move really is. |
| S&P 500 Futures | — | +0.48% | Up about 0.48% this morning, pointing to a firmer open above Wednesday’s 7,651 close on the back of the AI earnings wave. That’s a real gap, but don’t chase it blind: futures lead with the chips while the 10-year sits at a 24-year high, so the open has to prove it can reclaim and hold 7,700 on real trade. The signal isn’t the premarket direction — it’s whether cash defends the level after the gap and through the 10:00 ISM print. |
| Nasdaq-100 Futures | — | +0.86% | Up about 0.86%, the strongest major as the chips carry the tape into the open. Micron’s blowout read on AI memory demand, Accenture’s beat and Alphabet’s new AI model are the fuel. High-multiple growth leads first when the AI story is hot, but it’s also the most exposed if yields press higher and the bond rout deepens. The Nasdaq is the leader to watch: hold the gap and the tape has a foundation; fade it and there’s no one else carrying the load. |
| Dow Futures | — | +0.26% | Up about 0.26%, a modest steadying after the blue chips dropped 0.86% Wednesday. The Dow has been the weakest major as yields climbed — value and rate-sensitive names feel a 5.30% 10-year first. A small green print into the AI tailwind is positioning, not a broad bid. Watch whether participation widens after the open: if the Dow joins the chip-led bounce, the move is healthier; if it keeps lagging, the rally stays narrow and leans entirely on tech. |
| VIX | 16.28 | calm | Holding near 16, down about 0.4%, as the options market stays calm into the open despite the bond rout underneath. It’s a low absolute reading, but a quiet VIX sitting over a 10-year at a 24-year high is the kind of complacency that can reprice fast — the equity tape is leaning on the AI story while the bond market tells a different one. Treat the calm as conditional: a hot ISM print or another leg higher in yields can wake volatility quickly. |
| WTI Crude | 90.06 | easing | Near $90, down about 0.4% this morning, hovering at a level that still feeds the inflation story the bond market is trading. Crude holding near $90 keeps a floor under the inflation-and-yield loop even as it eases at the margin — it’s not the relief valve the rate-sensitive tape needs. Track oil as a secondary tell on the yield narrative: a sustained roll-over would help, but at $90 it’s still part of the sticky-inflation backdrop pushing the 10-year higher. |
| 10-Yr Yield | 5.30% | higher | Pushed to roughly 5.30%, its highest level since 2002, as a global bond rout deepens on sticky inflation, heavy government borrowing and resilient growth. This is the single most important number on the screen and the quiet half of today’s story that matters most. Yields at a generational high are the ceiling over every rate-sensitive corner, and they are the reason the AI rally is a collision, not a clean breakout. Watch the yield reaction to the 10:00 ISM print more closely than any single stock — it leads the whole tape. |
| Bitcoin | 83,070 | soft | Holding near $83,000, soft, as the highest-beta risk assets stay pressured with rates at a generational high. Crypto leaking while equity futures gap up on AI earnings is a split-tape signal: risk appetite is selective, concentrated in the AI winners, not broad. Treat Bitcoin’s softness as a caution flag on how much risk the market is really carrying under the green open — when the 10-year is at 24-year highs, the speculative end of the curve feels it first. |
Charts to Watch
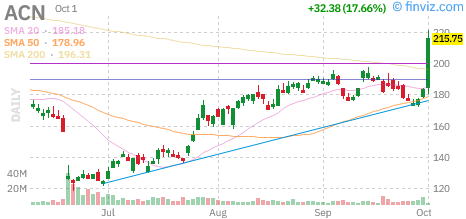
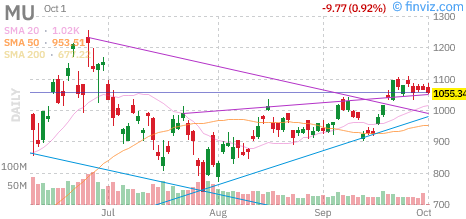
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
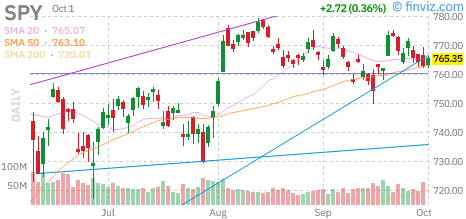
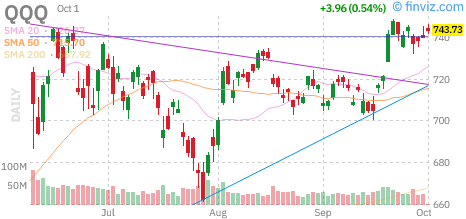
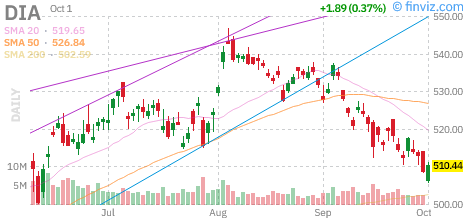
Performance at a Glance
Overnight & Global Markets
Wednesday closed September with a split tape — the Dow dropped 443.87 points, or 0.86%, to 50,906.05, the S&P 500 eased 0.25% to 7,651.54, and the Nasdaq Composite held green, up 0.24% to 26,861.06, as semis and megacap tech absorbed the yield pressure the broad market could not. This morning the chips want to run: Nasdaq-100 futures lead at about +0.86%, S&P 500 futures are up roughly 0.48%, and Dow futures are up about 0.26%, all powered by an AI-driven earnings wave — Micron’s blowout read on memory demand, Accenture up around 17% on a revenue beat, and Alphabet up about 2% on its most advanced AI model yet. That’s the loud half of the story. The quiet half is louder: the 10-year Treasury yield pushed to roughly 5.30%, its highest since 2002, as a global bond rout deepens on sticky inflation and heavy government borrowing. So today is a collision — AI euphoria lifting the Nasdaq straight into a generational-high yield that has been the ceiling over everything rate-sensitive. The data that decides direction comes at 10:00 AM ET with ISM Manufacturing, after jobless claims at 8:30, and a marathon of Fed speakers runs through the session. This is a patience day, not a chase day: a green gap on AI headlines does not cancel a bond market at 24-year highs. Mark 7,700 as the reclaim the gap has to earn and hold, 7,651 as the axis, 7,600 as the shelf, and let price prove which force wins before you act.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The AI earnings wave is the loud half of today’s tape. Micron delivered a blowout read on memory demand, Accenture is up around 17% on a revenue beat that topped its own guidance, and Alphabet is up about 2% after unveiling its most advanced AI model yet. Together they are lifting Nasdaq-100 futures to a near +0.9% lead and dragging the broad tape green. This is real strength in the AI names — but it’s concentrated leadership, not broad participation. Treat the AI bid as genuine while it holds, and watch whether it can carry the whole tape or just the chips.
- The 10-year at roughly 5.30% is the quiet half — and it matters more. Yields pushed to their highest level since 2002 as a global bond rout deepens on sticky inflation, heavy government borrowing and resilient growth. This is the ceiling under everything rate-sensitive, and it’s the reason today’s AI rally is a collision rather than a clean breakout. Watch the yield reaction to the 10:00 ISM print more closely than any single stock: if the 10-year presses higher, even the AI leaders feel it; if it eases, that’s the release valve that lets the gap extend.
- The data and Fed calendar stack up through the session. Jobless claims land at 8:30 AM ET, and the main event is ISM Manufacturing at 10:00 — the first real look at how factories did in September and a market-mover for the yield story. On top of that, a marathon of Fed speakers runs all day: Barkin, Collins, Schmid, Waller, Jefferson and Bowman. With the bond market this tense, any hawkish line can move the 10-year and the tape. Let the data and the yield reaction guide the trade, not the green premarket print.
Stock-Specific
- Micron (MU) is the marquee AI read of the morning, gapping higher on a blowout quarter and a fully-booked outlook for high-bandwidth memory tied to the AI buildout. It’s the fuel under the chip complex and the single best gauge of whether the AI demand story is still accelerating. Treat its strength as a real read on the AI leaders while it holds — but remember the move is already a large gap, and the cleanest trades come from how it reacts at its levels after the open, not from chasing the premarket pop.
- Accenture (ACN) is the standout premarket gainer, up around 17% after fiscal Q4 revenue of about $18.68 billion topped both its own guidance and Street estimates, with EPS of $3.29 also beating. It’s a clean, catalyst-driven move on a genuine beat — a read that enterprise AI and consulting demand is holding up. Trade it on its own levels: a 17% gap is a large move that can give back fast once the number is fully priced, so let it prove it can hold the gap rather than chasing the open.
- Alphabet (GOOGL) is up about 2% after unveiling its most advanced AI model yet, and Rocket Lab (RKLB) is up roughly 4.5% on a 20-mission launch agreement — its largest commercial Electron contract to date. United Therapeutics (UTHR) jumped about 12.5% on a favorable patent ruling, and McCormick (MKC) is up near 5% on a Q3 beat. These are clean single-name catalysts cutting through the macro backdrop. On a day defined by the AI-vs-yields collision, the self-contained setups are the ones with their own story — trade them on their own levels.
Global and Macro
- The bond rout is global, not just a U.S. story. The 10-year at a 24-year high is part of a worldwide move higher in yields driven by sticky inflation, heavy government borrowing and resilient growth — the 30-year has pushed toward 5.64%. That’s the macro backdrop the whole tape runs through: when the risk-free rate is at generational highs, it’s the ceiling over every risk asset, and it’s why crypto is soft and small caps are pressured even as the AI names run. The yield is the driver; everything else is a reaction to it.
- No shutdown, and the growth data is firm. The federal fiscal year turned over today without a government shutdown after a continuing resolution was signed, removing one tail risk from the tape. And the backdrop is resilient: ADP added about 90,000 private jobs against a 68,000 estimate, and GDP was revised up to 2.2%. That resilience is a double-edged sword — it’s good for earnings, but it’s exactly what keeps the Fed cautious and the 10-year elevated. Strong growth is part of why yields are at 24-year highs, not a reason to fade them.
TECHNICAL ANALYSIS
S&P 500 Key Levels
- The S&P closed Wednesday at 7,651.54 and futures point to a firmer open on the AI earnings wave, so the first battle is the 7,700 reclaim. That round level just above the close is where a gap-up open has to prove buyers want control once the dust settles — reclaim it and hold with the chips leading, and the September softness gives way to a base. Push through toward 7,720 and the AI bid is winning the collision. Don’t chase the gap into 7,700; let cash take and hold the level on real trade before you trust the long side.
- First support is 7,651 — Wednesday’s close and the axis the gap is built on. Below that, 7,600 is the shelf that keeps any fade contained. Lose 7,600 with the 10-year pressing higher and the tape opens toward the next leg lower as the yield ceiling wins. Above, 7,700 is the reclaim and 7,720 is where the AI bid takes real control. Mark 7,700 above and 7,600 below — inside is chop as the market digests the AI-vs-yields tug, outside is the real signal on which force is winning.
Sector and Sentiment
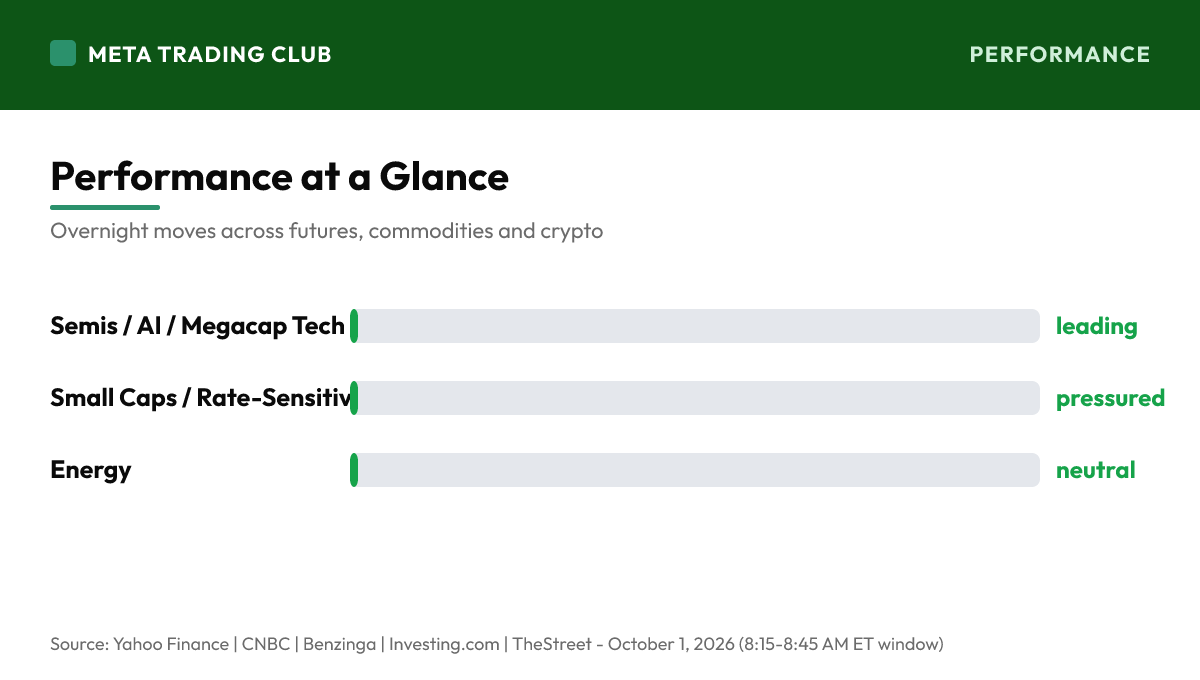
- The leadership read is narrow by design: the chips and megacap tech are carrying the tape on AI earnings while the Dow lags and small caps stay pressured by yields. That’s a concentrated, AI-led bid, not a broad risk-on move. For this gap to build into something that holds, you want participation to widen — the Dow joining rather than lagging, and the rate-sensitive corners stabilizing as the 10-year eases. Until then, trade it tactically off the levels; a narrow rally leaning entirely on the AI names is not a trend you assume will hold.
- The VIX near 16 says the options market is calm, but that calm is sitting on top of a bond market at 24-year highs — the definition of conditional complacency. Low absolute volatility over a global bond rout is the setup where a hot ISM print or another leg higher in yields can reprice risk fast. Practically: respect that the quiet can flip, keep the 10-year on your screen as the real driver, and let SPX prove its levels on the reaction to the 10:00 data before you trust either side of the collision.
TODAY’S ECONOMIC CALENDAR
Key Releases (ET)
- The morning opens with initial jobless claims at 8:30 AM ET, but the weight lands at 10:00 with ISM Manufacturing — the first big read on how factories did in September and a genuine market-mover. With the 10-year at a 24-year high, this print is a direct input to the yield story: a hot read that signals sticky inflation and resilient activity presses the bond market higher and pressures the rate-sensitive tape; a cool read eases yields and gives the AI-led gap room to extend. Watch the 10-year’s reaction to ISM as much as the headline number.
- A marathon of Fed speakers runs all session: Barkin, Collins, Schmid, Waller, Jefferson and Bowman. With the bond market this tense, any hawkish line about higher-for-longer can move the 10-year and ripple straight through the tape. Watch the chain, not just the calendar — the data and the Fed commentary move yields, and yields move everything. Let the rates reaction guide the trade: if the 10-year presses higher through the session, the rate-sensitive laggards leak; if it eases, the chips and the broad tape get room to build on the gap.
Earnings Today
- Micron (MU) is the earnings story already in motion, gapping higher on a blowout read on AI memory demand that’s fueling the chip complex this morning. Before the bell, Accenture (ACN) is up around 17% on a revenue beat, McCormick (MKC) near 5% on a Q3 beat, and Acuity (AYI) also reported. After the close, Nike (NKE) headlines — a key read on the consumer and global demand — alongside Conagra (CAG), Cal-Maine (CALM), Jabil (JBL) and FactSet (FDS). The AI names are driving the tape today; Nike tonight is the read on whether the consumer is holding up with rates this high.
- Trade the macro, use earnings as texture. The moves that matter most this morning are the AI-vs-yields collision and the ISM reaction — the single-name earnings are the fuel under the gap, not the thing that decides the day. Where they add value is as a check on demand: Accenture and Micron say enterprise and AI demand are strong, while Nike tonight tells you whether the household is still spending with the 10-year at 24-year highs. That’s the tension underneath the tape — strong AI demand against a consumer and a bond market feeling the weight of rates.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,700 — the reclaim. The round level just above Wednesday’s 7,651 close, and the first thing a gap-up open has to earn back and hold once the dust settles. Reclaim it AND hold it with the chips leading and the AI bid is winning the collision, opening the door toward 7,720 and higher. But this is a gap on AI earnings into a 24-year-high yield — don’t chase it. Make price take and hold 7,700 on real trade after the open and through the 10:00 ISM print before you trust the long side.
- SPX 7,651 — the axis. Wednesday’s close and the pivot the gap is built on. This is the ‘let it prove itself’ zone where a tape caught between AI euphoria and a bond rout tends to chop as ISM gets digested and the 10-year picks a direction. The real signal is which side SPX leaves 7,651 on once cash trades and the yield reaction sets in. Inside the range is noise; the move that matters follows the data. Patience beats chasing the gap here.
- SPX 7,600 — the shelf that keeps the fade contained. It’s the level that separates a healthy gap-and-hold from a failed gap that rolls over. Lose 7,600 with the 10-year pressing higher after ISM, and the tape opens to the next leg lower as the yield ceiling wins the collision. Below 7,600 the market is rejecting the AI bid and the job flips to capital preservation. Mark it, and respect it if it goes — a failed gap into rising yields is one of the cleaner short setups.
Bull case: ISM comes in soft enough to ease the yield pressure, the 10-year backs off 5.30%, and the AI bid holds. SPX reclaims 7,700 and pushes toward 7,720, participation widens beyond the chips as the Dow joins, and the market gets its first real breathing room as the yield ceiling lifts. In this scenario the AI earnings wave — Micron, Accenture, Alphabet — is the genuine catalyst that carries the tape, the bond rout pauses, and the gap becomes a base with the chips leading into the back half of the week and Nike tonight.
Bear case: ISM runs hot, confirming sticky inflation and resilient activity, the 10-year presses higher over 5.30%, and the rate-sensitive tape leaks as the bond rout deepens. SPX fails to reclaim 7,700, fades back through 7,651, and loses 7,600 as even the AI leaders give back their gap. A hot print into a bond market already at 24-year highs is the hardest backdrop for stocks — it confirms higher-for-longer with no relief, and a failed gap-up is exactly how euphoria turns into a reversal. In this scenario the AI rally was a one-day headline bid that the yield ceiling caps hard.
Premarket Movers
Gainers
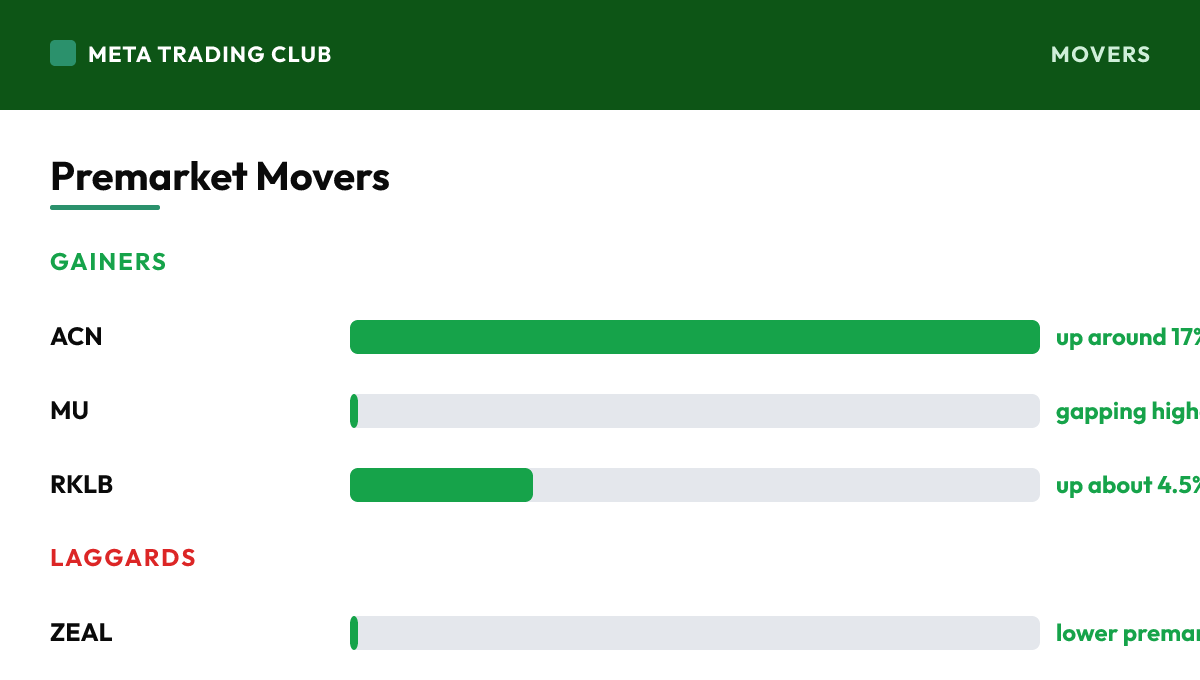
| ACN | Accenture | up around 17% on a fiscal Q4 revenue beat above its own guidance | The standout premarket gainer, up around 17% after fiscal Q4 revenue of about $18.68 billion topped both company guidance and Street estimates, with EPS of $3.29 also beating. It’s a clean, catalyst-driven move on a genuine beat and a read that enterprise AI and consulting demand is holding up. Trade it on its own levels: a 17% gap is a large move that can give back fast once the number is fully priced, so let it prove it can hold the gap on real trade rather than chasing the premarket pop. |
| MU | Micron Technology | gapping higher on a blowout read on AI memory demand | The marquee AI catalyst of the morning, gapping higher on a blowout quarter and a fully-booked outlook for high-bandwidth memory tied to the AI buildout. It’s the fuel under the chip complex and the single best gauge of whether the AI demand story is still accelerating. Watch memory pricing and AI demand commentary as the real read for the whole group. The move is already a large gap, so the cleanest trades come from how it reacts at its levels after the open, not from chasing the premarket strength. |
| RKLB | Rocket Lab | up about 4.5% on its largest commercial Electron launch contract | Up roughly 4.5% after signing a 20-mission launch agreement — its largest commercial Electron contract to date. A clean, single-name catalyst on a real business win, independent of the macro collision driving the broad tape. Trade it on its own story and its own levels: news-driven moves can extend on momentum but also give back when the catalyst is priced. On a day defined by AI-vs-yields, this is the kind of self-contained setup that trades on its own merits, not as a read on the market’s direction. |
Laggards
| ZEAL | Zealand Pharma | lower premarket on company-specific news | Among the few notable premarket decliners on an otherwise green tape, lower on company-specific news rather than any macro signal. On a morning dominated by the AI earnings wave and the bond rout, broad premarket weakness is scarce — the pressure is concentrated in the rate-sensitive corners, not the single names. Treat this as idiosyncratic risk and trade it on its own story. The lesson holds: know whether you’re trading the market’s collision or a single company’s news, because they demand different playbooks. |
Risks Into the Open
- Primary risk: chasing the gap instead of trading the reaction. A green premarket on AI earnings is a tailwind, but with the 10-year at a 24-year high it is not a green light — chasing the first candle into a gap-up is how you get caught when the AI bid collides with the yield ceiling and reverses. Let SPX react to the open and the 10:00 ISM print, watch the 10-year’s response, and require price to reclaim and hold 7,700 or lose 7,600 on real trade before you act. The reaction at the level is the signal; the gap alone is noise.
- The 10-year at 5.30% is the ceiling risk for the whole tape. Yields at their highest since 2002, in a deepening global bond rout, are the weight over every rate-sensitive corner — and the reason today’s AI rally is a collision, not a clean breakout. If ISM leans hot and the 10-year presses higher, the rate-sensitive names leak first and even the AI leaders can’t hold the gap. The regime is elevated-and-rising rates in a bond-market-led tape — respect the ceiling, and watch the yield reaction as the real driver of every other move today.
- Narrow leadership and conditional calm are the quieter risks. The gap is carried almost entirely by the AI names while the Dow lags and small caps stay pressured — a concentrated bid that’s fragile if the chips fade. And the VIX near 16 is calm sitting on top of a bond rout, the kind of complacency that reprices fast on a hot ISM print or another leg higher in yields. Don’t mistake a narrow, AI-led green open for broad strength. Trade the levels, keep the 10-year on your screen, and let participation prove itself before trusting the move.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Thursday, October 1, 2026, S&P 500 futures are at 7,651.54 (-0.25%), with the VIX near 16.28. The stock market today is opening the fourth quarter with a split personality — the chips want to run while the bond market is screaming. Wednesday closed September on a soft, two-sided note: the Dow dropped 443.87 points, or 0.86%, to 50,906.05, the S&P 500 eased 0.25% to 7,651.54, and the Nasdaq Composite actually held green, up 0.24% to 26,861.06, as tech and semis absorbed the pressure the broad tape could not. This morning futures are firmly higher and led by the chips — Nasdaq-100 futures up about 0.86%, S&P 500 futures up roughly 0.48%, Dow futures up about 0.26% — on a wave of AI-driven earnings: Micron’s blowout read on memory demand, Accenture up around 17% on a revenue beat, and Alphabet up about 2% after unveiling its most advanced AI model yet. That’s the loud half of the story. The quiet half is louder: the 10-year Treasury yield just pushed to roughly 5.30%, its highest level since 2002, as a global bond rout deepens on sticky inflation and heavy government borrowing. So the setup today is a direct collision — AI euphoria lifting the Nasdaq into a generational-high yield that has been the ceiling over everything rate-sensitive. The data that decides it comes at 10:00 AM ET with ISM Manufacturing, after jobless claims at 8:30. This is a day that rewards patience over reaction: a green gap on AI headlines does not cancel a bond market at 24-year highs. Don’t chase the first candle. SPX 7,700 is the round level the gap has to reclaim and hold, 7,650 is Wednesday’s close and the axis, and 7,600 is the shelf that keeps any fade contained. Nike reports after the close. No alignment, no trade.
What is the biggest catalyst for the market today?
The AI earnings wave is the loud half of today’s tape. Micron delivered a blowout read on memory demand, Accenture is up around 17% on a revenue beat that topped its own guidance, and Alphabet is up about 2% after unveiling its most advanced AI model yet. Together they are lifting Nasdaq-100 futures to a near +0.9% lead and dragging the broad tape green. This is real strength in the AI names — but it’s concentrated leadership, not broad participation. Treat the AI bid as genuine while it holds, and watch whether it can carry the whole tape or just the chips.
What key levels should traders watch today?
SPX 7,700 — the reclaim. The round level just above Wednesday’s 7,651 close, and the first thing a gap-up open has to earn back and hold once the dust settles. Reclaim it AND hold it with the chips leading and the AI bid is winning the collision, opening the door toward 7,720 and higher. But this is a gap on AI earnings into a 24-year-high yield — don’t chase it. Make price take and hold 7,700 on real trade after the open and through the 10:00 ISM print before you trust the long side. SPX 7,651 — the axis. Wednesday’s close and the pivot the gap is built on. This is the ‘let it prove itself’ zone where a tape caught between AI euphoria and a bond rout tends to chop as ISM gets digested and the 10-year picks a direction. The real signal is which side SPX leaves 7,651 on once cash trades and the yield reaction sets in. Inside the range is noise; the move that matters follows the data. Patience beats chasing the gap here. SPX 7,600 — the shelf that keeps the fade contained. It’s the level that separates a healthy gap-and-hold from a failed gap that rolls over. Lose 7,600 with the 10-year pressing higher after ISM, and the tape opens to the next leg lower as the yield ceiling wins the collision. Below 7,600 the market is rejecting the AI bid and the job flips to capital preservation. Mark it, and respect it if it goes — a failed gap into rising yields is one of the cleaner short setups.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – October 1, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.