Thursday, October 1, 2026 · 4:30 PM ET · MTC Market Close
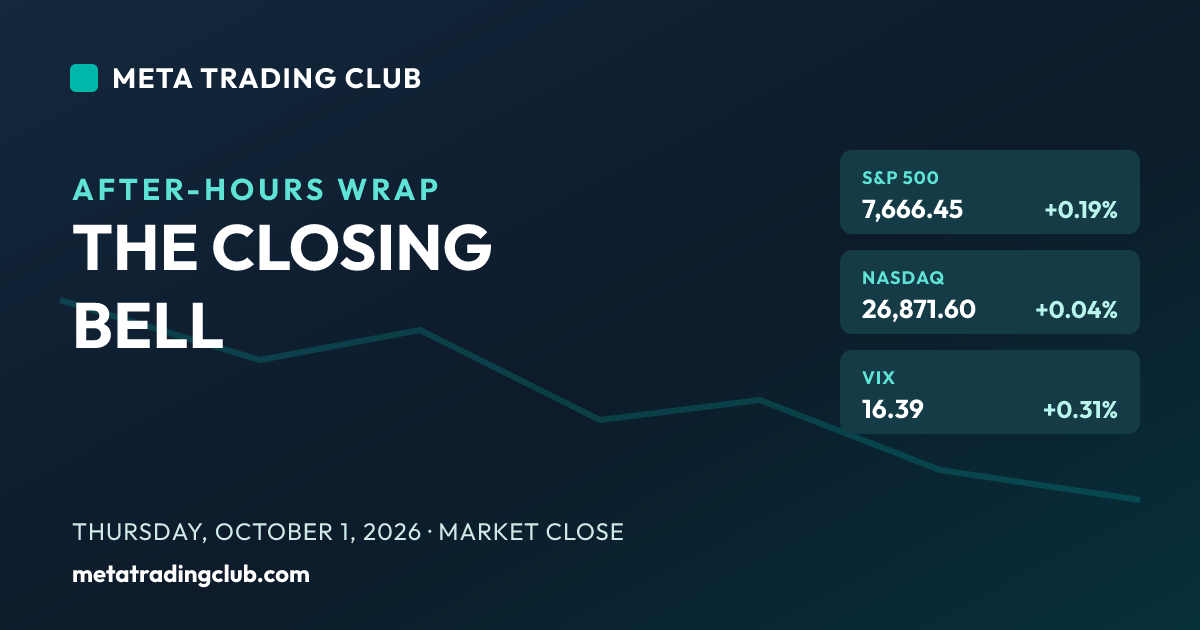
The stock market today opened October on a green note, but you had to squint to see it. The S&P 500 clawed back from a morning loss to close up 0.19% at 7,666.45, the Nasdaq added 0.04% to 26,871.60, and the Dow inched up 20 points to 50,926.56. The recovery had one driver: the 10-year Treasury yield backed off its 24-year high to 5.24%, which let the chip and AI trade bounce. Accenture led the tape with a 17% surge on a strong earnings beat, while Micron posted record quarterly results and still finished red, the classic sell-the-news tell that leadership isn’t fully confirming. Small caps did the most, with the Russell 2000 up 0.35% on the yield relief. This was a narrow, low-conviction green close that sits right under the round number at 7,700, and it hands Friday a clean binary: the September jobs report lands at 8:30 AM ET, the last major data point before the October 28 Fed meeting. A cool number keeps the yield relief alive and 7,700 comes into play; a hot one pushes yields back toward that 24-year high and caps the rally.
The Closing Bell
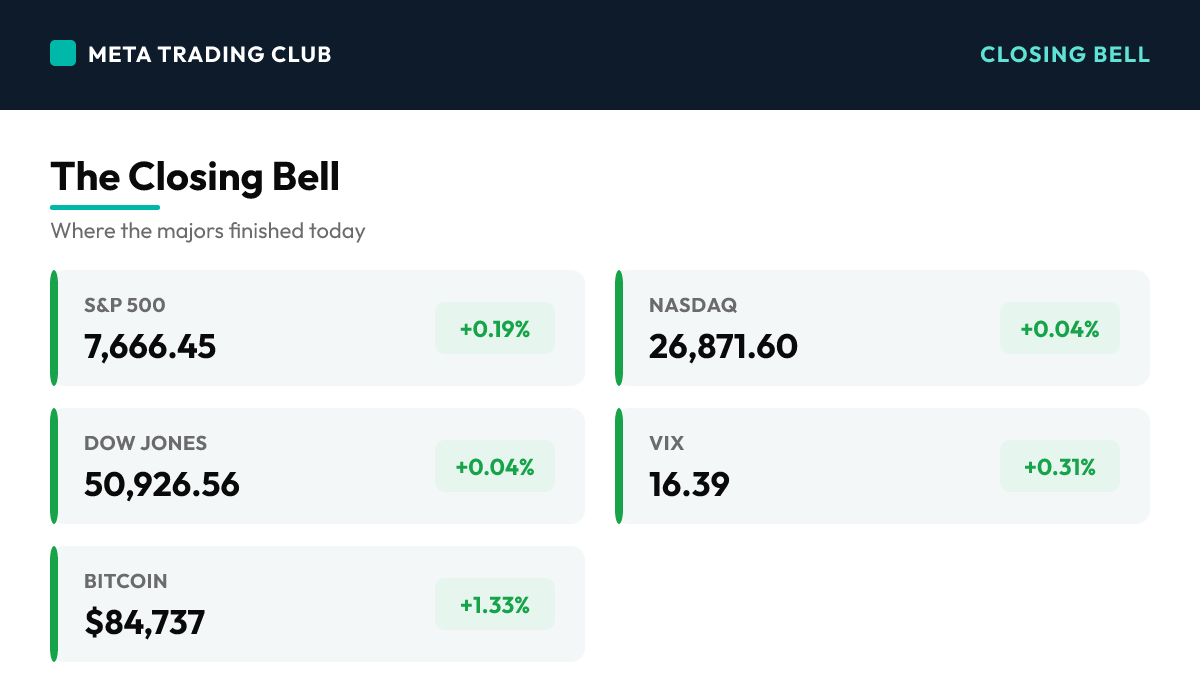
| Instrument | Close | Change | Note |
|---|---|---|---|
| S&P 500 | 7,666.45 | +0.19% | Clawed back from a morning loss to close up about 15 points at 7,666.45, the recovery driven almost entirely by the 10-year yield backing off its 24-year high. The index now sits just under the round number at 7,700, which makes that the single most important level on the page. The close was green but thin, and the real test comes Friday at 8:30 AM ET with the September jobs report. Reclaim 7,700 on a cool print and October’s buyers get room; stall here on a hot one and the yield ceiling wins. |
| Nasdaq | 26,871.60 | +0.04% | Barely held green, up about 11 points, as the chip and AI complex bounced back on the yield relief. Accenture’s 17% surge and firm semiconductor action did the lifting, but Micron’s record-but-red session shows the leadership wasn’t uniform. A near-flat close on a day the headline driver was duration relief tells you the growth trade got the backdrop it wanted and could only manage a grind, not a thrust. |
| Dow Jones | 50,926.56 | +0.04% | Inched up about 20 points to 50,926.56, essentially flat, with no single blue-chip catalyst to drive it either way. The Dow carries the least duration tailwind from the yield retreat, so on a day the move was all about rates easing, the blue-chip index had the least to gain. A flat close is a fair read of a low-conviction tape that recovered its losses but never found a reason to press higher. |
| Russell 2000 | 2,806.63 | +0.35% | The day’s relative leader among the majors, up about 10 points, the small-cap tell that the yield retreat mattered most to the most rate-sensitive corner of the market. With the 10-year backing off its 24-year high, borrowing-cost pressure eased at the margin and small caps caught the best bid. A 0.35% gain is modest, but it being the top of the board on a flat day confirms this was a rates-relief session, not a growth-led one. |
| VIX | 16.39 | +0.31% | Barely moved, ticking up a hair to hold near 16.4 even as the indices recovered. A calm, slightly firmer VIX on a green day is a quiet tell: the recovery was orderly but the market is not dropping its guard into Friday’s jobs report. Low volatility here does not mean low risk when a binary data print sits one session away. The reading says traders are hedged and waiting, not complacent. |
| 10-Year Yield | 5.24% | -6 bp | The real story of the day. The 10-year backed off about 6 basis points to 5.24% after touching a 24-year high earlier in the week, and that retreat is exactly why stocks could recover and the chip trade could bounce. The catch is that 5.24% is still deeply restrictive, and it took only a small move lower to lift the tape. That tells you how heavy the rate ceiling is, and why Friday’s jobs number matters so much for which way yields break next. |
| WTI Crude | $91.49 | +1.18% | Firmed about a dollar to hold near $91.49, the day’s best-performing corner of the commodity complex and the fuel behind energy’s sector-leading session. Crude caught a bid on supply-side positioning as the front-month pushed back above $91. A firmer oil tape is a double-edged read: good for energy stocks, but a reminder that the inflation story still has an energy component heading into Friday’s data. |
| Gold | $4,208.30 | +0.52% | Climbed about $22 to settle near $4,208 an ounce, catching a bid as the 10-year eased and real yields softened at the margin. After a volatile stretch, gold got the rate relief it needed, and a lower opportunity cost of holding a non-yielding asset let the metal firm. The move fits the day’s theme: anywhere duration or rates mattered, the easing in yields provided a tailwind. Level approximate into the settle. |
| Bitcoin | $84,737 | +1.33% | Firmed to near $84,737, up more than 1%, as the softer rate backdrop gave speculative assets a tailwind. Bitcoin leaned on the same yield-relief theme that lifted small caps and chips, and its gain outpaced the equity indices. On a quiet grind-higher day, crypto was one of the clearer beneficiaries of the move lower in the 10-year. Level approximate into the settle. |
Today’s Charts
Daily candlestick charts with 20/50/200-day moving averages — the index majors, the day’s biggest mover on each side, and the leading sector ETF.

Charts: Finviz (daily). Levels and overlays update through the next session.
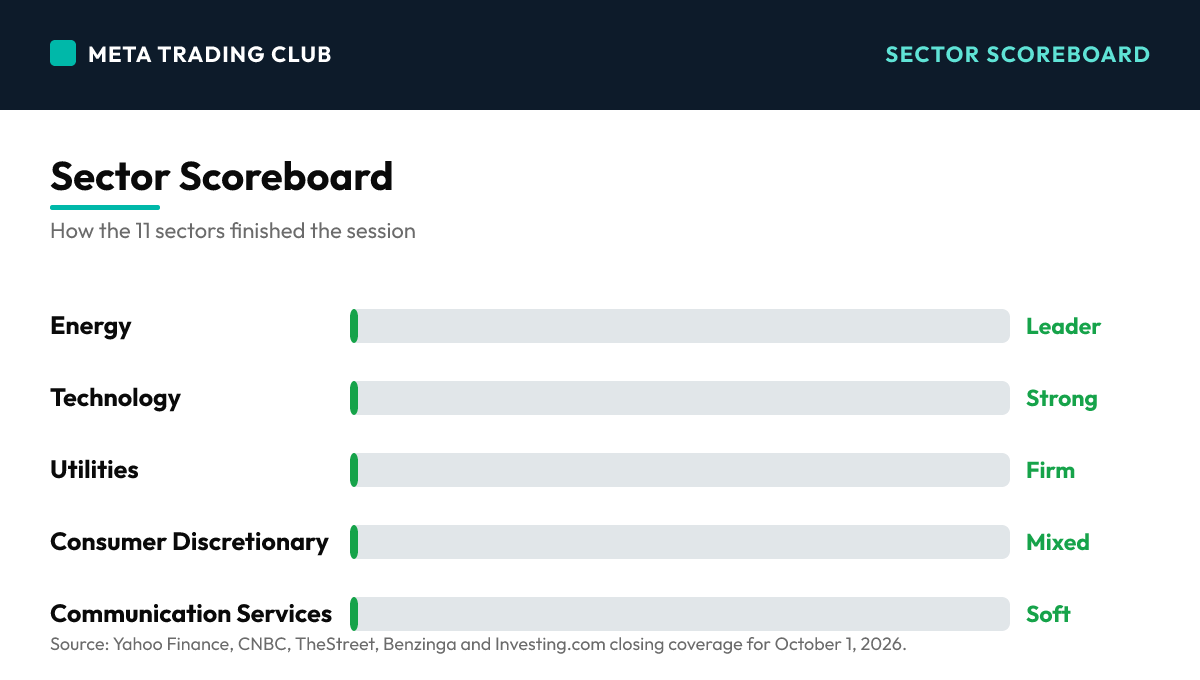
Sector Scoreboard
What Drove The Day
This was a recovery session with a single engine: rates. The S&P opened the month in the red, but as the 10-year backed off its 24-year high to 5.24%, the pressure on the long-duration growth trade eased and the chip and AI complex bounced, pulling the index back to a 0.19% gain. The order of strength told the whole story. Small caps led at 0.35% because they are the most rate-sensitive, the Nasdaq and Dow finished essentially flat, and the move was about yields easing, not earnings or breadth. Accenture’s 17% post-earnings surge was the day’s marquee single-stock win, while Micron’s record results closing red was the warning under the surface: the best news of the day could not lift its own stock. A slightly firmer VIX near 16.4 on a green day confirmed the tape was hedged and waiting, not confident. The recovery was real but thin, and it parked the S&P right under 7,700 with the September jobs report one session away.
MAJOR HEADLINES AND CATALYSTS
Top Market-Moving Stories
- YIELDS EASE, AND THE TAPE RECOVERS (Day) – The 10-year Treasury yield backed off about 6 basis points to 5.24% after touching a 24-year high earlier in the week, and that single move did the heavy lifting. It eased pressure on the long-duration growth trade, let the chip and AI complex bounce, and pulled the S&P back from a morning loss to a 0.19% gain. When a market needs a move in rates just to recover its losses, it tells you how heavy the rate ceiling has become.
- ACCENTURE SURGES 17% ON STRONG EARNINGS (Day) – Accenture was the day’s cleanest winner, surging about 17% after Q4 revenue of $18.68 billion beat its own guidance, bookings stayed strong, and the company guided fiscal 2027 local-currency revenue growth of 3% to 6%. It was a rare high-conviction single-stock catalyst on an otherwise low-conviction tape, and it carried the services and consulting corner of tech.
- MICRON’S RECORD RESULTS CLOSE RED (Day) – Micron delivered record fiscal 2026 results, with Q4 revenue of $54.23 billion and a Q1 guide well above expectations on tightening chip supply, yet the stock finished down about 1%. That is the sell-the-news tell: when the best earnings story of the day cannot lift its own stock, it is a warning that the leadership trade is crowded and the good news is already priced in.
- ALL EYES SHIFT TO FRIDAY’S JOBS REPORT (Day) – With the close in, the market’s full attention turns to the September employment report due Friday at 8:30 AM ET. Economists expect roughly 90,000 nonfarm payrolls and a 4.1% unemployment rate. Coming about four weeks before the October 28 Fed meeting, it is the last major data point to shape rate expectations, and it is the binary that decides whether today’s yield relief holds or reverses.
AFTER-HOURS EARNINGS SPOTLIGHT
Nike Beats on EPS but Guidance Sinks the Stock
- NIKE BEATS EPS, MISSES ON REVENUE AND GUIDANCE (AH) – Nike reported after the bell and beat on the bottom line, posting about $0.48 per share versus $0.44 expected, but revenue came in near $11.21 billion, just shy of estimates, and down about 4% year over year. The headline beat was not the story.
- THE GUIDANCE IS WHY THE STOCK FELL 5% (AH) – Shares dropped about 5% in the after-hours session as management guided fiscal 2027 adjusted EPS to a range well below what analysts expected and flagged a high-single-digit revenue decline ahead. This is the same lesson Micron taught during the regular session: when the forward guide disappoints, an EPS beat does not save the stock. The market trades the future, not the quarter that just closed.
WHAT IT SETS UP FOR FRIDAY
The Jobs Report Owns the Open
- SEPTEMBER PAYROLLS AT 8:30 AM ET IS THE BINARY (AH) – The September employment report is the single event that decides Friday’s tape. Consensus is for about 90,000 nonfarm payrolls and a 4.1% unemployment rate. A cool-to-in-line number keeps the yield relief that drove today alive and gives the S&P room to test 7,700. A hot print pushes the 10-year back toward its 24-year high, pressures the duration trade, and caps the recovery before it can extend.
- 7,700 IS THE LINE ON THE RECLAIM (AH) – The S&P closed at 7,666, parked just under the round number at 7,700. Reclaim and hold 7,700, ideally on a cool jobs print and calm yields, and today’s grind becomes the start of an October bounce with buyers in control. Fail there, or lose 7,620 on a hot number, and the thin, rates-dependent nature of today’s recovery becomes the story, opening 7,600 as the next shelf.
Winners & Losers
Winners
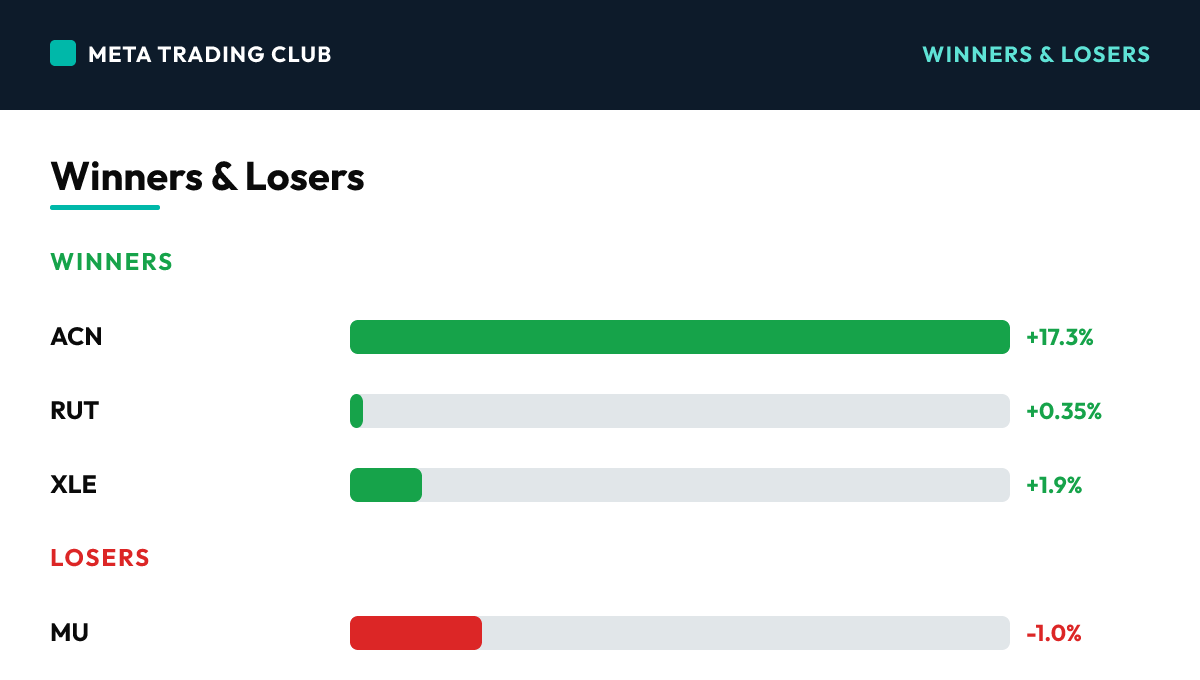
| ACN | +17.3% | Accenture was the day’s cleanest and biggest winner, surging about 17% after Q4 revenue of $18.68 billion beat its own guidance range, bookings came in strong at $22.2 billion for the quarter, and the company guided fiscal 2027 local-currency revenue growth of 3% to 6%. It was the rare high-conviction single-stock catalyst on a low-conviction tape and led the consulting and services corner of tech. | |
| RUT | +0.35% | Small caps, as a group, were the relative winners of the session, with the Russell 2000 topping the major-index board on the yield retreat. As the most rate-sensitive corner of the market, small caps caught the best bid when the 10-year backed off its 24-year high, the clearest sign that this was a rates-relief day rather than a growth-led one. | |
| XLE | +1.9% | The energy sector ETF was among the day’s strongest, rising close to 2% as WTI crude firmed back above $91. Energy was the one group working on a genuine commodity bid rather than the rates-relief theme that drove the rest of the tape, which made it the standout sector on an otherwise narrow, grind-higher session. |
Losers
| MU | -1.0% | Micron delivered record fiscal 2026 results, with Q4 revenue of $54.23 billion and a Q1 guide well above expectations on tightening chip supply, and still finished down about 1%. That is the sell-the-news tell: when the best earnings story of the day cannot lift its own stock, the leadership trade is crowded and the good news is already in the price. The single clearest warning under an otherwise green tape. | |
| NKE | -5.0% | Nike fell about 5% in the after-hours session despite beating on EPS, dragged down by a weak fiscal 2027 guide that put adjusted EPS well below expectations and flagged a high-single-digit revenue decline. The move is the after-hours version of the day’s lesson: an earnings beat does not save a stock when the forward guidance disappoints. Move reflects the post-close reaction. | |
| XLC | -0.3% | Communication Services leaned lower, one of the groups that could not ride the duration-relief bid despite its growth tilt. On a narrow day where the gains concentrated in energy and chips, the broader communication names drifted, a reminder that the recovery was selective rather than broad. Move approximate. |
What It Sets Up For Tomorrow
Levels Into Tomorrow
- S&P 500 7,700 – THE LINE THAT DECIDES IT. Price closed at 7,666.45, sitting just under the round number at 7,700 after clawing back from a morning loss. This is the single most important level on the page. Reclaim 7,700 and hold it, ideally on a cool jobs print keeping yields calm, and today’s grind becomes the start of an October bounce with buyers keeping control. Fail there and the sellers keep the upper hand. The first clean move relative to 7,700 after the 8:30 AM data tells you who owns the tape to start the month.
- S&P 500 7,620 – THE SHELF THAT MUST HOLD. The first real support below the close and the line that keeps today’s recovery intact. As long as the S&P holds 7,620, the thin green close stays a constructive base and the rates-relief trade stays alive. Lose 7,620, especially if the jobs report runs hot and yields push back toward their 24-year high, and the market is telling you today’s bounce was rate-dependent and fragile, opening 7,600 then 7,550.
- S&P 500 7,600 – THE NEXT STOP LOWER. The deeper support if 7,620 gives way. A loss of 7,600 on a hot jobs number would confirm that the yield ceiling at 5.24% is capping the tape and that today’s recovery was borrowed, not earned. This is where the rates-dependent nature of the bounce would become the dominant story, and the most rate-sensitive groups would likely lead the move lower.
Bull case: Today showed the market wants to go up the moment rates give it room. The 10-year backed off its 24-year high, and that was all it took for the chip trade to bounce and the S&P to recover a morning loss. If Friday’s jobs report comes in cool or in line, yields stay calm, the duration relief broadens out, and 7,700 comes into play with small caps and semis leading. Accenture’s 17% surge proves there is still appetite to pay up for clean earnings stories. A calm, slightly firmer VIX says the market is hedged and patient, not fearful, and patient markets with a rates tailwind are where October bounces get built.
Bear case: A recovery that needs a move in yields just to get back to flat is a fragile one. The 10-year is still at 5.24%, a hair off a 24-year high, and the whole bounce was leaning on that single thread. Micron posting record results and still closing red, and Nike dropping 5% after hours on weak guidance, both say the market is quick to sell any crack in the forward story. If Friday’s payrolls run hot, yields push back up, the duration relief evaporates, and the S&P loses 7,620 with the most rate-sensitive groups leading. That turns today’s thin green close into the start of a rates-driven pullback toward 7,600 and 7,550.
Risks Into Tomorrow
- When a market needs lower yields just to recover, the rate ceiling is the story — Today the S&P opened in the red and only clawed back to green after the 10-year backed off its 24-year high. That is the whole session in one sentence. The recovery was not built on earnings, broad breadth, or new money, it was built on a six-basis-point move in rates. The lesson is to watch what the market needs to go up, not just whether it goes up. A tape that requires a yield move to recover a morning loss is telling you the rate ceiling at 5.24% is the dominant force, and that leaves the bounce dependent on a single variable. That is exactly why Friday’s jobs report matters more than today’s green close. When the move depends entirely on one thread, you wait for that thread to confirm before you trust the rally. No alignment between price and a durable driver means you stay patient and let the level, 7,700, pick the side.
- Sell-the-news is a tell, and today you got it twice — Micron posted record results and closed red. Nike beat on EPS and dropped 5% after hours. Two of the day’s biggest earnings stories, both with a headline beat, and both sold. That is not a coincidence, it is a signal about positioning. When good earnings cannot lift a stock, it means the good news was already priced in and the market is trading the forward guide, not the quarter that just closed. This is a repeatable tell you can use. When a name beats and still falls, do not fight the tape by buying the beat, read the reaction and respect it. The reaction is the market voting with real money on what comes next, and it is almost always more informative than the headline number. Today the reaction said the leadership trade is crowded and the forward outlook is what matters. The discipline is to trade the response, not the report.
- A calm VIX before a binary event is patience, not permission — The VIX barely moved today, ticking up slightly to hold near 16.4 even as the indices recovered. On the surface that reads as calm, but a quiet VIX the day before the September jobs report is not an all-clear, it is a market that is hedged and waiting. The mistake is to read low volatility as low risk and chase the green close into a binary data print. Volatility is low precisely because the outcome is unknown and traders are positioned for it, not because the risk has passed. The plan is to separate the volatility gauge from the event on the calendar. A calm VIX in front of a jobs report that can send yields in either direction is a reason to size down and wait for the number, not a reason to lean in. The discipline is to let the data land, see how price reacts at 7,700, and then act. No alignment until the catalyst clears.
Frequently Asked Questions
How did the S&P 500 close today?
On Thursday, October 1, 2026, the S&P 500 closed at 7,666.45 (+0.19%), with the VIX at 16.39. The stock market today opened October on a green note, but you had to squint to see it.
What drove the market today?
YIELDS EASE, AND THE TAPE RECOVERS (Day) – The 10-year Treasury yield backed off about 6 basis points to 5.24% after touching a 24-year high earlier in the week, and that single move did the heavy lifting. It eased pressure on the long-duration growth trade, let the chip and AI complex bounce, and pulled the S&P back from a morning loss to a 0.19% gain. When a market needs a move in rates just to recover its losses, it tells you how heavy the rate ceiling has become.
What levels matter for tomorrow?
S&P 500 7,700 – THE LINE THAT DECIDES IT. Price closed at 7,666.45, sitting just under the round number at 7,700 after clawing back from a morning loss. This is the single most important level on the page. Reclaim 7,700 and hold it, ideally on a cool jobs print keeping yields calm, and today’s grind becomes the start of an October bounce with buyers keeping control. Fail there and the sellers keep the upper hand. The first clean move relative to 7,700 after the 8:30 AM data tells you who owns the tape to start the month. S&P 500 7,620 – THE SHELF THAT MUST HOLD. The first real support below the close and the line that keeps today’s recovery intact. As long as the S&P holds 7,620, the thin green close stays a constructive base and the rates-relief trade stays alive. Lose 7,620, especially if the jobs report runs hot and yields push back toward their 24-year high, and the market is telling you today’s bounce was rate-dependent and fragile, opening 7,600 then 7,550. S&P 500 7,600 – THE NEXT STOP LOWER. The deeper support if 7,620 gives way. A loss of 7,600 on a hot jobs number would confirm that the yield ceiling at 5.24% is capping the tape and that today’s recovery was borrowed, not earned. This is where the rates-dependent nature of the bounce would become the dominant story, and the most rate-sensitive groups would likely lead the move lower.
How does Meta Trading Club prepare for the next session?
We wrap every session and carry the read forward through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
New to this? Start with the free training.
Learn how we read the market before you risk a dollar — our free education library and ebook break down the fundamentals step by step.
Free education → Get the free ebookThe session’s over. The prep isn’t.
This is how MTC members close each day — wrap what happened, mark the levels, and carry one clean read into tomorrow. If you want to build that habit and qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process. It’s application-based — see if it’s a fit.
Explore the MTC Incubator → Apply nowSources: Yahoo Finance, CNBC, TheStreet, Benzinga and Investing.com closing coverage for October 1, 2026.. For educational purposes only. Not financial advice.