Friday, September 18, 2026 · 8:45 AM ET · MTC Market Intelligence
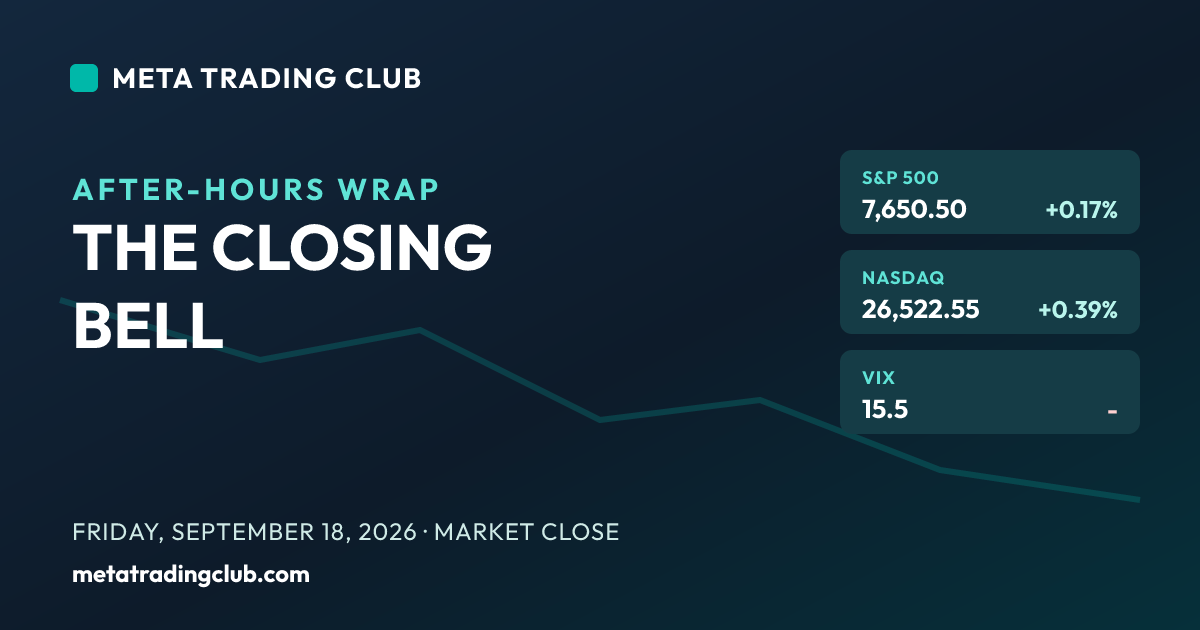
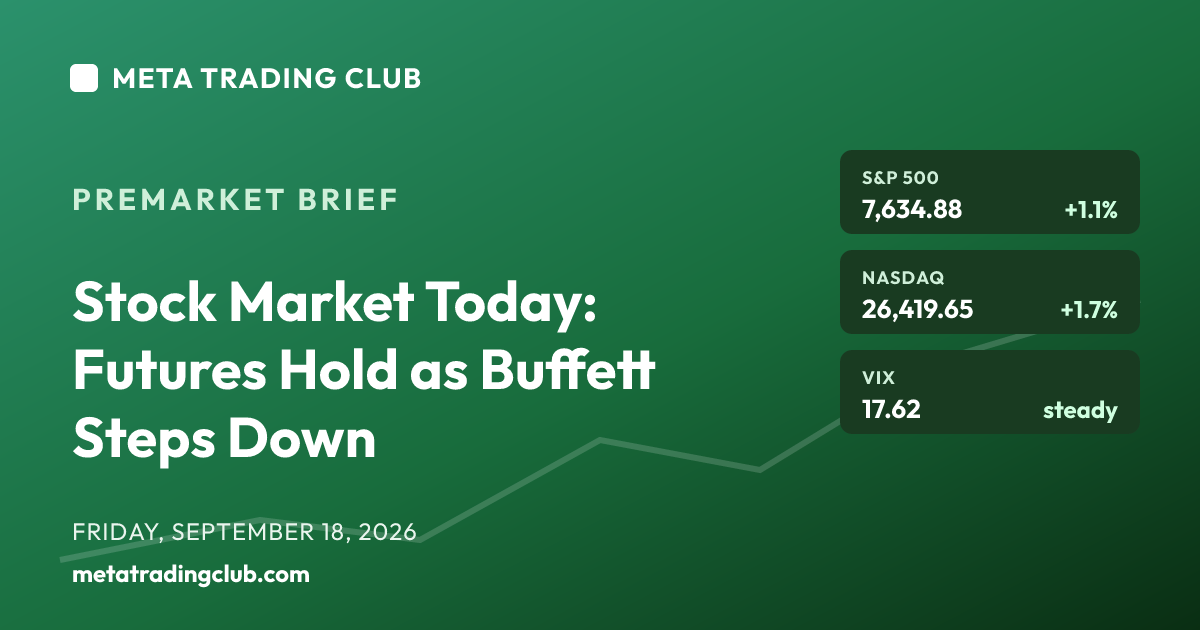
The stock market today is trying to close the week on the front foot. Thursday the tape did exactly what a healthy bounce is supposed to do — the opening gap got sold, and then buyers stepped in and lifted it all day. The S&P 500 rallied 1.1% to about 7,635, the Nasdaq Composite jumped 1.7% to roughly 26,420, and the Dow added 316 points, or 0.6%, to near 51,778. Breadth was solid at 63% advancing, semis (SMH) ran close to 3%, and the Mag7 led. The one crack: the Russell 2000 closed at the lows of the day with just a 0.6% gain — small caps did not confirm. The reason the bounce got legs is the single number that matters right now: the 10-year yield stabilized at 4.93% after tagging 5.01%, a 19-year high, on Wednesday. Yields held under 5%, and that let the chips and the big-cap tech names catch a bid. This morning futures are steady-to-higher — S&P +0.1%, Nasdaq-100 +0.4% leading, Dow flat — with oil down a third straight day near $100.70 and yields still calm. Two wildcards define the session. First, it is triple witching — the quarterly expiration of stock options, index futures and index options all at once — which means heavier volume, pinning around big strikes, and sharp, headline-free swings into the 4:00 close. Second, Warren Buffett announced he is stepping down as Berkshire chairman, handing the role to his son Howard while staying on as chairman emeritus. Here is the honest scorecard for the week: yields held their level, semis held leadership, but small caps failed their test. That is a bounce that passed most of its exams — not all of them. So the job today is simple. Let SPX prove it can hold 7,635 and push 7,700, respect 7,550 as the line that keeps Thursday’s gains intact, and do not let triple-witching noise bait you into a trade the level hasn’t confirmed. No alignment, no trade.
Market Snapshot
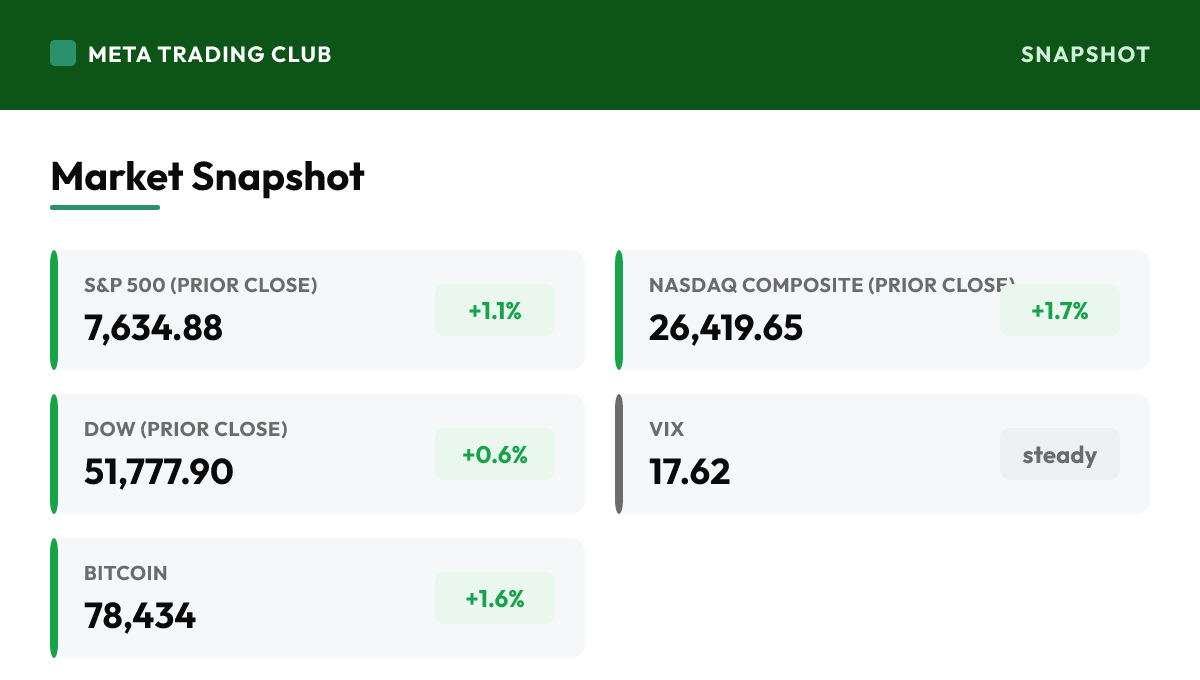
| Instrument | Level | Change | Note |
|---|---|---|---|
| S&P 500 (prior close) | 7,634.88 | +1.1% | Rallied about 1.1% Thursday to roughly 7,635 in a textbook bounce — the opening gap got sold, then buyers carried it higher all session. That close is the pivot the morning rotates around. The move earned trust because it built through the day rather than fading; the question now is whether it can push through 7,700 or stalls under it into expiration. |
| Nasdaq Composite (prior close) | 26,419.65 | +1.7% | Jumped roughly 1.7% Thursday to near 26,420, the clear leader as semis (SMH close to +3%) and the Mag7 did the heavy lifting. This is where the bounce announced itself, and it’s leaning on the same names that lead every rally. Genuine leadership — but narrow, and only as durable as the 10-year staying under 5%. |
| Dow (prior close) | 51,777.90 | +0.6% | Added 316 points, or 0.6%, Thursday to about 51,778, participating but not leading as financials steadied after Wednesday’s drubbing. The banks stabilizing is a quiet positive — it means the bounce wasn’t just a tech story. Berkshire is the name to watch here today on the Buffett succession headline. |
| S&P 500 Futures | — | +0.1% | Up about 0.1%, barely green as the tape tries to extend Thursday’s gains into the weekend. Don’t read much into a flat premarket on triple-witching Friday — the real move comes from expiration flows and how SPX handles 7,700. The signal isn’t the open; it’s whether price can hold the 7,635 pivot once cash trades. |
| Nasdaq-100 Futures | — | +0.4% | Up about 0.4%, leading the premarket again as semis and megacap tech keep the bid. This is the corner still doing the work. Intel is higher on SK hynix headlines and the chip complex is firm — but treat tech strength as the highest-beta bet on yields staying calm, up and down. |
| Dow Futures | — | -0.1% | Roughly flat to slightly lower, the laggard of the three this morning. After leading Wednesday’s damage and stabilizing Thursday, the blue chips have the most to prove on follow-through. Berkshire and the financials are the tell — if they hold up on the Buffett news and steady yields, the broad-market bounce stays intact. |
| Russell 2000 Futures | — | flat | Roughly flat after the small-cap index closed Thursday at the lows of the day with only a 0.6% gain — the one group that did NOT confirm the bounce. Small caps are the most rate-sensitive corner of the market, and their refusal to lead is the clearest crack under an otherwise strong tape. Watch them for the honest read on breadth. |
| VIX | 17.62 | steady | Holding near 17.62, still elevated but off the panic readings around the Fed. The fear premium is slowly bleeding out as yields stabilize. One caveat: triple witching can jolt vol intraday regardless of the trend — expect sharp, mechanical swings into the close that say more about expiration flows than about real risk. |
| WTI Crude | 100.70 | -1.2% | Down about 1.2% to $100.70, a third straight daily decline as easing Saudi supply worries outweigh the Saudi-Houthi strikes still hitting the region. Softer oil takes a little pressure off the inflation-and-yield loop that forced the Fed’s hand — a genuine tailwind for stocks at the margin, as long as crude stays under control. |
| 10-Yr Yield | 4.93% | lower | Sitting near 4.93% after tagging 5.01% — a 19-year high — on Wednesday, then easing about 7bp Thursday. This is the single most important number on the screen. Yields stabilizing under 5% is exactly what let the chips and big-cap tech catch a bid. Hold here and the bounce has a foundation; press back over 5% and the ceiling returns. |
| Bitcoin | 78,434 | +1.6% | Up about 1.6% near $78,400, firming with the broader risk-on tone as yields calm and oil eases. Crypto trading with the tape rather than against it is a small confirmation that the post-Fed relief is real. Steady, not euphoric — the right posture with the Fed still signaling one more hike this year. |
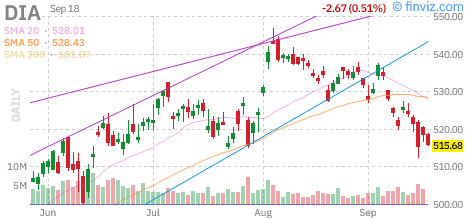
Charts to Watch
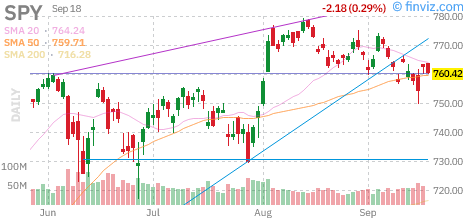
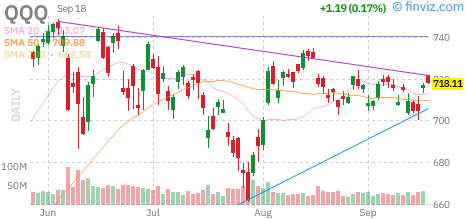
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
Overnight & Global Markets
Thursday was a clean bounce off Wednesday’s post-Fed selloff. The opening gap got sold, then buyers stepped in and lifted the tape into the close: the S&P 500 rose about 1.1% to roughly 7,635, the Nasdaq Composite jumped 1.7% to near 26,420, and the Dow added 316 points, or 0.6%, to about 51,778. Breadth was solid at 63% advancing, semis (SMH) ran close to 3%, and the Mag7 led — but the Russell 2000 closed at the lows of the day with just a 0.6% gain, the one group that failed to confirm. The move worked because the 10-year yield stabilized at 4.93% after hitting a 19-year high near 5.01% on Wednesday; yields holding under 5% let chips and big-cap tech catch a bid. This morning futures are steady-to-higher — S&P +0.1%, Nasdaq-100 +0.4% leading, Dow flat — with WTI down a third straight day near $100.70 and yields still calm. Two wildcards frame the session: it’s triple witching, so expect heavier volume and pinning into the 4:00 close, and Warren Buffett announced he’s stepping down as Berkshire chairman. The bounce passed most of its tests — yields held, semis led — but small caps didn’t. Today is about whether SPX can hold 7,635 and push 7,700, not chasing expiration noise.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The post-Fed bounce is holding, and the reason is the bond market. After Wednesday’s 25bp hike to 3.75%-4.00% — the first since 2023 — the 10-year yield spiked to 5.01%, a 19-year high, then eased back to 4.93% on Thursday. That stabilization under 5% is what let semis and megacap tech catch a bid and drive a 1.1% S&P rally. Yields are the whole ballgame right now: hold under 5% and the bounce has a foundation; press back above it and the ceiling returns.
- Today is triple witching — the quarterly simultaneous expiration of stock options, stock-index futures and stock-index options that happens on the third Friday of March, June, September and December. Practically, that means heavier-than-normal volume, price pinning around large open-interest strikes, and sharp, mechanical swings into the 4:00 close that often have nothing to do with news. Respect it: expiration flows can override the trend intraday, so don’t over-read a move that’s really just contracts settling.
- Warren Buffett is stepping down as Berkshire Hathaway chairman. The 96-year-old announced in a letter to shareholders that he’ll become chairman emeritus effective immediately while remaining on the board, with his son Howard Buffett taking the chairman role and Greg Abel continuing as CEO. It’s a long-telegraphed succession, not a shock, but it puts Berkshire in focus today and marks the end of an era for the most-watched capital allocator in the market. Expect the headline to drive BRK more than the tape.
Stock-Specific
- Semis stay the cleanest strength. Intel (INTC) is up about 1.15% premarket near $110 on reports of talks with SK hynix, adding to a chip complex that ran close to 3% Thursday. The AI and semiconductor trade is still the market’s preferred place to be when yields cooperate — it’s the group leading the bounce, and its follow-through today is a direct read on whether the risk-on tone survives triple witching.
- Lennar (LEN) is the earnings tell that matters. The homebuilder fell about 1.6% premarket after missing on both revenue and EPS, reporting new-home deliveries down 3%, and cutting its fiscal-2026 delivery guidance while citing ‘deterioration’ in market conditions. That’s the real economy talking: a near-5% 10-year is squarely aimed at housing demand, and Lennar’s guidance cut is the clearest sign yet that higher-for-longer rates are biting the rate-sensitive parts of the economy.
- On the movers list, Xenon Pharmaceuticals (XENE) is the standout loser, down more than 26% premarket after pausing enrollment in a psychiatry trial over neuropsychiatric adverse events — a clean, single-name biotech story, not a market tell. Lockheed Martin (LMT) is modestly higher after the Trump administration approved a $24.3 billion sale of 48 F-35 jets to Saudi Arabia. Treat both as texture; the tape is trading yields, expiration and the Buffett headline, not these prints.
Global and Macro
- Oil is cooling, and that helps. WTI fell about 1.2% to $100.70, a third straight daily decline, as easing Saudi supply worries outweigh the Saudi-Houthi strikes still hitting the region. Softer crude takes pressure off the inflation-and-yield loop that forced the Fed’s hand — it’s a genuine tailwind for stocks at the margin. The regime only really shifts if oil breaks meaningfully below $100 and stays there, but the direction of travel this week is finally the market’s friend.
- The data and Fedspeak keep the rate story front and center. Industrial Production is on the calendar this morning, and Fed Governor Michelle Bowman is scheduled to speak — the first policymaker commentary since Wednesday’s hike, so any nuance on the ‘one more hike’ path will move yields. With the Fed still signaling another increase before year-end, the market’s read on that path — visible in the 10-year — matters more than any single equity headline today.
TECHNICAL ANALYSIS
S&P 500 Key Levels
- The S&P closed Thursday near 7,635, and that level is the axis the morning rotates around. On the upside, 7,700 is the level that matters — reclaim and hold it and the bounce extends toward the 7,714 futures high and beyond, telling you buyers are willing to press the rally into the weekend. But this is triple witching: don’t chase a pop toward 7,700 on expiration flows. Make SPX take and hold the level on real trade before you trust it.
- First support is the 7,635 pivot, then the line that keeps Thursday’s gains intact: 7,550. Hold above 7,635 and the bounce stays healthy and two-way; lose 7,550 and Thursday’s rally starts to unwind toward 7,500, with the post-Fed caution back in play. Mark 7,700 above and 7,550 below — between them is expiration noise, outside them is the real signal. The middle is where triple witching pins price; the edges are where the trade lives.
Sector and Sentiment
- The leadership tell is semis versus small caps. Chips (SMH) ran close to 3% Thursday and lead again this morning, but the Russell 2000 closed at the lows with just a 0.6% gain. That split is the story: a rally carried by megacap tech while small caps refuse to confirm is a strong index masking thin breadth. For the bounce to be durable, you want to see the laggards — small caps, homebuilders — start to participate, not just the same narrow leaders.
- The VIX near 17.62 is calming as yields stabilize, but triple witching adds a mechanical wildcard. Expect vol to jolt intraday around the expiration and the 4:00 close in ways that don’t reflect the underlying trend. Practically: respect fast, headline-free swings, don’t confuse an expiration-driven move for a change in direction, and let a level hold on real volume before you lean on it. Patience beats reacting to noise on a day like today.
TODAY’S ECONOMIC CALENDAR
Key Releases (ET)
- Industrial Production is the morning’s scheduled data, a read on the manufacturing side of the economy that gets extra weight now that the Fed is tightening into what it calls a still-firm economy. The bigger variable is Fed Governor Michelle Bowman’s commentary — the first policymaker to speak since Wednesday’s hike. Any signal on how committed the Fed is to ‘one more hike’ will move the 10-year, and the 10-year is what’s driving stocks this week.
- Layered on top is triple witching, which is really a flow event, not a data event. The quarterly expiration concentrates volume and can pin price to big strikes through the session before a burst of activity into the 4:00 close. Let the rates reaction — not the first equity print or an expiration-driven wobble — guide your read of the day. A move that holds on real volume matters; a move that’s just contracts settling doesn’t.
Earnings Today
- Lennar (LEN) is the earnings read that counts today. The homebuilder missed on revenue and EPS, reported deliveries down 3%, and cut its fiscal-2026 delivery guidance while citing ‘deterioration’ in market conditions. On a week where the Fed just hiked and the 10-year is near 5%, a homebuilder flagging softening demand is the clearest evidence that higher-for-longer rates are hitting the real economy where it’s most rate-sensitive. Listen to the guidance, not just the headline miss.
- The heavier earnings flow comes next week — AutoZone (AZO) reports Tuesday, with General Mills (GIS) and Cintas (CTAS) mid-week giving fresh reads on the consumer and industrial demand. For today, treat earnings as texture. The tape is trading yields, the Buffett headline and expiration flows, not single-name prints. Where earnings matter is as a check on the macro question underneath everything: is demand slowing enough to make the Fed pause, or not?
PREMARKET PLAYBOOK
Key Levels
- SPX 7,700 — the upside proof. This is the level that turns Thursday’s bounce into a genuine push higher. Reclaim it AND hold it on real trade and the tape opens the door to the 7,714 futures high and beyond, telling you buyers are willing to press the rally into the weekend. But it’s triple witching — don’t chase a pop toward it on expiration flows. Make price take and hold the level on volume before you trust the long side.
- SPX 7,635 — the pivot. Thursday’s close and the axis the morning rotates around. Hold above it and the bounce stays healthy and two-way, ready to resolve higher; this is the ‘let it prove itself’ zone where triple witching tends to pin price. The real signal is which side SPX leaves this level on into the afternoon. Patience beats prediction inside the range — let the tape show its hand.
- SPX 7,550 — the line that keeps the gains. Lose it and Thursday’s rally starts to unwind toward 7,500, with the post-Fed caution and a near-5% 10-year back in the driver’s seat. Below 7,550 the bounce is failing its follow-through test and the job flips toward capital preservation. This is the number that separates a healthy consolidation from a rally that gives itself back — mark it, and respect it if it goes.
Bull case: Yields keep stabilizing under 5%, oil stays soft, and the bounce broadens. SPX reclaims and holds 7,700, the financials that steadied Thursday keep participating, semis hold leadership, and — the real tell — small caps finally start to join. In this scenario Wednesday’s selloff was the clearing event, the ‘one more hike’ is treated as manageable, and Thursday’s rally builds into a durable recovery that carries into next week rather than fading with expiration.
Bear case: Triple-witching flows and a hawkish Bowman drag the tape. The 10-year presses back toward 5%, the narrow leadership cracks as semis stall, small caps keep failing, and SPX loses the 7,635 pivot and then 7,550 into a give-back toward 7,500. In this scenario Thursday’s bounce was a one-day relief inside an unchanged tightening regime, the Lennar guidance cut is the leading edge of a real demand slowdown, and the path of least resistance turns lower into the weekend.
Premarket Movers
Gainers
| INTC | Intel | higher on SK hynix talks and firm semis | Up about 1.15% premarket near $110 on reports of talks with SK hynix, riding a chip complex that ran close to 3% Thursday. It’s a beta play on the one theme with real leadership right now — semis — rather than a pure company story. Treat it as a read on risk appetite inside the chip trade: if the AI and semiconductor bid holds through the open, the bounce keeps its leader; if it fades, watch the whole tape wobble. |
| LMT | Lockheed Martin | up on approved $24.3B Saudi F-35 sale | Modestly higher premarket after the Trump administration approved a $24.3 billion sale of 48 F-35 jets to Saudi Arabia, along with engines and parts. A clean, catalyst-driven defense story tied to rising Middle East tension — the Saudis are facing intensifying Houthi attacks. It’s a single-name move, but a reminder that geopolitics is still a live undercurrent under a tape that’s mostly focused on yields and the Fed this week. |
Laggards
| XENE | Xenon Pharmaceuticals | down 26%+ on paused psychiatry trial | Off more than 26% premarket after pausing enrollment in a psychiatry trial over neuropsychiatric adverse events. A clean, binary biotech story — clinical risk playing out exactly as it does in the group — and not a read on the broader market. Mentioned as the day’s standout single-name loser, but it carries no signal for the index; the tape is trading yields, expiration and the Buffett headline, not one biotech’s trial setback. |
| LEN | Lennar | lower on earnings miss and guidance cut | Down about 1.6% premarket after missing revenue and EPS, reporting deliveries down 3%, and cutting fiscal-2026 delivery guidance on ‘deterioration’ in market conditions. Unlike the biotech move, this one IS a market tell: it’s the housing read on what a near-5% 10-year does to rate-sensitive demand. Watch homebuilders and small caps around it — if the group leaks, it confirms the breadth problem sitting under an otherwise strong index. |
Risks Into the Open
- Primary risk: letting triple witching trade you. Today’s quarterly expiration concentrates volume, pins price to big strikes, and produces sharp, headline-free swings into the 4:00 close. The mistake is reacting to an expiration-driven move as if it’s a real trend change. Let SPX hold or lose a level on genuine volume before you act — a wobble that’s just contracts settling is noise, not signal, and chasing it is how good setups turn into bad trades on a day like this.
- The breadth problem is the real caution under a strong tape. Thursday’s 1.1% S&P rally was led by semis and the Mag7 while the Russell 2000 closed at the lows with just a 0.6% gain — small caps did not confirm. A rally carried by a narrow group over thin breadth is more fragile than the index level suggests. The confirmation you want is the laggards joining; until small caps and homebuilders participate, treat the bounce as top-heavy and vulnerable to a fast unwind.
- The backdrop is improving but not resolved. Yields stabilized under 5% and oil is cooling — both real tailwinds — but the Fed still signaled one more hike this year, the 10-year is only a few bp below a 19-year high, and Lennar just flagged demand deterioration. The regime hasn’t flipped from tightening to easing; it’s paused. Respect that a hawkish Bowman comment or a push back over 5% on the 10-year can put the ceiling right back over the tape.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Friday, September 18, 2026, S&P 500 futures are at 7,634.88 (+1.1%), with the VIX near 17.62. The stock market today is trying to close the week on the front foot. Thursday the tape did exactly what a healthy bounce is supposed to do — the opening gap got sold, and then buyers stepped in and lifted it all day. The S&P 500 rallied 1.1% to about 7,635, the Nasdaq Composite jumped 1.7% to roughly 26,420, and the Dow added 316 points, or 0.6%, to near 51,778. Breadth was solid at 63% advancing, semis (SMH) ran close to 3%, and the Mag7 led. The one crack: the Russell 2000 closed at the lows of the day with just a 0.6% gain — small caps did not confirm. The reason the bounce got legs is the single number that matters right now: the 10-year yield stabilized at 4.93% after tagging 5.01%, a 19-year high, on Wednesday. Yields held under 5%, and that let the chips and the big-cap tech names catch a bid. This morning futures are steady-to-higher — S&P +0.1%, Nasdaq-100 +0.4% leading, Dow flat — with oil down a third straight day near $100.70 and yields still calm. Two wildcards define the session. First, it is triple witching — the quarterly expiration of stock options, index futures and index options all at once — which means heavier volume, pinning around big strikes, and sharp, headline-free swings into the 4:00 close. Second, Warren Buffett announced he is stepping down as Berkshire chairman, handing the role to his son Howard while staying on as chairman emeritus. Here is the honest scorecard for the week: yields held their level, semis held leadership, but small caps failed their test. That is a bounce that passed most of its exams — not all of them. So the job today is simple. Let SPX prove it can hold 7,635 and push 7,700, respect 7,550 as the line that keeps Thursday’s gains intact, and do not let triple-witching noise bait you into a trade the level hasn’t confirmed. No alignment, no trade.
What is the biggest catalyst for the market today?
The post-Fed bounce is holding, and the reason is the bond market. After Wednesday’s 25bp hike to 3.75%-4.00% — the first since 2023 — the 10-year yield spiked to 5.01%, a 19-year high, then eased back to 4.93% on Thursday. That stabilization under 5% is what let semis and megacap tech catch a bid and drive a 1.1% S&P rally. Yields are the whole ballgame right now: hold under 5% and the bounce has a foundation; press back above it and the ceiling returns.
What key levels should traders watch today?
SPX 7,700 — the upside proof. This is the level that turns Thursday’s bounce into a genuine push higher. Reclaim it AND hold it on real trade and the tape opens the door to the 7,714 futures high and beyond, telling you buyers are willing to press the rally into the weekend. But it’s triple witching — don’t chase a pop toward it on expiration flows. Make price take and hold the level on volume before you trust the long side. SPX 7,635 — the pivot. Thursday’s close and the axis the morning rotates around. Hold above it and the bounce stays healthy and two-way, ready to resolve higher; this is the ‘let it prove itself’ zone where triple witching tends to pin price. The real signal is which side SPX leaves this level on into the afternoon. Patience beats prediction inside the range — let the tape show its hand. SPX 7,550 — the line that keeps the gains. Lose it and Thursday’s rally starts to unwind toward 7,500, with the post-Fed caution and a near-5% 10-year back in the driver’s seat. Below 7,550 the bounce is failing its follow-through test and the job flips toward capital preservation. This is the number that separates a healthy consolidation from a rally that gives itself back — mark it, and respect it if it goes.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – September 18, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.