Monday, October 5, 2026 · 4:30 PM ET · MTC Market Close
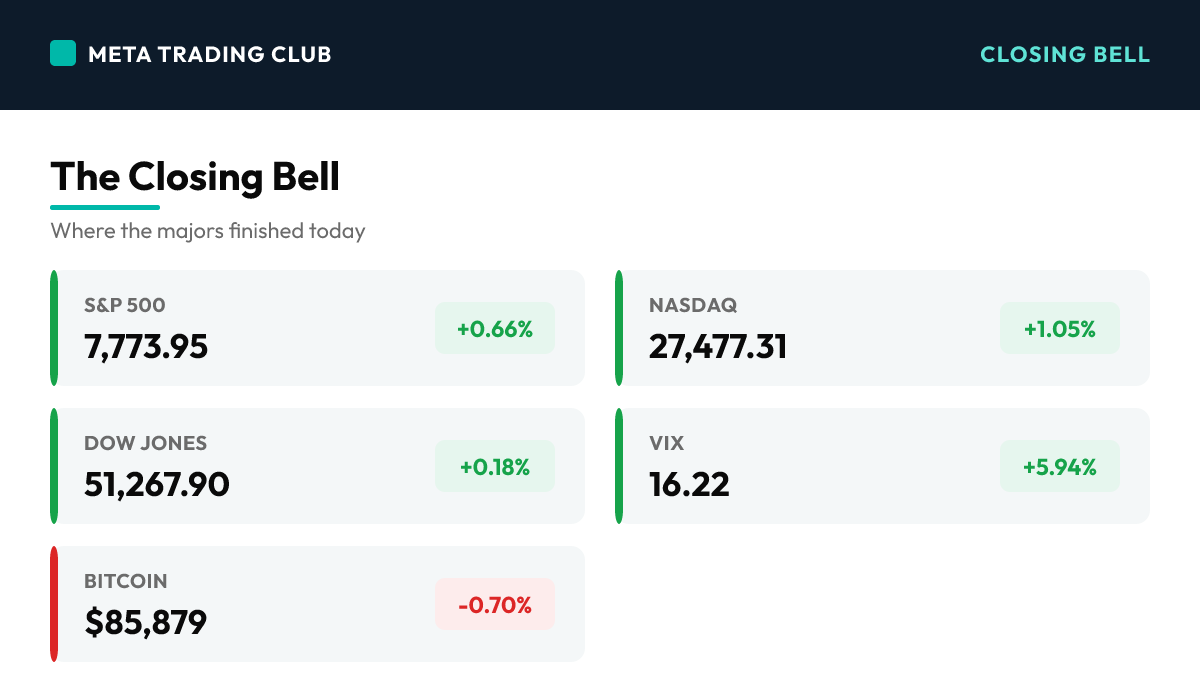
The story of the stock market today was a fresh Nasdaq record close on Monday, but you had to look away from most of the market to enjoy it. The Nasdaq Composite rose 1.05% to a record 27,477.31, led by Nvidia hitting an all-time high, while the S&P 500 added 0.66% to 7,773.95 and the Dow crept up just 0.18% to 51,267.90. The split in those three numbers is the whole story: this was a mega-cap, AI-led tape where only about half of Nasdaq names actually rose and the S&P still sits roughly 40 points below its August record at 7,816.70. Under the surface, two gauges leaned the other way. The 10-year Treasury yield held near 5.26%, a hair off multi-decade highs, and the VIX actually rose almost 6% to 16.22 on a green day, a quiet tell that the move was narrow rather than broad. Memory and storage names got hit even as AI chips flew, with Western Digital and Seagate both down about 10% while Nvidia and Broadcom gained over 2%. That leaves the S&P pinned between support at 7,750 and the August record at 7,816, and hands Tuesday a clean read: hold 7,750 and the breakout attempt stays alive, lose it and today looks like a thin, mega-cap-only pop. The economic calendar is light, so the tape, not a headline, decides the next move.
The Closing Bell
| Instrument | Close | Change | Note |
|---|---|---|---|
| S&P 500 | 7,773.95 | +0.66% | Added about 51 points to close at 7,773.95, a solid green day that still left the index roughly 40 points shy of its August record high at 7,816.70. The gain was real but narrow, carried by a handful of mega-cap and AI names rather than the broad tape. That makes 7,750 the line that matters: hold it and the push toward the record stays alive, lose it and today reads as a thin, top-heavy pop. The index is squeezed between support at 7,750 and resistance at the 7,816 record, and Tuesday’s light calendar means price action, not a catalyst, picks the side. |
| Nasdaq | 27,477.31 | +1.05% | The record of the day, up about 286 points to an all-time closing high of 27,477.31, powered by Nvidia’s run to a new record and strength across the large-cap AI and software complex. The catch sits under the headline: breadth was thin, with only about half of Nasdaq names higher on the session. A record built on roughly 50% participation is a record led by the few, not the many, and that is exactly the kind of advance that needs confirmation before you trust it to extend. |
| Dow Jones | 51,267.90 | +0.18% | Lagged the pack, up just 91 points, or 0.18%, as the blue-chip index carries the least AI and semiconductor weight that drove today’s move. On a day the Nasdaq set a record, a near-flat Dow is the clearest sign of how narrow the leadership was. The money went to growth and chips, and the parts of the market without that exposure barely moved, a divergence worth respecting. |
| Russell 2000 | 2,847.14 | +0.50% | Small caps closed up about 0.50% to 2,847.14, participating in the green but trailing the mega-cap-led Nasdaq. With the 10-year yield still pinned near multi-decade highs, the most rate-sensitive corner of the market had a ceiling over it. A modest gain is a fair read: small caps were along for the ride but not leading it, which fits a session defined by large-cap AI strength rather than broad risk appetite. |
| VIX | 16.22 | +5.94% | The quiet contradiction of the day. The volatility gauge rose almost 6% to 16.22 even as the Nasdaq set a record and the S&P closed green. A rising VIX on an up day is unusual and it tells you the move was narrow and hedged, not a confident, broad-based risk-on surge. When fear ticks up on a green close, the market is signaling it does not fully trust the rally, and that non-confirmation is a reason to stay patient rather than chase. |
| 10-Year Yield | 5.26% | ~flat | Held near 5.26%, a hair off multi-decade highs, and that is the heavy ceiling over this tape. Stocks managed a record on the Nasdaq despite yields this restrictive, which is impressive, but it also means the entire advance is running against a strong rate headwind. As long as the 10-year sits near 5.3%, the valuation math on the long-duration growth names stays stretched, and any further push higher in yields is the most direct threat to the AI-led leadership. |
| WTI Crude | $90.11 | -1.10% | Eased about a dollar to settle near $90.11, down 1.1%, as the energy complex gave back ground on softer supply-side positioning. A lower crude tape kept energy off the leaderboard on a day the action was all in chips and software. The pullback is modest and crude remains above $90, but on a session driven by growth, the commodity side simply did not participate. |
| Gold | $4,196.20 | +0.81% | Firmed about $34 to near $4,196 an ounce, up 0.81%, continuing to find a bid as a hedge even on a risk-on equity day. With yields pinned near multi-decade highs, gold holding firm shows steady demand for a store of value against the restrictive-rate backdrop. The metal quietly did its job as insurance while the headlines went to the AI trade. Level approximate into the settle. |
| Bitcoin | $85,879 | -0.70% | Slipped about 0.7% to near $85,879, a mild pullback that put crypto on the opposite side of the equity tape. On a day stocks pushed to records, Bitcoin easing lower is a small divergence, a reminder that the risk appetite was concentrated in large-cap AI equities rather than spread across the full risk complex. Level approximate into the settle. |
Today’s Charts
Daily candlestick charts with 20/50/200-day moving averages — the index majors, the day’s biggest mover on each side, and the leading sector ETF.

Charts: Finviz (daily). Levels and overlays update through the next session.
Sector Scoreboard
What Drove The Day
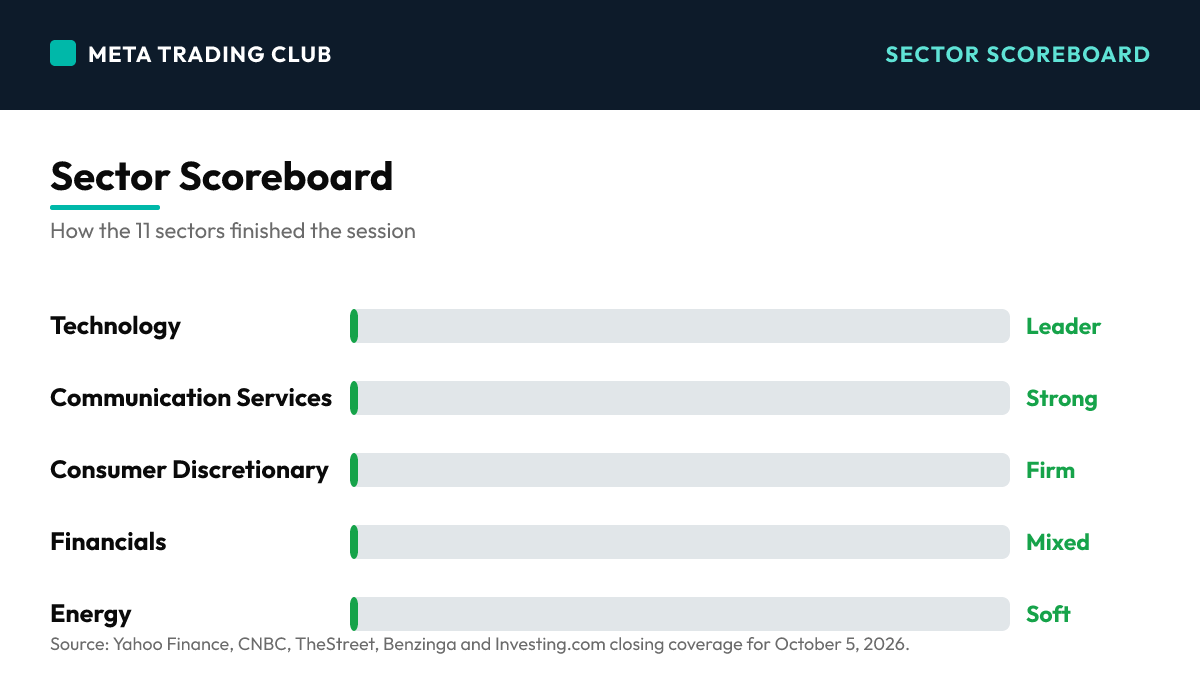
This was a record that most of the market did not attend. The Nasdaq closed at an all-time high of 27,477.31 and Nvidia printed a fresh record, but the strength was concentrated in large-cap AI and software, not spread across the tape. The order of the board told the story: the Nasdaq led at 1.05%, the S&P managed 0.66% and still finished about 40 points below its own August record, and the Dow crawled up just 0.18%. Beneath that, roughly half of Nasdaq names actually fell, memory and storage stocks like Western Digital and Seagate dropped about 10% even as Nvidia and Broadcom gained more than 2%, and the VIX rose almost 6% on a green day. Add a 10-year yield pinned near 5.26% and you have a textbook narrow advance: real at the index level, unconfirmed under the surface. The S&P closed squeezed between support at 7,750 and the 7,816 August record, which turns a thin green day into a clean binary for Tuesday rather than a trend you chase into the open.
MAJOR HEADLINES AND CATALYSTS
Top Market-Moving Stories
- NASDAQ AND NVIDIA PRINT RECORDS (Day) – The Nasdaq Composite closed at an all-time high of 27,477.31, up 1.05%, led by Nvidia hitting a fresh record of its own and over 2% gains in the semiconductor complex. The AI trade was firmly back in control of the leadership. The catch is that the record came on thin breadth, with only about half of Nasdaq names higher, a sign the advance was carried by the biggest stocks rather than the full market.
- THE S&P RECORD STAYS JUST OUT OF REACH (Day) – The S&P 500 rose 0.66% to 7,773.95 but still finished roughly 40 points below its August record high at 7,816.70. On the same day the Nasdaq set a record, the broad index could not, and the Dow managed just 0.18%. That divergence between the three majors is the clearest read on how narrow and top-heavy today’s strength really was.
- VIX RISES ON A GREEN DAY (Day) – The volatility index climbed almost 6% to 16.22 even as stocks closed higher, an unusual pairing that signals the market is hedged and cautious under the surface. A fear gauge ticking up on a record-setting Nasdaq day is a non-confirmation: the rally is real at the index level but the internals are not fully on board. It is a reason to respect the move without chasing it.
- MEMORY SELLS OFF WHILE AI CHIPS FLY (Day) – The split inside technology was stark. Western Digital and Seagate both fell about 10% and Micron slipped, while Nvidia and Broadcom gained more than 2%. The money concentrated in the AI and compute winners and left the storage and memory names behind, a reminder that a record on the chip ETF does not mean every chip stock is working.
AFTER-HOURS EARNINGS SPOTLIGHT
A Light Post-Close Slate
- NO MAJOR S&P NAMES AFTER THE BELL (AH) – Monday’s post-close earnings slate was light, with no index-moving S&P 500 reports hitting the tape after 4:05 PM ET. That leaves the day’s narrow, AI-led advance as the full story and keeps attention on the technical setup rather than a fresh earnings catalyst into Tuesday.
- THE CALENDAR PICKS UP TUESDAY (AH) – The next earnings of note arrive Tuesday with Constellation Brands and RPM International, alongside the August trade balance at 8:30 AM ET. None are likely to override the tape on their own, which keeps the focus on whether the S&P can hold 7,750 and press back toward its August record, or whether the thin breadth finally matters.
WHAT IT SETS UP FOR TUESDAY
The Tape Decides, Not a Headline
- 7,750 IS THE LINE THAT MATTERS (AH) – The S&P closed at 7,773.95, parked just above support at 7,750 and below the 7,816 August record. With a light economic calendar, there is no single data print to force the move, which means price action owns the open. Hold 7,750 and the push toward the record stays alive. Lose it and today’s narrow, mega-cap-led pop starts to look like a top-heavy stall.
- WATCH IF BREADTH CONFIRMS OR CRACKS (AH) – The single most important tell into Tuesday is whether participation broadens. A record Nasdaq on roughly 50% breadth needs the rest of the market to join for the move to be durable. If more names start rising with the mega-caps, the rally earns trust. If the VIX keeps climbing and breadth stays thin, the non-confirmation becomes the story and 7,750 gets tested.
Winners & Losers
Winners
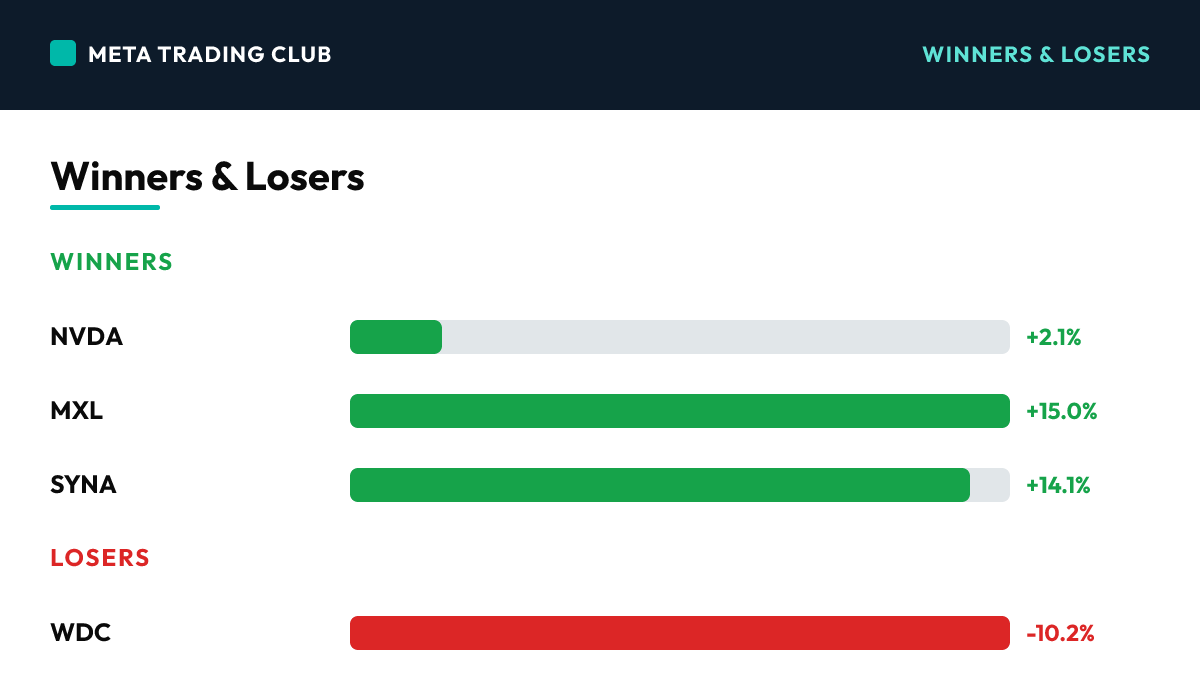
| NVDA | +2.1% | Nvidia was the engine of the record, rising about 2.1% to a fresh all-time high and dragging the Nasdaq to its own record close. The AI chip leader reclaimed the top of the tape for the first time in months, and its strength, alongside a comparable gain in Broadcom, was the single biggest reason the index finished green. When Nvidia leads, the AI trade leads, and today that was enough to set a record even with the broader market lagging. | |
| MXL | +15.0% | MaxLinear was the day’s biggest percentage gainer, surging about 15% as the semiconductor complex caught a strong bid. The move sat alongside double-digit gains in other chip names and underscored where conviction concentrated on the session. A 15% single-day move in a smaller chip name is the kind of momentum that appears when money crowds aggressively into one theme, in this case AI and semiconductors. | |
| SYNA | +14.1% | Synaptics jumped about 14.1%, another standout in a semiconductor group that led the market. The gain fit the day’s single clear theme, with chip names dominating the leaderboard while the rest of the tape lagged. Strength this broad across individual semis, even as breadth overall stayed thin, shows just how concentrated the risk appetite was in the AI and compute corner. |
Losers
| WDC | -10.2% | Western Digital fell about 10.2%, one of the sharpest declines on the day and a clear sign that not every chip name shared in the rally. The storage and memory complex sold off hard even as AI compute names set records, the cleanest example of how narrow and selective today’s technology strength really was. When one corner of chips drops 10% while another prints all-time highs, the sector is splitting, not surging as one. | |
| STX | -10.2% | Seagate dropped about 10.2% alongside Western Digital, confirming the memory and storage group as the day’s clear loser inside technology. The pair falling in lockstep while AI chips flew is the divergence of the session: the money chased compute and left storage behind. It is a reminder that a record on the chip ETF can mask double-digit losses in the names that are out of favor. | |
| INTC | -2.6% | Intel slipped about 2.6%, lagging the broader semiconductor strength and underscoring the split between the AI winners and the rest of the chip space. On a day Nvidia set a record, Intel fading is the same story told a different way: leadership was tightly concentrated in the AI and compute names, and the legacy and memory corners of the sector could not keep up. Move reflects the regular session. |
What It Sets Up For Tomorrow
Levels Into Tomorrow
- S&P 500 7,750 – THE LINE THAT DECIDES IT. Price closed at 7,773.95, sitting just above the 7,750 shelf after a narrow, AI-led green day. This is the single most important level on the page. Hold 7,750 and today’s push stays alive with a clear path back toward the August record at 7,816. Lose it, especially if breadth stays thin and the VIX keeps rising, and the market is telling you the record on the Nasdaq was a mega-cap mirage. The first clean move relative to 7,750 at Tuesday’s open tells you whether the breakout attempt is real.
- S&P 500 7,816 – THE RECORD TO RECLAIM. The August all-time high and the ceiling this tape has to clear to prove the advance is more than a few names. A decisive close above 7,816 on broadening breadth would confirm the AI leadership is pulling the whole market with it. Until that happens, the index is making lower progress than the Nasdaq, and the record on the chip complex is not yet a record on the broad tape.
- S&P 500 7,700 – THE SHELF BELOW. The next real support if 7,750 gives way. A loss of 7,700 would confirm that today’s narrow strength could not hold and that the thin breadth and rising VIX were the honest signals. This is where a top-heavy pop turns into a genuine pullback, and where the most rate-sensitive and lower-quality names would likely lead the move lower.
Bull case: The AI trade is back in command and it is powerful. The Nasdaq set a record, Nvidia printed an all-time high, and the semiconductor complex gained more than 2%, proof that the market still wants to pay up for compute and AI leadership. If participation broadens on Tuesday, with more names joining the mega-caps, the S&P holds 7,750 and presses toward its August record at 7,816. A light calendar removes headline risk and lets the trend run. In this read, today’s narrow leadership is simply the first leg, and the broad market catches up to the chip complex rather than the other way around.
Bear case: A record on roughly half the market is a record on borrowed time. The Nasdaq made a new high while the S&P stalled below its own record, the Dow barely moved, the VIX rose almost 6%, and the 10-year yield sat near multi-decade highs. That is non-confirmation stacked four deep. Memory and storage names falling 10% while AI chips fly shows the strength is concentrated, not broad. If breadth does not improve, the S&P loses 7,750, and the thin, mega-cap-only nature of today’s advance becomes the story, opening a move back toward 7,700 with the rising volatility gauge finally mattering.
Risks Into Tomorrow
- A record on half the market is a record that needs confirmation — The Nasdaq set an all-time high today, but only about half of its names actually rose. That single fact reframes the whole session. An index can print a record on the strength of a handful of mega-caps while most of the stocks inside it go nowhere or fall, and that is exactly what happened. The lesson is to look past the headline number to the participation behind it. Breadth is the market voting with its feet, and when a record comes on roughly 50% participation, the vote is split. That does not make the move fake, but it does make it fragile, because a rally led by a few names depends entirely on those names continuing to lead. The discipline is to treat a thin record as a reason to demand confirmation before you trust it, not as a green light to chase. If participation broadens tomorrow, the move earns its stripes. If it does not, the narrow leadership becomes the risk. No alignment between the index and its internals means you wait for the breadth to catch up, or you respect that the level, 7,750, will settle it.
- When the fear gauge rises on a green day, listen to it — The VIX climbed almost 6% today while the Nasdaq set a record and the S&P closed green. That pairing is unusual and it is informative. Normally volatility falls as stocks rise, because calm and gains go together. When the VIX rises on an up day, it means traders are paying up for protection even as prices climb, a sign the smart money is hedging the very rally it is participating in. This is a non-confirmation, one of several today, and non-confirmations are where discipline earns its keep. The mistake is to see green on the screen and assume the all-clear. The better read is to notice what the volatility market is doing underneath and ask why fear would rise into strength. The answer, today, is that the move is narrow, the breadth is thin, and the participants know it. The plan is to let that caution inform your sizing. A record built on rising fear and falling breadth is not one you lean into with full risk. You wait for the internals to confirm, or you let the key level do the deciding.
- Respect the rate ceiling even when stocks ignore it — The 10-year Treasury yield sat near 5.26% today, a hair off multi-decade highs, and stocks set a record on the Nasdaq anyway. That is impressive, but it is also a setup worth watching with caution rather than celebration. A yield this restrictive puts a heavy valuation ceiling over the long-duration growth and AI names that led today, and the entire advance is running directly against that headwind. The lesson is that just because the market is ignoring a risk today does not mean the risk is gone. Rates near multi-decade highs are the single most direct threat to the AI leadership trade, and any further push higher in the 10-year is the most likely trigger for that leadership to crack. The discipline is to keep the macro backdrop in view even on the strong days. When the move depends on a handful of expensive names and those names are fighting a 5.3% yield, the margin for error is thin. You stay alert to the bond market as the place a surprise is most likely to come from, and you let your risk reflect that the tailwind here is price momentum, not the fundamentals of the rate environment. No alignment until yields give the growth trade room to breathe.
Frequently Asked Questions
How did the S&P 500 close today?
On Monday, October 5, 2026, the S&P 500 closed at 7,773.95 (+0.66%), with the VIX at 16.22. The story of the stock market today was a fresh Nasdaq record close on Monday, but you had to look away from most of the market to enjoy it.
What drove the market today?
NASDAQ AND NVIDIA PRINT RECORDS (Day) – The Nasdaq Composite closed at an all-time high of 27,477.31, up 1.05%, led by Nvidia hitting a fresh record of its own and over 2% gains in the semiconductor complex. The AI trade was firmly back in control of the leadership. The catch is that the record came on thin breadth, with only about half of Nasdaq names higher, a sign the advance was carried by the biggest stocks rather than the full market.
What levels matter for tomorrow?
S&P 500 7,750 – THE LINE THAT DECIDES IT. Price closed at 7,773.95, sitting just above the 7,750 shelf after a narrow, AI-led green day. This is the single most important level on the page. Hold 7,750 and today’s push stays alive with a clear path back toward the August record at 7,816. Lose it, especially if breadth stays thin and the VIX keeps rising, and the market is telling you the record on the Nasdaq was a mega-cap mirage. The first clean move relative to 7,750 at Tuesday’s open tells you whether the breakout attempt is real. S&P 500 7,816 – THE RECORD TO RECLAIM. The August all-time high and the ceiling this tape has to clear to prove the advance is more than a few names. A decisive close above 7,816 on broadening breadth would confirm the AI leadership is pulling the whole market with it. Until that happens, the index is making lower progress than the Nasdaq, and the record on the chip complex is not yet a record on the broad tape. S&P 500 7,700 – THE SHELF BELOW. The next real support if 7,750 gives way. A loss of 7,700 would confirm that today’s narrow strength could not hold and that the thin breadth and rising VIX were the honest signals. This is where a top-heavy pop turns into a genuine pullback, and where the most rate-sensitive and lower-quality names would likely lead the move lower.
How does Meta Trading Club prepare for the next session?
We wrap every session and carry the read forward through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
New to this? Start with the free training.
Learn how we read the market before you risk a dollar — our free education library and ebook break down the fundamentals step by step.
Free education → Get the free ebookThe session’s over. The prep isn’t.
This is how MTC members close each day — wrap what happened, mark the levels, and carry one clean read into tomorrow. If you want to build that habit and qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process. It’s application-based — see if it’s a fit.
Explore the MTC Incubator → Apply nowSources: Yahoo Finance, CNBC, TheStreet, Benzinga and Investing.com closing coverage for October 5, 2026.. For educational purposes only. Not financial advice.