Monday, October 5, 2026 · 8:45 AM ET · MTC Market Intelligence
The stock market today walks in carrying a contradiction it can’t keep ignoring. The S&P 500 sits less than 1% from a record high after Friday’s rally — the Dow added 250 points to 51,176.96, the S&P 500 gained 0.7% to 7,722.72, and the Nasdaq Composite jumped 1.2% to 27,190.86 as a weak September jobs print (+29,000) pared back the odds of another Fed hike. But the 10-year Treasury yield is at 5.28%, its highest level since 2002, and Brent crude is holding above $100 after Iran said the Strait of Hormuz won’t fully reopen until Washington meets seven conditions. Two forces pulling opposite directions: a dovish Fed story lifting stocks, and a bond market and oil shock that should be dragging them down. This morning the second force has a small edge — Dow futures are down about 0.15%, S&P 500 futures off 0.17%, and Nasdaq-100 futures down 0.24%, pointing to a slightly lower open. The calendar is quiet: ISM Services at 10:00 AM ET is the only real data, and the prices-paid component is the one to watch after Thursday’s manufacturing survey ran hot at 77.9. No major earnings today. So this is a reaction day, not a prediction day. The question isn’t whether the market ‘should’ pull back with yields at 24-year highs — strategists have said that for weeks and it hasn’t. The question is whether price can finally break to a new high against that pressure, or whether the bond market wins. SPX 7,780 is the record-high wall, 7,722 is Friday’s close and the axis, and 7,666 is the shelf that keeps a pullback orderly. Don’t fight the tape and don’t chase it. Let price pick the side. No alignment, no trade.
Market Snapshot
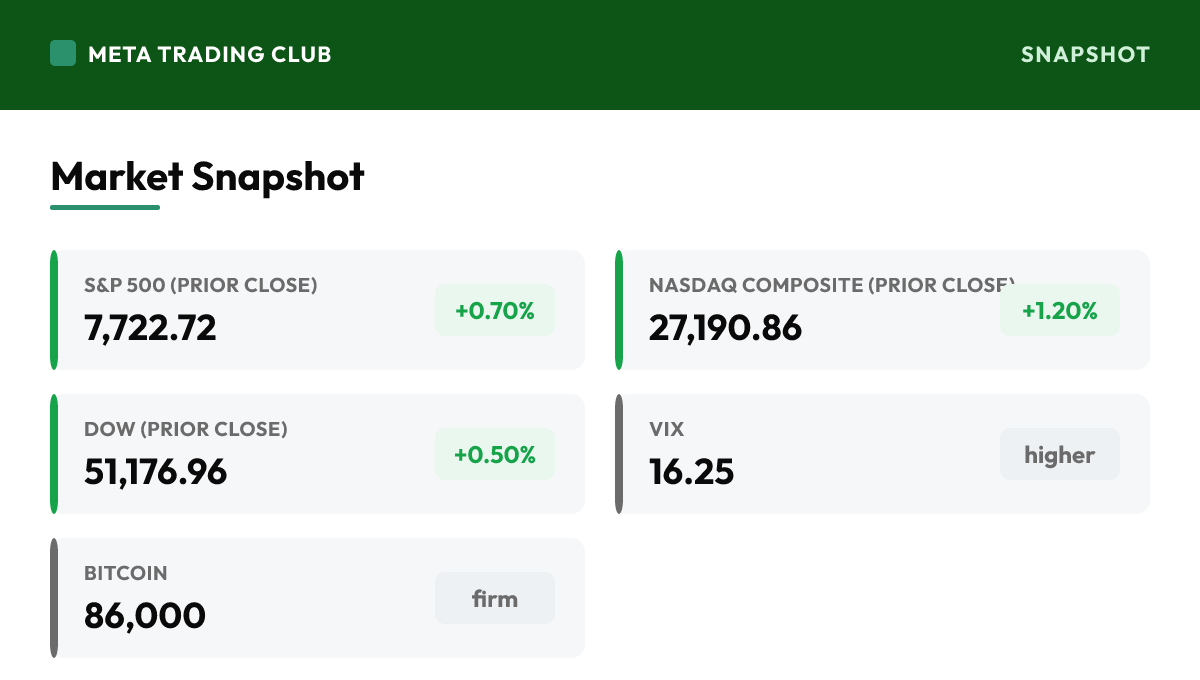
| Instrument | Level | Change | Note |
|---|---|---|---|
| S&P 500 (prior close) | 7,722.72 | +0.70% | Closed Friday at 7,722.72, up 0.7%, as a weak September jobs report lowered the odds of another Fed hike and sent buyers back into stocks. That close leaves the index less than 1% from a record high — a remarkable place to be with the 10-year at 5.28%. This morning S&P 500 futures are down about 0.17%, pointing to a slightly lower open. The axis is 7,722: hold above it and the record-high test stays alive; fade back through it and the rising-yield pressure is starting to bite. Watch the reaction at the level, not the premarket tick. |
| Nasdaq Composite (prior close) | 27,190.86 | +1.20% | Finished Friday at 27,190.86, up 1.2% and adding over 300 points as megacap tech led the jobs-driven rally back toward all-time highs. This morning Nasdaq-100 futures are the weakest major, down about 0.24% — the highest-duration corner of the market is the first to feel a 10-year yield pinned at 24-year highs. That’s the tension in tech right now: it leads when rate-cut hope is the story and gives back first when the bond market reasserts itself. Lead or lag off the open tells you which story is winning today. |
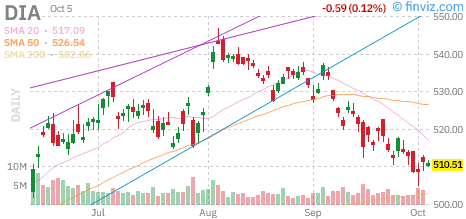
| Dow (prior close) | 51,176.96 | +0.50% | Closed Friday at 51,176.96, up 0.5% or 250 points, as the blue chips joined the broad rally on the softer jobs read. This morning Dow futures are down about 0.15%, a quiet pullback rather than a real reversal. The value-heavy, rate-sensitive index is the one most exposed to a 10-year at 5.28%, so watch whether the Dow can hold near Friday’s gains or whether rising yields start pulling it lower. Broad participation across the Dow, Nasdaq and small caps keeps the record-high story credible; a narrow, tech-only tape is the first warning sign. |
| S&P 500 Futures | — | -0.17% | Down about 0.17% this morning, pointing to a modestly lower open after Friday’s push toward record territory. It’s a drift, not a drop — the market isn’t rejecting the highs, it’s hesitating in front of them with yields and oil both elevated. Don’t over-read a small red premarket. The signal today is how cash trades the 7,722 axis after the open: hold and build above it and the record-high test is live; lose it and fail to reclaim and the rising-yield worry is finally showing up in price. |
| Nasdaq-100 Futures | — | -0.24% | Down about 0.24%, the weakest of the majors as the longest-duration growth names feel the 10-year at a 24-year high most directly. High-multiple tech is the leadership when the rate-cut story runs and the first to wobble when the bond market tightens the screws. Watch the Nasdaq as the cleanest tell on which force is winning: if it reclaims green and leads off the open, the dovish read still owns the tape; if it keeps leaking while yields climb, the rate pressure is the real driver today. |
| Russell 2000 Futures | — | -0.11% | Down about 0.11%, nearly flat and the most resilient of the major futures this morning. Small caps are the most rate-sensitive group there is, so a Russell holding steady while the 10-year sits at 5.28% is a quiet sign that the market isn’t yet pricing a yield-driven breakdown. Use the Russell as a breadth tell: if small caps can hold and join a push to new highs, participation is broad and the move is healthier; if they roll over with yields, the rally is narrowing and leaning entirely on megacap tech. |
| VIX | 16.25 | higher | Ticking up about 6% toward 16.25 this morning, a small rise off a low base as the options market prices a touch more caution into a tape sitting near records with yields at 24-year highs. It’s still a calm absolute reading — nothing close to fear — but the uptick says traders are paying a little more for protection as the market tests the highs against real macro pressure. Treat it as a tell, not an alarm: a VIX that keeps climbing while stocks stall is the market quietly bracing; one that fades back down says the dip-buyers are still in control. |
| WTI Crude | 90.50 | lower | Easing about 0.7% toward $90.50 this morning, a small pullback that doesn’t change the bigger picture: Brent is still holding above $100 after Iran said the Strait of Hormuz won’t fully reopen until the U.S. meets seven conditions. Elevated oil is one half of the pressure sitting on this tape — it feeds the inflation worry that keeps the 10-year high. Track crude as a macro swing factor: a sustained move back toward and above $100 keeps upward pressure on yields and the inflation story, while a real roll-over would take some heat off the bond market and help stocks. |
| 10-Yr Yield | 5.28% | higher | At 5.28% this morning, up slightly and sitting at its highest level since 2002. This is the single most important number on the screen today. A 24-year-high yield is the force that should be pulling a near-record stock market lower, and the fact that stocks have held anyway is the whole story of this tape. Mohamed El-Erian warned this weekend about the ‘structural repricing’ in bonds spilling into credit and spread risk. Watch the 10-year more closely than any stock: keep climbing and it eventually caps the rally; back off and it hands stocks room to test new highs. |
| Bitcoin | 86,000 | firm | Firm near $86,000, up roughly 1% over the last 24 hours as the highest-beta risk asset holds its ground alongside a near-record stock market. Crypto steady while yields sit at 24-year highs is a modest risk-on tell — the speculative end of the curve isn’t flinching yet. Treat Bitcoin as a sentiment gauge today: if it holds and firms alongside equities, risk appetite is intact and the dovish read has support; if it rolls over intraday, it’s often the first place a broader risk-off shows up before it reaches the index. |
Charts to Watch
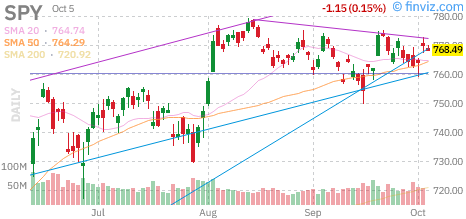
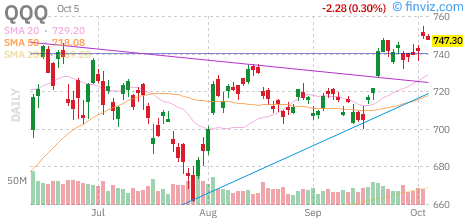
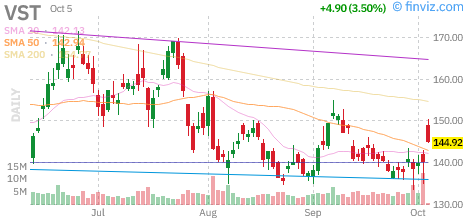
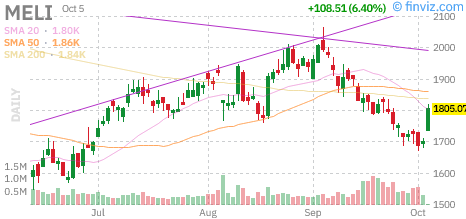
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
Overnight & Global Markets
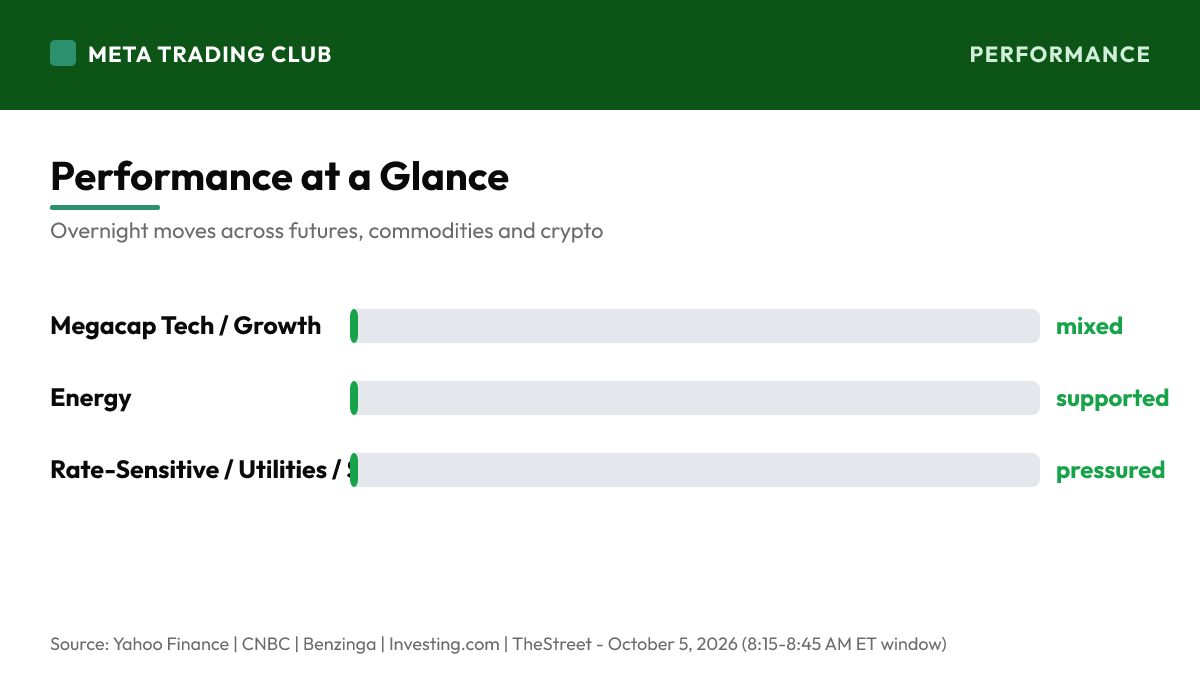
Friday closed strong and broad — the Dow rose 0.5% to 51,176.96, the S&P 500 added 0.7% to 7,722.72, and the Nasdaq Composite jumped 1.2% to 27,190.86 — as a soft September jobs report (+29,000 payrolls) pared back the odds of another Fed rate hike and pulled buyers back toward record highs. That rally left the S&P less than 1% from an all-time high. The problem is what it’s sitting on top of: the 10-year Treasury yield is at 5.28%, its highest since 2002, and Brent crude is holding above $100 after Iran said the Strait of Hormuz won’t fully reopen until Washington meets seven conditions. Two forces pulling opposite ways — a dovish Fed story lifting stocks, a bond-and-oil shock that should be dragging them down. This morning the macro side has a slight edge: Dow futures are down about 0.15%, S&P 500 futures off 0.17%, and Nasdaq-100 futures down 0.24%, pointing to a modestly lower open. The calendar is quiet — ISM Services at 10:00 AM ET is the only real data, with the prices-paid component the key tell after Thursday’s manufacturing survey ran hot at 77.9 — and there are no major earnings today. That puts the weight entirely on the reaction. For weeks the market has had every reason to sell off and hasn’t; the path of least resistance has been higher. Today tests whether that holds against yields at a 24-year high. Mark 7,780 as the record-high wall, 7,722 as Friday’s close and the axis, and 7,666 as the shelf. Don’t fight the tape and don’t chase it — let price pick the side.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The whole tape runs through one contradiction: the S&P 500 sits less than 1% from a record high while the 10-year Treasury yield is at 5.28%, its highest level since 2002. Friday’s rally came off a weak September jobs report (+29,000 payrolls) that cut the odds of another Fed hike — CME FedWatch now shows roughly a 20.5% chance of an October hike, down sharply. That dovish read is what’s kept stocks bid. But a 24-year-high yield is exactly the kind of pressure that historically pulls a near-record market lower, and this morning futures are slipping: Dow -0.15%, S&P 500 -0.17%, Nasdaq-100 -0.24%. The market is hesitating in front of the highs, not rejecting them.
- Geopolitics is the second force on the tape. Iran said the Strait of Hormuz will not fully reopen until Washington meets seven conditions, holding a firm line despite mediated proposals, and Brent crude is holding above $100 per barrel. Tehran also warned of a stronger military response to any U.S. strikes amid reports of additional American troop deployments. Elevated oil feeds straight into the inflation-and-yield loop that’s keeping the 10-year high, so the Hormuz story and the bond market are really the same risk wearing two hats. Watch crude and the 10-year together — they’re the macro engine under today’s session.
- The calendar is quiet, which puts all the weight on the reaction. ISM Services for September lands at 10:00 AM ET (expected around 55.1 versus 55.4 prior), with the S&P Global services PMI final at 9:45 AM. The number to watch is prices paid: Thursday’s manufacturing survey ran hot at 77.9 against the 72.3 expected, so a hot services prices-paid print would reinforce the inflation worry and the higher-for-longer yield story. There are no major earnings today. With little to break the move, today is about how price digests the record-high test against 24-year-high yields — not about a fresh catalyst.
Stock-Specific
- Vistra (VST) is the standout mover, up more than 6% premarket after a Bloomberg report that the Trump administration plans to offer the company a roughly $4 billion loan package to upgrade three of its nuclear plants. It’s a clean, catalyst-driven move on a real policy tailwind for nuclear power — trade it on its own levels, since a 6% gap can both extend on momentum and fade once the headline is priced. On a day defined by the macro tug-of-war, this is a self-contained single-name story worth isolating from the broad-tape read.
- Qualcomm (QCOM) is higher by roughly 1.8% premarket after filing a prospectus to offer 25 million common shares — notable because a share offering is typically dilutive, so a stock trading up on one says the market likes the use of capital or had already braced for it. MercadoLibre (MELI) is up about 6% alongside other Brazil-exposed names after first-round results in Brazil’s presidential election. Both are clean single-name catalysts with their own drivers — trade them on their own levels, not as reads on the broad tape.
- Space Exploration Technologies (SPCX) is up about 1% after completing three launches in under 13 hours, sending astronauts, a classified U.S. intelligence payload, and Google’s first in-orbit AI experiment into space. Applied Digital (APLD) is firm after announcing a second phase of its Polaris Forge 1 campus reached Ready for Service, adding 75 MW of capacity, with its own earnings due later this week. These are self-contained momentum stories — isolate them on their own levels rather than treating them as signals on market direction.
Global and Macro
- The bond market is the macro story everything else bends around. The 10-year at 5.28% — a 24-year high — is the force that should be capping a near-record stock market, and the fact that it hasn’t yet is what makes this tape unusual. Mohamed El-Erian warned this weekend that fixed-income volatility is being driven by a ‘long-term structural repricing’ from heavy supply and weaker traditional demand, and that interest-rate risk is starting to spill into credit and spread risk as high-yield spreads widen. The belief that surging risk-free rates can stay isolated, he said, is ‘now visibly under pressure.’ Watch the 10-year as the real driver of every risk asset today.
- There’s a seasonality and resilience backdrop worth holding in mind. October has a scary reputation but a solid record — an average return near 1.9% and a 63% win rate over the past 30 years. And the market has, in the words of one strategist, ‘had every reason to sell off and it hasn’t,’ with the path of least resistance appearing higher. That doesn’t cancel the risk from yields and oil; it frames it. The lesson for today is not to assume the pullback everyone’s been calling for is finally here just because futures are red — let price confirm it before you trade it.
TECHNICAL ANALYSIS
S&P 500 Key Levels
- The S&P closed Friday at 7,722.72, less than 1% from a record high, and futures point to a modestly lower open. The level that matters on the upside is 7,780 — the record-high wall. A push through and hold above it on real trade, with breadth from the Dow and small caps rather than tech alone, is the market saying it can break to new highs even against a 24-year-high yield. That’s a powerful signal if it comes. But don’t anticipate it: let cash reclaim and hold the level before you trust the breakout, because a near-record tape stalling in front of resistance with yields climbing is exactly where failed breakouts happen.
- First support is 7,722 — Friday’s close and the axis the whole session pivots on. Hold above it and the record-high test stays alive. Below that, 7,666 is the shelf that keeps a pullback orderly — roughly Thursday’s prior level and the first real floor. Lose 7,666 and fail to reclaim it and the rising-yield pressure is finally showing up in price, opening the tape toward the next leg lower. Mark 7,780 above and 7,666 below: inside that range is the market deciding; outside it is the real signal. Trade the edges, not the middle.
Sector and Sentiment
- The leadership read this morning is the key tell. Nasdaq-100 futures are the weakest major and the Russell is the most resilient — an unusual split that says the market is quietly rotating out of the highest-duration tech and into groups less exposed to the yield. For a push to new highs to be credible, you want breadth: the Dow, small caps and cyclicals participating, not just megacap tech carrying the tape. If tech leads back green off the open and drags everything up, the dovish read is still in control; if the rally narrows to a handful of names while yields climb, that’s the first sign the move is running out of fuel.
- The VIX ticking up toward 16.25 says the options market is pricing a little more caution into a tape sitting near records against real macro pressure — but it’s still a low, calm reading, not fear. That combination, low volatility over a 24-year-high yield and a $100 oil price, is the definition of conditional calm: comfortable until it isn’t. Practically, respect that the quiet can break fast if ISM services runs hot or the 10-year pushes higher, keep the yield on your screen as the real driver, and let SPX prove its levels on the reaction before you commit to either side.
TODAY’S ECONOMIC CALENDAR
Key Releases (ET)
- It’s a light data day with one real event: ISM Services for September at 10:00 AM ET, expected around 55.1 versus 55.4 prior, preceded by the S&P Global services PMI final at 9:45 AM. The component to watch is prices paid. Thursday’s ISM manufacturing survey showed prices paid at 77.9 against the 72.3 expected — a hot inflation signal — so if the services prices-paid number also runs hot, it reinforces the higher-for-longer yield story that’s pressuring the tape. A softer services read, by contrast, would support the case that the Fed can pause in October and take some heat off the 10-year.
- Beyond today, the week builds slowly: the September FOMC meeting minutes land Wednesday at 2:00 PM ET, weekly jobless claims Thursday, and University of Michigan consumer sentiment Friday, with a steady stream of Fed speakers — Logan, Musalem and Schmid among them — through the week. Earnings pick up with Levi Strauss, Applied Digital, PepsiCo and Delta Air Lines before Q3 season kicks off in earnest in mid-October. For today, with no major catalyst to rescue or break the move, trade the ISM reaction and the levels — and let the week’s bigger events come to you rather than front-running them.
Earnings Today
- There are no notable earnings on today’s calendar, so the single-stock story is about the premarket movers rather than fresh prints. Vistra’s 6% jump on a reported federal nuclear loan is the standout, with Qualcomm up on its share-offering filing and MercadoLibre higher on Brazil election results. With no heavyweight earnings to swing the tape, the macro tug-of-war between a dovish Fed and a 24-year-high yield owns the session, and the single names are texture — isolate them on their own levels rather than treating them as reads on market direction.
- Look ahead, not just at today. This week brings Levi Strauss (LEVI), Applied Digital (APLD), PepsiCo (PEP) and Delta Air Lines (DAL) — a cross-section of the consumer, travel and AI-infrastructure economy — before the heart of Q3 season arrives mid-October. Those prints will be the first real test of whether high yields and elevated oil are starting to bite corporate results. For today, trade the ISM reaction and the SPX levels; use the week-ahead earnings and the Fed minutes as the reasons to keep risk measured rather than overcommitting early.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,780 — the record-high wall. The level just above Friday’s 7,722 close and the resistance the market has to clear to print a new high. A push through AND a hold above it on real trade, with breadth from the Dow and small caps rather than tech alone, is the tape saying it can break out even against a 24-year-high yield — a powerful signal, and the door opens higher if it holds. But don’t anticipate the breakout. Make price take and hold 7,780 after the open before you trust the long side; a near-record market stalling at resistance with yields climbing is exactly where failed breakouts live.
- SPX 7,722 — the axis. Friday’s close and the pivot the whole session turns on. Hold above it and the record-high test stays alive; this is the ‘let it prove itself’ zone where a market weighing a dovish Fed against rising yields tends to chop. The real signal is which side SPX leaves this level on once the open settles and ISM services lands at 10:00. Inside the range is noise; the move that follows is the trade. Patience beats forcing a position while the tape is still deciding which macro force it wants to trade.
- SPX 7,666 — the shelf that keeps a pullback orderly. The first real floor below the axis, roughly Thursday’s prior level. Hold it and a dip is just a dip inside an uptrend. Lose 7,666 and fail to reclaim it and the rising-yield pressure is finally showing up in price — the market is starting to trade the 5.28% 10-year as the thing that caps the rally, and the tape opens toward the next leg lower. Below 7,666 the job shifts to capital preservation. Mark it, and respect it if it goes.
Bull case: The market keeps doing what it’s done for weeks: shrugging off the macro pressure. ISM services comes in cool enough to ease the inflation worry, the 10-year backs off 5.28%, and SPX clears 7,780 to print a new high. Breadth broadens — the Dow, small caps and cyclicals join rather than megacap tech carrying it alone — and the dip-buyers stay in control. In this scenario the resilience that’s defined the tape wins again: the dovish-Fed read keeps its grip, the record falls, and the market proves once more that the path of least resistance is higher, even with yields at a 24-year high.
Bear case: The bond market finally wins. ISM services prices paid runs hot like Thursday’s manufacturing print, the 10-year pushes further above 5.28%, and the rate pressure everyone’s been warning about shows up in price at last. SPX fails at 7,780, fades back through 7,722, and loses 7,666 as megacap tech — the longest-duration, most rate-exposed group — leads lower. El-Erian’s warning about rate risk spilling into credit starts to look prescient, oil stays above $100 to keep the inflation worry alive, and the pullback strategists have called for weeks finally arrives. A failed record-high test on rising yields is a clean short setup.
Premarket Movers
Gainers
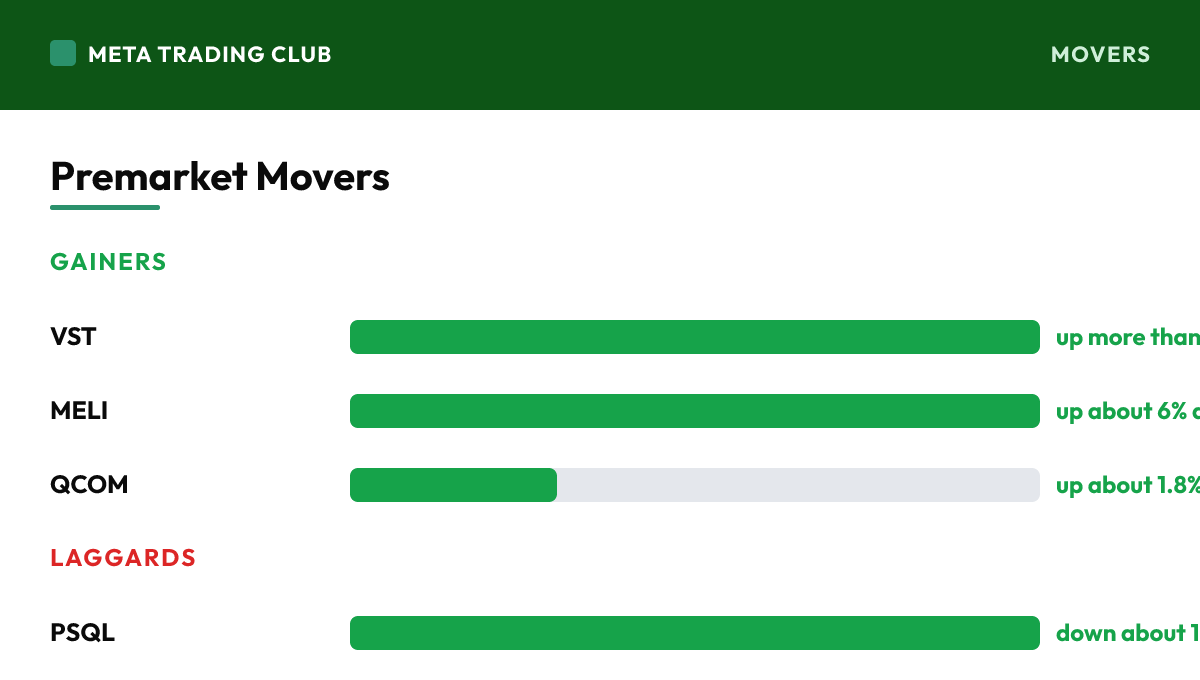
| VST | Vistra | up more than 6% on a reported ~$4B federal loan package for nuclear plant upgrades | Up over 6% premarket after a Bloomberg report that the Trump administration plans to offer the company a roughly $4 billion loan package to upgrade three of its nuclear plants. It’s a clean, policy-driven catalyst and a real tailwind for the nuclear-power story that’s been a theme in the AI-energy trade. Trade it on its own levels — a 6% gap can extend on momentum or fade once the headline is priced in. On a day owned by the macro tug-of-war, this is a self-contained single-name setup to isolate from the broad-tape read. |
| MELI | MercadoLibre | up about 6% alongside Brazil-exposed names after first-round presidential election results | Up roughly 6% premarket alongside other Brazil-exposed names after first-round results in Brazil’s presidential election. This is an event-driven, country-specific flow story rather than a company-fundamentals catalyst — political results reset the risk premium on Brazilian assets and the move reflects that repricing. Trade it on its own levels and understand the driver: election-reaction moves can be sharp and can reverse as the second round and policy details come into focus. A clean single-name story independent of the U.S. macro read. |
| QCOM | Qualcomm | up about 1.8% after filing a prospectus to offer 25 million common shares | Higher by roughly 1.8% premarket after filing a prospectus to offer 25 million common shares. That’s notable because a share offering is usually dilutive and pressures a stock — so one trading up on the news says the market either likes the intended use of the capital or had already priced the risk. Trade it on its own levels and respect the nuance: offerings can create overhang that caps a move even when the initial reaction is positive. A self-contained catalyst to isolate from the broad tape. |
Laggards
| PSQL | Pasqal Holding | down about 1.3% after naming a new head of investor relations | Down about 1.3% premarket after naming Roger L. Chuchen as head of investor relations — a minor, personnel-driven move rather than a fundamental catalyst. On a quiet Monday with no major earnings and a broadly flat-to-lower tape, there’s no marquee single-stock decliner driving the session; the real pressure is at the index level, where the longest-duration names feel the 24-year-high yield most. Trade PSQL on its own levels and keep the focus where it belongs today — on the 10-year and the SPX axis, not on a thin premarket move. |
Risks Into the Open
- Primary risk: assuming the long-awaited pullback has finally arrived just because futures are red. Strategists have called for a selloff for weeks on the back of 24-year-high yields, elevated oil and narrowing breadth — and the market has kept grinding higher. A modestly lower premarket near record highs is hesitation, not confirmation of a top. Fading the tape on a hunch has been a losing trade all autumn. Let SPX actually lose 7,666 and fail to reclaim it before you trade the downside; let it clear and hold 7,780 before you trust the breakout. The reaction at the level is the signal, not the premarket tick.
- The structural risk is the bond market, and it’s the one that matters most. The 10-year at 5.28% is a 24-year high, and El-Erian’s warning this weekend was specific: the ‘structural repricing’ in Treasuries is starting to spill into credit and spread risk, with high-yield spreads widening. The belief that surging risk-free rates can stay isolated from stocks is, in his words, ‘now visibly under pressure.’ If the ISM prices-paid number runs hot or the 10-year pushes higher, that’s the scenario where the rate pressure finally reaches equities. Keep the yield on your screen as the real driver of every risk asset today.
- The oil-and-geopolitics risk is the wild card. Brent is holding above $100 with the Strait of Hormuz standoff unresolved and Iran warning of a military response to any U.S. strikes. A fresh escalation or a push in crude back toward and above $100 would feed straight into the inflation worry and the yield story, compounding the pressure on stocks. It’s not today’s base case — WTI is easing slightly this morning — but it’s the headline risk that can reprice the tape in minutes. Keep crude on your screen alongside the 10-year, size appropriately, and don’t be caught long and complacent if the oil story turns.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Monday, October 5, 2026, S&P 500 futures are at 7,722.72 (+0.70%), with the VIX near 16.25. The stock market today walks in carrying a contradiction it can’t keep ignoring. The S&P 500 sits less than 1% from a record high after Friday’s rally — the Dow added 250 points to 51,176.96, the S&P 500 gained 0.7% to 7,722.72, and the Nasdaq Composite jumped 1.2% to 27,190.86 as a weak September jobs print (+29,000) pared back the odds of another Fed hike. But the 10-year Treasury yield is at 5.28%, its highest level since 2002, and Brent crude is holding above $100 after Iran said the Strait of Hormuz won’t fully reopen until Washington meets seven conditions. Two forces pulling opposite directions: a dovish Fed story lifting stocks, and a bond market and oil shock that should be dragging them down. This morning the second force has a small edge — Dow futures are down about 0.15%, S&P 500 futures off 0.17%, and Nasdaq-100 futures down 0.24%, pointing to a slightly lower open. The calendar is quiet: ISM Services at 10:00 AM ET is the only real data, and the prices-paid component is the one to watch after Thursday’s manufacturing survey ran hot at 77.9. No major earnings today. So this is a reaction day, not a prediction day. The question isn’t whether the market ‘should’ pull back with yields at 24-year highs — strategists have said that for weeks and it hasn’t. The question is whether price can finally break to a new high against that pressure, or whether the bond market wins. SPX 7,780 is the record-high wall, 7,722 is Friday’s close and the axis, and 7,666 is the shelf that keeps a pullback orderly. Don’t fight the tape and don’t chase it. Let price pick the side. No alignment, no trade.
What is the biggest catalyst for the market today?
The whole tape runs through one contradiction: the S&P 500 sits less than 1% from a record high while the 10-year Treasury yield is at 5.28%, its highest level since 2002. Friday’s rally came off a weak September jobs report (+29,000 payrolls) that cut the odds of another Fed hike — CME FedWatch now shows roughly a 20.5% chance of an October hike, down sharply. That dovish read is what’s kept stocks bid. But a 24-year-high yield is exactly the kind of pressure that historically pulls a near-record market lower, and this morning futures are slipping: Dow -0.15%, S&P 500 -0.17%, Nasdaq-100 -0.24%. The market is hesitating in front of the highs, not rejecting them.
What key levels should traders watch today?
SPX 7,780 — the record-high wall. The level just above Friday’s 7,722 close and the resistance the market has to clear to print a new high. A push through AND a hold above it on real trade, with breadth from the Dow and small caps rather than tech alone, is the tape saying it can break out even against a 24-year-high yield — a powerful signal, and the door opens higher if it holds. But don’t anticipate the breakout. Make price take and hold 7,780 after the open before you trust the long side; a near-record market stalling at resistance with yields climbing is exactly where failed breakouts live. SPX 7,722 — the axis. Friday’s close and the pivot the whole session turns on. Hold above it and the record-high test stays alive; this is the ‘let it prove itself’ zone where a market weighing a dovish Fed against rising yields tends to chop. The real signal is which side SPX leaves this level on once the open settles and ISM services lands at 10:00. Inside the range is noise; the move that follows is the trade. Patience beats forcing a position while the tape is still deciding which macro force it wants to trade. SPX 7,666 — the shelf that keeps a pullback orderly. The first real floor below the axis, roughly Thursday’s prior level. Hold it and a dip is just a dip inside an uptrend. Lose 7,666 and fail to reclaim it and the rising-yield pressure is finally showing up in price — the market is starting to trade the 5.28% 10-year as the thing that caps the rally, and the tape opens toward the next leg lower. Below 7,666 the job shifts to capital preservation. Mark it, and respect it if it goes.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – October 5, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.