Friday, October 2, 2026 · 4:30 PM ET · MTC Market Close
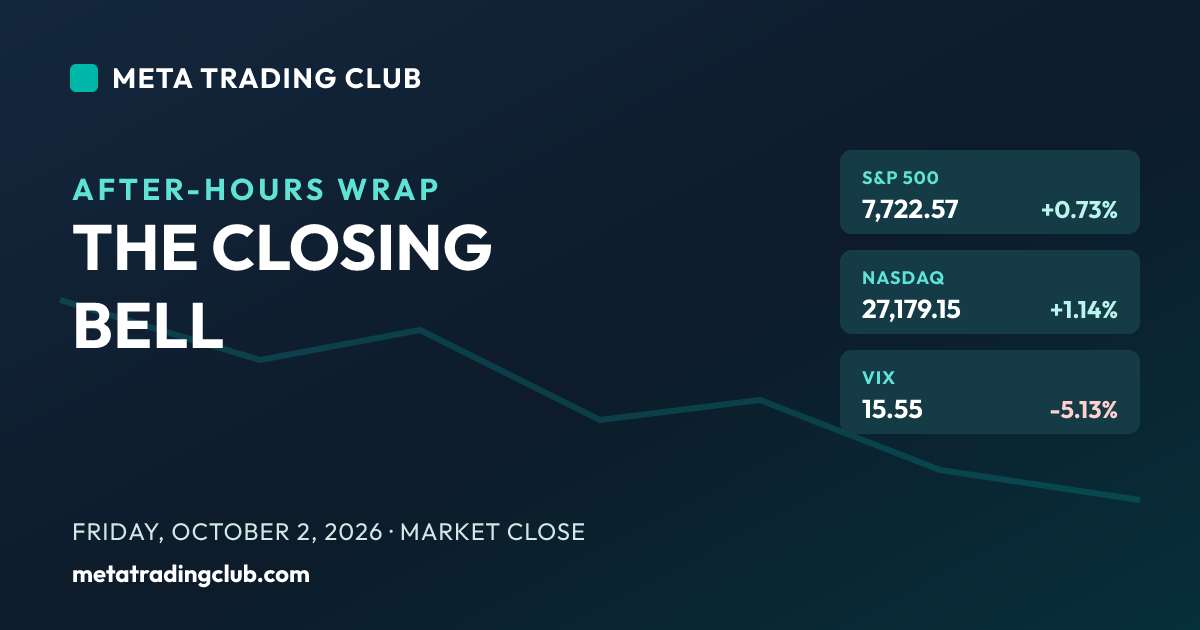
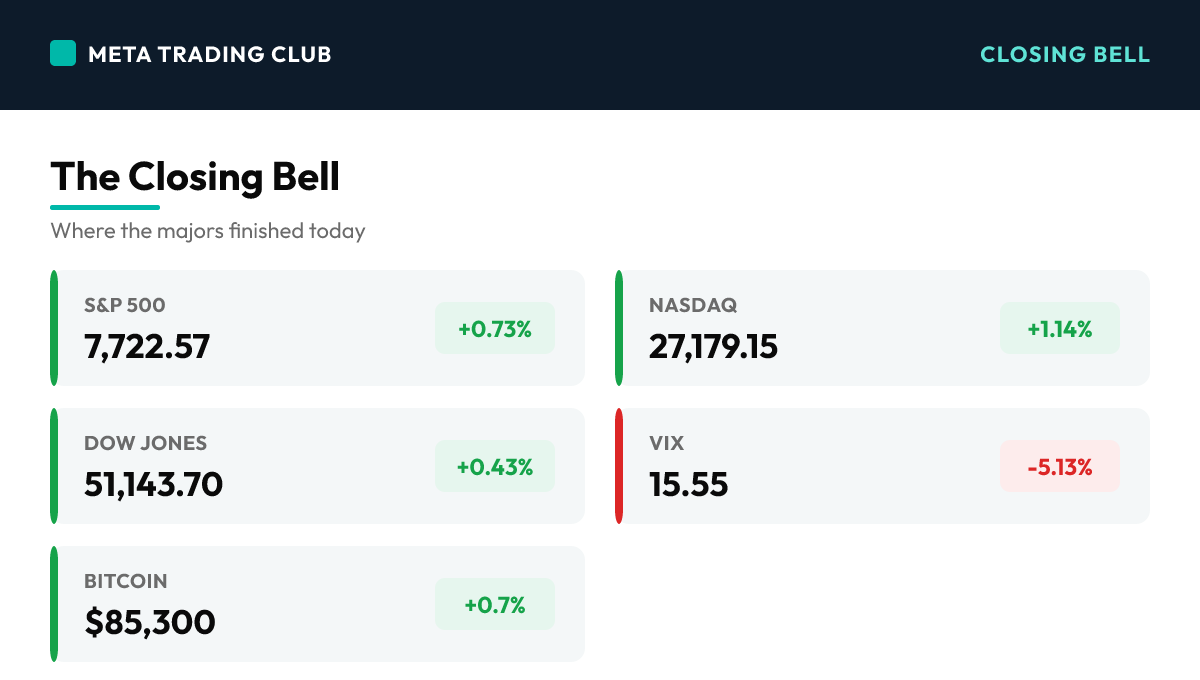
The stock market today got the number it was supposedly dreading and rallied anyway. September payrolls came in at just 29,000 jobs against the 84,000 Wall Street expected, and the unemployment rate ticked up to 4.2%. On paper that is a weak labor market. In practice it killed the fear of an October rate hike, and traders rotated straight back into growth. The S&P 500 closed up 0.73% at 7,722.57, right back near record highs. The Nasdaq led at 1.14% with Nvidia printing a fresh all-time intraday high and a $5.7 trillion market cap. The Dow added 0.43% and small caps rose 0.79%. Clean green across the board. The catch is what did not confirm it. The 10-year Treasury yield actually rose about 4 basis points to 5.28%, which means the bond market did not buy the dovish story the stock market was telling. And breadth was thin: roughly three of every four S&P names still sit below their 50-day average even as the index pushes highs. So you have a record-adjacent close built on a bad jobs number, with yields leaning the wrong way and participation narrow. The whole thing now hangs on one line: 7,700. Hold it and the highs stay in play. Lose it and this looks like a dovish-data pop that the tape could not back up.
The Closing Bell
| Instrument | Close | Change | Note |
|---|---|---|---|
| S&P 500 | 7,722.57 | +0.73% | Rose about 56 points to close at 7,722.57, back near record highs, as a weak September jobs report erased the fear of an October rate hike and sent money back into growth. The close was clean and green, but it sits just above the round number at 7,700, which is now the single most important line on the page. Buyers stepped in on dips through the afternoon, a constructive tell, yet the move was built on bad economic news rather than strength. Hold 7,700 and the record run stays alive. Lose it and today looks like a dovish-data pop. |
| Nasdaq | 27,179.15 | +1.14% | Led the majors, up about 307 points, as rate-cut-sensitive tech grabbed the wheel the moment the jobs report lowered the odds of a hike. Nvidia printed a fresh all-time intraday high near $237.88 and pushed its market cap past $5.7 trillion, dragging the chip and AI complex higher. The one crack under the surface was storage: Western Digital and Seagate both fell about 10% on a Toshiba supply scare. Growth led, but not uniformly. |
| Dow Jones | 51,143.70 | +0.43% | Added about 217 points to 51,143.70, a solid green close but a clear laggard to the Nasdaq. On a day money rotated into high-growth tech, the blue-chip index had the least to gain from the rate-cut re-pricing. A 0.43% gain that trails the Nasdaq by seven tenths of a point is exactly what a growth-led session looks like under the hood. |
| Russell 2000 | 2,836.54 | +0.79% | Climbed about 0.79%, firmly green and a fair read on a risk-on tape, but notably it was not the leader on a day the hike fear came off. Small caps are the most rate-sensitive corner of the market, so a 0.79% gain that trails the Nasdaq says the move was more about the AI-growth bid than a broad rate-relief rally. A decent day, not a dominant one. |
| VIX | 15.55 | -5.13% | Dropped about 5% to 15.55 as the event risk of the jobs report cleared and stocks pushed higher. The fear gauge coming off tells you traders exhaled once the number landed and the October hike came off the table. But a low VIX into a near-record close on thin breadth is not the same as a healthy market. It says complacency is building while participation stays narrow, which is a setup worth respecting, not chasing. |
| 10-Year Yield | 5.28% | +4 bp | The tell of the day. Yields initially fell on the weak jobs print, then reversed and closed higher, up about 4 basis points to 5.28%. That matters: the stock market celebrated a dovish jobs number while the bond market leaned the other way. With the G7 releasing oil reserves and diesel still near record prices, the long end is still pricing an inflation and supply story that a soft payrolls figure did not erase. When stocks and bonds disagree this sharply, the bond market usually gets the last word. |
| WTI Crude | $91.24 | -1.8% | Fell about 1.8% to settle near $91.24 after the G7 agreed to coordinate the release of 100 million barrels of oil and fuel from emergency reserves to ease a tight global market. Crude sold off hard at the open, down near $89, then pared the loss into the settle. The release is a direct response to the Iran war disruption and record diesel prices, and it took some of the energy-driven inflation pressure off at the margin. Level approximate into the settle. |
| Gold | $4,172.20 | -0.72% | Slipped about 0.7% to near $4,172 after rising early, giving back its gains as the risk-on tape pulled money toward equities and the firmer long-end yield raised the opportunity cost of holding a non-yielding asset. After a strong run, gold took a breather on a day traders chased growth. Level approximate into the settle. |
| Bitcoin | $85,300 | +0.7% | Firmed to near $85,300, up modestly, but the story was the fade: Bitcoin popped on the soft jobs data and then reversed most of the early gain as the session wore on. Crypto got the same initial rate-relief tailwind as small caps and chips, but its inability to hold the pop echoes the broader theme of the day, a market that rallied on the headline but could not fully confirm it underneath. Level approximate into the settle. |
Today’s Charts
Daily candlestick charts with 20/50/200-day moving averages — the index majors, the day’s biggest mover on each side, and the leading sector ETF.

Charts: Finviz (daily). Levels and overlays update through the next session.
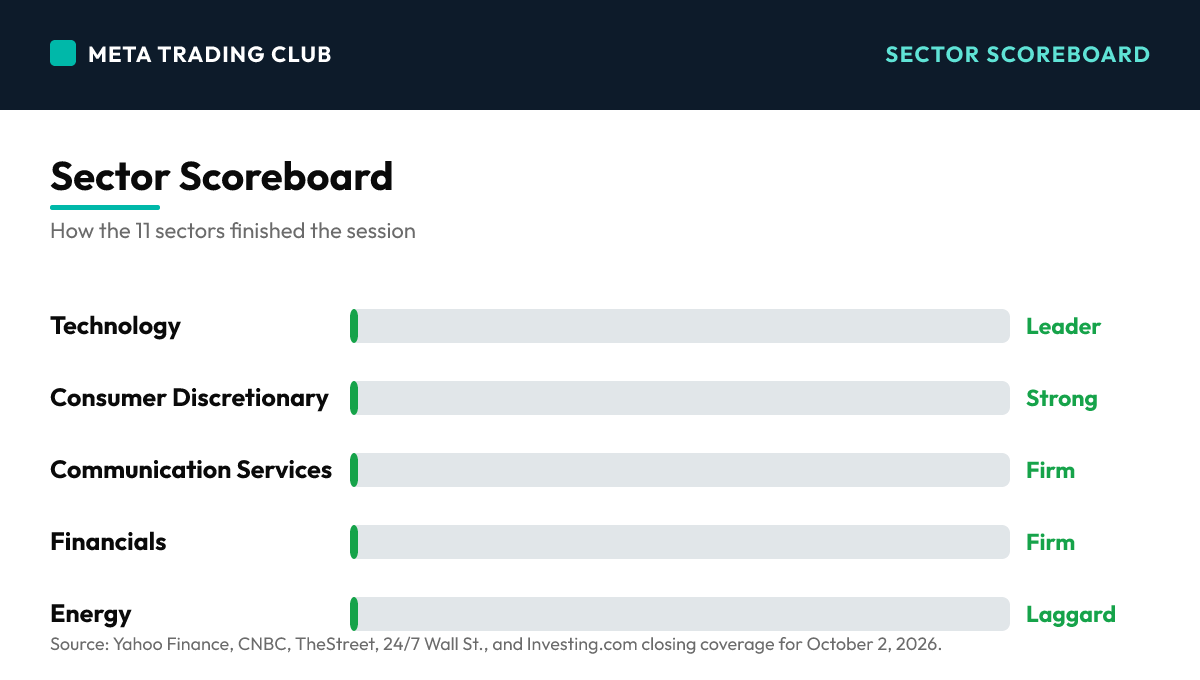
Sector Scoreboard
What Drove The Day
This was a bad-news-is-good-news session, and the whole thing turned on one data point. September payrolls landed at just 29,000 against the 84,000 expected, with unemployment up to 4.2%. A soft labor market on its own is not bullish, but it did one thing the market wanted badly: it took the October rate hike off the table, with CME odds of a hike collapsing to around 18%. That was the green light for growth. Money rotated straight into the rate-sensitive, high-multiple names, and the Nasdaq led at 1.14% with Nvidia printing a fresh record and a $5.7 trillion cap. The S&P closed up 0.73% at 7,722.57, back near all-time highs, with buyers stepping in on dips. But the confirmation was missing in two places. First, the 10-year yield rose instead of falling, closing up about 4 basis points at 5.28%, a clear sign the bond market did not endorse the dovish read. Second, breadth stayed thin, with roughly 75% of S&P names still under their 50-day average even at a near-record index level. Storage stocks got crushed on a Toshiba supply scare, with Western Digital and Seagate both off about 10%, a reminder the strength was selective. A clean green tape on the surface, a lot of unconfirmed signals underneath, and everything now keyed to whether 7,700 holds.
MAJOR HEADLINES AND CATALYSTS
Top Market-Moving Stories
- WEAK JOBS REPORT KILLS THE OCTOBER HIKE (Day) – September nonfarm payrolls came in at just 29,000 versus the 84,000 the Dow Jones consensus expected, and unemployment rose to 4.2% from 4.1%. A soft labor market, but it did exactly what the market wanted: CME FedWatch odds of an October rate hike collapsed to around 18%, with a hold now the heavy favorite at roughly 81%. That re-pricing was the green light for the rate-sensitive growth trade and the single reason stocks rallied.
- NVIDIA PRINTS A FRESH RECORD, CAP TOPS $5.7 TRILLION (Day) – Nvidia hit a new all-time intraday high near $237.88, eclipsing its prior peak and pushing its market cap past $5.7 trillion as investors piled back into AI hardware. It was the clearest expression of the day’s rotation into growth, and it dragged the broader chip and AI complex higher. When the largest stock in the market is making new highs, it pulls the indexes with it, but it also concentrates the gains.
- BOND MARKET REFUSES TO CONFIRM (Day) – Here is the catch. The 10-year Treasury yield fell on the weak jobs print and then reversed to close higher, up about 4 basis points at 5.28%. Stocks celebrated a dovish jobs number while bonds leaned the other way. With the G7 releasing oil reserves and diesel near record prices, the long end is still pricing an inflation and supply risk that a soft payrolls figure did not erase. A stock-bond disagreement this sharp is a signal, not noise.
- STORAGE STOCKS CRUSHED ON TOSHIBA SCARE (Day) – Western Digital fell about 10% and Seagate dropped roughly 10% after a report that Toshiba plans to invest around $380 million to double its hard-disk-drive capacity by fiscal 2027. SanDisk slipped as well. On a day the chip complex led the market higher, the storage corner got hammered on a supply-glut fear, a sharp reminder that the tech leadership was selective and the breadth under the rally was thin.
AFTER-HOURS EARNINGS SPOTLIGHT
A Light Post-Close Slate Into a Quiet Week
- LIGHT FRIDAY SLATE, EYES ON Q3 EARNINGS (AH) – There were no major earnings reports after the 4:00 PM close, a typical quiet Friday. The notable after-hours move was SoundHound AI, which slid about 6.5% in the post-close session, a high-volatility name swinging on positioning rather than a fresh catalyst. The real earnings story starts next week as third-quarter season opens up.
- THE WEEK AHEAD IS ABOUT CONFIRMATION, NOT DATA (AH) – Next week is light on top-tier economic data, with ISM Services on Monday and the September FOMC minutes on Wednesday as the main items, before Q3 earnings begin to flow with PepsiCo and Delta later in the week. With the October hike now priced out, the question flips: can earnings and breadth confirm a tape sitting at record highs, or does the thin participation and firmer long-end yield catch up to it?
WHAT IT SETS UP FOR THE WEEK AHEAD
7,700 Is the Whole Story
- 7,700 IS THE LINE THAT DECIDES IT (AH) – The S&P closed at 7,722.57, just above the round number at 7,700. That level is now the floor the bulls have to defend. Hold 7,700 on a pullback and the record run stays intact, with the AI-growth leadership carrying the tape toward fresh highs. Lose 7,700 and today’s dovish-data pop starts to look hollow, especially with breadth thin and the 10-year leaning higher. The first clean reaction at that line early next week tells you who is in control.
- WATCH THE 10-YEAR AND THE BREADTH (AH) – The two things that did not confirm today are the two things to watch into next week. If the 10-year keeps climbing past 5.30% toward its recent 24-year high, the rate relief that drove this rally evaporates and the record-adjacent close becomes a trap. And if breadth stays narrow, with three of four names below their 50-day, the index can drift higher on a handful of mega-caps right up until it cannot. Confirmation, or the lack of it, is the trade.
Winners & Losers
Winners
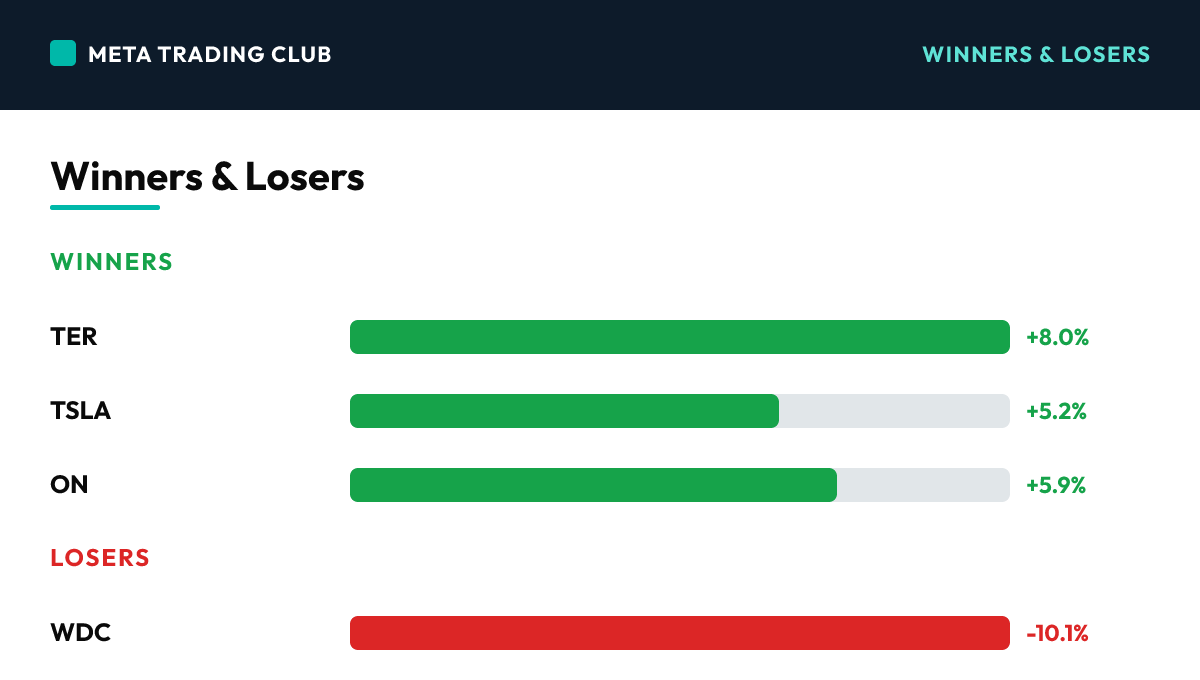
| TER | +8.0% | Teradyne led the entire board, jumping about 8% to near $449 after announcing a strategic partnership with Tokyo Electron. The automated-test-equipment maker was the cleanest single-stock winner on a day money rotated into the semiconductor and AI-infrastructure complex, and its partnership headline gave growth investors a concrete reason to pay up. | |
| TSLA | +5.2% | Tesla climbed about 5% after reporting third-quarter deliveries of 486,532 vehicles, topping the roughly 463,000 Bloomberg consensus, even as deliveries fell 2% from a year earlier. The beat, plus news its Megapack earned entry into Nvidia’s DSX Ready program for AI data centers, gave the stock a double catalyst on a risk-on day. | |
| ON | +5.9% | ON Semiconductor rose about 6% after revising its acquisition of Synaptics from an all-stock structure to a firm all-cash deal valued at $123 per share. A cleaner, more decisive deal structure was read as a vote of confidence, and the stock caught the broad semiconductor bid that lifted the group. |
Losers
| WDC | -10.1% | Western Digital fell about 10% after a report that Toshiba plans to invest roughly $380 million to double its hard-disk-drive manufacturing capacity by fiscal 2027. The prospect of a supply glut hit the data-storage group hard, and WDC was the clearest casualty, a sharp reminder that even on a strong tech day the leadership was selective and the breadth underneath was thin. | |
| STX | -10.0% | Seagate dropped about 10% to near $851 on the same Toshiba capacity-expansion report that hit Western Digital. The stock had run up roughly 190% year to date on tight memory supply, so a credible threat of new capacity triggered a swift sell-the-leader move. When a high-flyer breaks on a supply scare, the unwind is fast. | |
| ACN | -6.1% | Accenture fell about 6% to near $199, giving back a chunk of its prior-session earnings surge. After a sharp run on its results, the stock faded as the rotation favored high-growth chip and AI names over consulting and services, a fair example of money moving to where the momentum was on a risk-on day. |
What It Sets Up For Tomorrow
Levels Into Tomorrow
- S&P 500 7,700 – THE LINE THAT DECIDES IT. Price closed at 7,722.57, just above the round number after a weak-jobs rally pushed it back near record highs. This is the single most important level on the page. Hold 7,700 on any pullback, ideally with the 10-year staying calm, and the record run stays alive with AI-growth leadership in control. Lose it and today’s dovish-data pop loses its footing, especially on thin breadth and a firmer long-end yield. The first clean move relative to 7,700 early next week tells you who owns the tape.
- S&P 500 7,666 – THE FIRST SHELF BELOW. Thursday’s close and the first real support under today’s rally. As long as the S&P holds 7,666, today’s green close stays a constructive higher low and the growth bid stays intact. Lose 7,666, particularly if the 10-year pushes past 5.30% and breadth stays narrow, and the market is telling you the weak-jobs pop was not backed by real participation, opening the door toward 7,620.
- S&P 500 7,780 – THE UPSIDE TARGET. The next area of interest on a continuation. Clear and hold above the record zone, with the 10-year behaving and breadth starting to broaden, and the AI-led rally extends with buyers firmly in control. This is the level that would confirm today’s close was a breakout and not just a dovish-data spike, and it would need more than a handful of mega-caps to get there.
Bull case: The fear of an October rate hike is gone, collapsing to around 18% odds, and that is the ceiling this market has been fighting all month. With that off the table, the rate-sensitive growth trade has room to run, and Nvidia’s fresh record proves the AI bid is still the strongest force in the market. Buyers stepped in on dips all afternoon, a constructive sign, and the VIX fell as event risk cleared. If the S&P holds 7,700 and the 10-year stays calm into a quiet data week, the leadership broadens, breadth starts to repair, and 7,780 comes into play with the record run extending into Q3 earnings season.
Bear case: A rally that needs a weak economy to work is standing on soft ground. September payrolls at 29,000 is not a sign of strength, it is a sign the labor market is cracking, and the market is cheering it only because it stays the Fed’s hand. More telling, the bond market refused to confirm: the 10-year rose to 5.28% instead of falling, and if it pushes past 5.30% toward its 24-year high, the rate relief that powered this rally evaporates. Breadth is the other problem, with roughly 75% of S&P names below their 50-day even at a near-record index. That is a market being carried by a few mega-caps. Lose 7,700, then 7,666, and the dovish-data pop unwinds toward 7,620 fast.
Risks Into Tomorrow
- When stocks and bonds disagree, respect the bond market — Today the clearest signal was not the green screen, it was the split between the two markets. Stocks rallied hard on a weak jobs number because it killed the October hike. But the 10-year yield rose to 5.28% instead of falling, which means the bond market looked at the same data and did not agree the inflation and rate story was over. That disagreement matters. The bond market is larger, slower to get excited, and historically more right at turning points than the equity tape. When you see stocks celebrating and yields leaning the other way, the discipline is to treat the equity move as unconfirmed until the bond market comes along. That does not mean fade the rally on day one. It means do not chase it. You wait for the 10-year to roll over and validate the dovish read, or you watch price at 7,700 to tell you whether the equity enthusiasm can stand on its own. No confirmation, no conviction. You let the two markets agree before you lean in.
- A breadthless record is a narrow trade wearing a wide suit — The index made a near-record close today while roughly three of every four S&P names sat below their 50-day average. Sit with that. The headline says new highs, the internals say most stocks are not participating. That gap is the definition of a narrow market, and it happens when a handful of mega-caps, Nvidia chief among them, carry the whole tape. Narrow rallies can run far longer than they should, so this is not a reason to short. It is a reason to understand what you actually own when you buy the index here: a concentrated bet on a few names, not a healthy broad advance. The repeatable lesson is to check breadth before you trust a breakout. If the index is making highs and participation is improving, that is a real trend you can lean on. If the index is making highs while breadth deteriorates, you are late in a move being held up by fewer and fewer shoulders. Today was the second kind. You respect the trend, size accordingly, and watch for breadth to either confirm or crack.
- Bad news is good news works until the economy actually breaks — The market cheered a 29,000 payroll print and a rising unemployment rate because weakness means the Fed holds. That logic is real, but it has a shelf life. Bad-news-is-good-news works while the economy is slowing from strong to normal, because the only thing the market cares about is the rate path. It stops working the moment the data tips from soft to genuinely weak, because then the story flips from easier Fed to real earnings and growth risk. September’s 29,000 is close enough to that line to pay attention. The discipline here is to notice which regime you are in. Right now the market is treating weak data as a rate-cut catalyst. If payrolls keep deteriorating and the unemployment rate keeps rising, that same data becomes a recession signal, and the market stops rallying on it and starts falling on it. You cannot know in advance exactly where that line is, but you can watch for the day the market stops cheering bad news. That is the tell the regime has changed, and it is far more important than any single level.
Frequently Asked Questions
How did the S&P 500 close today?
On Friday, October 2, 2026, the S&P 500 closed at 7,722.57 (+0.73%), with the VIX at 15.55. The stock market today got the number it was supposedly dreading and rallied anyway.
What drove the market today?
WEAK JOBS REPORT KILLS THE OCTOBER HIKE (Day) – September nonfarm payrolls came in at just 29,000 versus the 84,000 the Dow Jones consensus expected, and unemployment rose to 4.2% from 4.1%. A soft labor market, but it did exactly what the market wanted: CME FedWatch odds of an October rate hike collapsed to around 18%, with a hold now the heavy favorite at roughly 81%. That re-pricing was the green light for the rate-sensitive growth trade and the single reason stocks rallied.
What levels matter for tomorrow?
S&P 500 7,700 – THE LINE THAT DECIDES IT. Price closed at 7,722.57, just above the round number after a weak-jobs rally pushed it back near record highs. This is the single most important level on the page. Hold 7,700 on any pullback, ideally with the 10-year staying calm, and the record run stays alive with AI-growth leadership in control. Lose it and today’s dovish-data pop loses its footing, especially on thin breadth and a firmer long-end yield. The first clean move relative to 7,700 early next week tells you who owns the tape. S&P 500 7,666 – THE FIRST SHELF BELOW. Thursday’s close and the first real support under today’s rally. As long as the S&P holds 7,666, today’s green close stays a constructive higher low and the growth bid stays intact. Lose 7,666, particularly if the 10-year pushes past 5.30% and breadth stays narrow, and the market is telling you the weak-jobs pop was not backed by real participation, opening the door toward 7,620. S&P 500 7,780 – THE UPSIDE TARGET. The next area of interest on a continuation. Clear and hold above the record zone, with the 10-year behaving and breadth starting to broaden, and the AI-led rally extends with buyers firmly in control. This is the level that would confirm today’s close was a breakout and not just a dovish-data spike, and it would need more than a handful of mega-caps to get there.
How does Meta Trading Club prepare for the next session?
We wrap every session and carry the read forward through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
New to this? Start with the free training.
Learn how we read the market before you risk a dollar — our free education library and ebook break down the fundamentals step by step.
Free education → Get the free ebookThe session’s over. The prep isn’t.
This is how MTC members close each day — wrap what happened, mark the levels, and carry one clean read into tomorrow. If you want to build that habit and qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process. It’s application-based — see if it’s a fit.
Explore the MTC Incubator → Apply nowSources: Yahoo Finance, CNBC, TheStreet, 24/7 Wall St., and Investing.com closing coverage for October 2, 2026.. For educational purposes only. Not financial advice.