Wednesday, September 30, 2026 · 4:30 PM ET · MTC Market Close
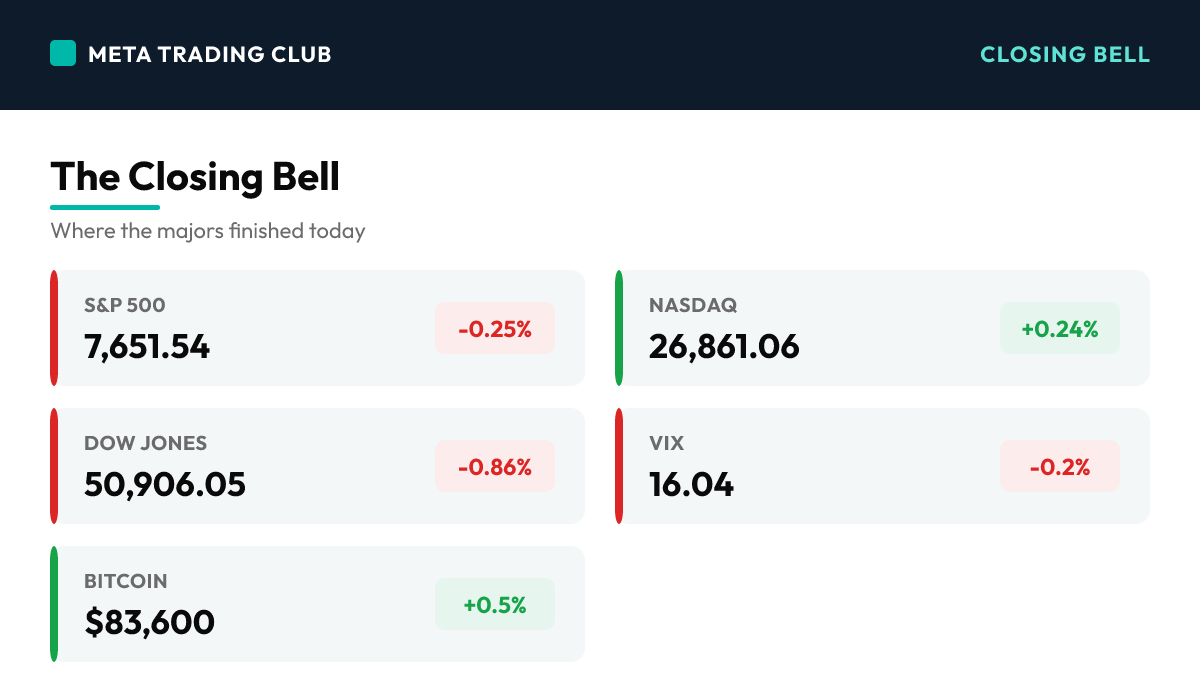
The stock market today got the news it wanted and sold it anyway. August PCE came in cool across the board, headline at 3.4% versus 3.7% expected and core at 3.0% versus 3.3%, the 10-year backed off its 2007 high to 5.23%, and the S&P 500 was up as much as 0.7% on the print. Then the tape faded. The S&P closed down 0.25% at 7,651.54, the Dow dropped 444 points or 0.86% to 50,906.05, and only the Nasdaq held green, up 0.24% to 26,861.06, carried by a handful of mega-cap tech names while Apple fell 2% and breadth crumbled underneath. This was a narrow, divergent close on the last day of a losing September, and it hands Thursday a clean binary: the S&P shut the month sitting right on 7,650, so hold that line and October’s buyers get the benefit of the doubt, lose it and the weak breadth becomes the story.
The Closing Bell
| Instrument | Close | Change | Note |
|---|---|---|---|
| S&P 500 | 7,651.54 | -0.25% | Faded about 19 points to close at 7,651.54 after being up as much as 0.7% earlier in the day on the cool PCE print. That intraday reversal is the whole story: the index got the soft inflation number it had been waiting for and could not hold the gain. It closed the month sitting almost exactly on 7,650, which makes that the single most important level on the page. Hold it into October and this is a healthy pause; lose it and today’s thin breadth becomes the trend. |
| Nasdaq | 26,861.06 | +0.24% | The only major index to finish green, up about 64 points as a narrow group of mega-cap tech names, Meta, Nvidia and Amazon, held the line while most of the tape sold off. Cool PCE eased the pressure on the long-duration growth complex, so the highest-multiple names got the most relief. But green built on three or four stocks is not broad strength, and Apple’s 2% drop shows even the mega-cap trade was not uniform today. |
| Dow Jones | 50,906.05 | -0.86% | The day’s biggest loser among the majors, down about 444 points, dragged by Apple’s 2% slide and a weak financials complex that has been the worst sector all month. The Dow carries no duration tailwind from the PCE relief and the most cyclical, rate-sensitive corners of the tape did the damage. A 444-point drop on a day inflation came in soft tells you the selling was about positioning and breadth, not the data. |
| Russell 2000 | 2,838 | +0.3% | Firmed modestly, the small-cap tell that the cool inflation print did offer some relief to the most rate-sensitive corner of the market. With the 10-year backing off its 2007 high, borrowing-cost pressure eased at the margin and small caps caught a small bid. But a 0.3% gain on a day the Dow fell 444 points is a mixed, low-conviction read, not a rotation. Level approximate into the close. |
| VIX | 16.04 | -0.2% | Barely moved, holding near 16 as the tape faded in an orderly, mechanical way rather than a panic. A calm VIX on a day the Dow drops 444 points is a classic quarter-end tell: this was rotation and repositioning, not fear. The trap is reading a quiet VIX as an all-clear. Low volatility does not mean low risk when the underlying issue, thin breadth on the last day of a losing month, is still fully intact. |
| 10-Year Yield | 5.23% | -1 bp | Backed off about a basis point to 5.23% after the cool PCE print pulled it down from the 2007 high it touched earlier in the week, with the 30-year also retreating. This was the market’s reward for soft inflation, and it is exactly why the Nasdaq could hold green. The catch is that a 5.23% 10-year is still restrictive, and traders pushed the next expected Fed hike out to December, keeping higher-for-longer very much alive. |
| WTI Crude | $89.11 | -0.3% | Eased slightly to hold near $89.11, drifting lower as the geopolitical premium that had lifted crude earlier in the week faded and the focus shifted back to demand and supply. A softer oil tape takes some pressure off the inflation narrative, which fits the cool PCE read, but energy could not lean on it today. Level reflects the front-month contract into the settle. |
| Gold | $4,217 | +0.9% | Climbed about $38 to settle near $4,217 an ounce, catching a bid as real yields eased on the cool inflation print. After getting crushed earlier in the week on the real-yield spike, gold got exactly the relief it needed when the 10-year backed off its 2007 high. A softer rate backdrop lowers the opportunity cost of holding a non-yielding asset, and the metal took advantage. Level approximate into the settle. |
| Bitcoin | $83,600 | +0.5% | Firmed modestly to hold near $83,600 as the softer rate backdrop gave speculative assets a small tailwind. Bitcoin did not lead the way the mega-cap tech names did, but an easing 10-year is a supportive backdrop for risk, and the modest gain fits the day’s split tone: relief where duration matters, weakness where breadth does. Level approximate into the settle. |
Today’s Charts
Daily candlestick charts with 20/50/200-day moving averages — the index majors, the day’s biggest mover on each side, and the leading sector ETF.

Charts: Finviz (daily). Levels and overlays update through the next session.
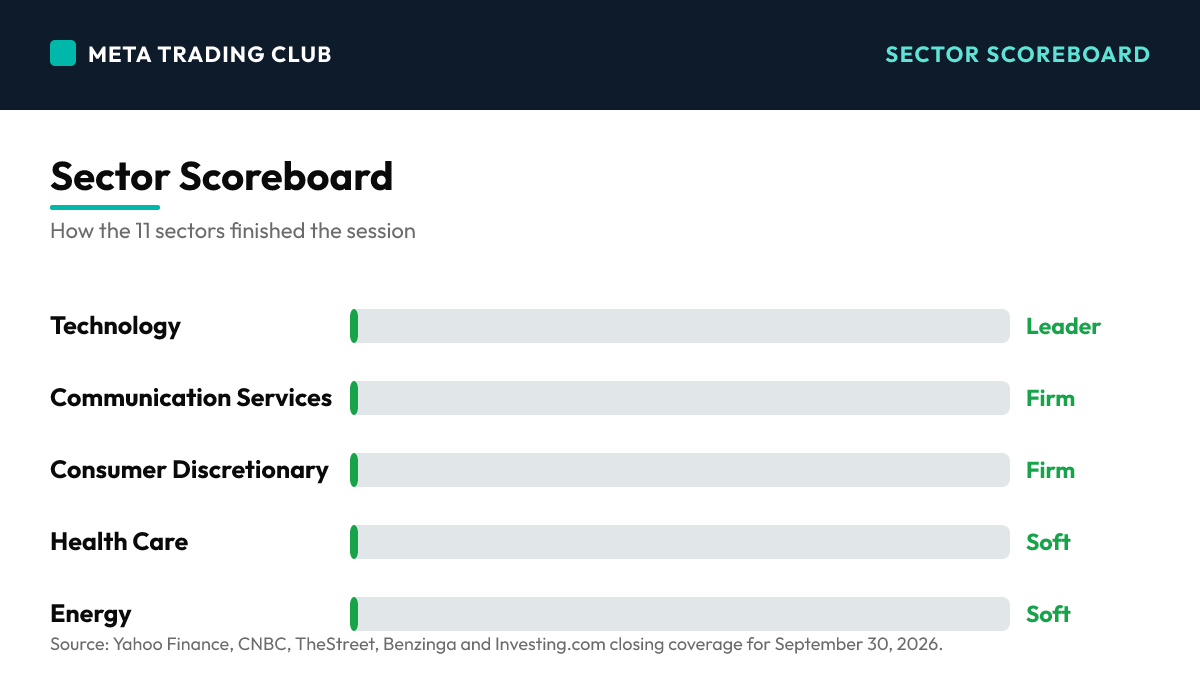
Sector Scoreboard
What Drove The Day
This was a textbook divergent close, and the tell was in the reversal. August PCE landed cool across the board, headline 3.4% and core 3.0%, both below expectations, the 10-year backed off its 2007 high to 5.23%, and the S&P jumped as much as 0.7% out of the gate. Then it faded all day and closed red. The order of the damage explains why: the Nasdaq held green on mega-cap tech getting duration relief, while the Dow dropped 444 points on Apple and a broken financials complex, and the S&P split the difference to finish just below flat. A calm VIX near 16 confirmed this was orderly quarter-end repositioning, not fear. The data was fine. The internals were not, and on the last day of a losing September that mattered more than the print.
MAJOR HEADLINES AND CATALYSTS
Top Market-Moving Stories
- COOL PCE FAILS TO HOLD THE RALLY (Day) – The Fed’s preferred inflation gauge came in soft across the board: headline PCE rose 3.4% year over year versus 3.7% expected, and core PCE eased to 3.0% versus 3.3%, with the monthly readings also below consensus. The market’s first reaction was exactly right, stocks jumped and the 10-year backed off its 2007 high, but the S&P gave back a 0.7% gain and closed red. When good news cannot hold a rally, the tape is telling you something about positioning, not data.
- THE DOW SHEDS 444 POINTS ON THIN BREADTH (Day) – The Dow fell 0.86%, or about 444 points, to 50,906.05, the worst of the majors, dragged by Apple’s 2% slide and a financials complex that has been the market’s weakest group all month. On a day inflation came in cool, a drop of this size is a breadth story, not a macro one. Most stocks were red while a handful of mega-cap tech names held the Nasdaq green, the definition of a narrow, top-heavy tape.
- BOEING JUMPS ON NAVY FIGHTER CONTRACT (Day) – Boeing climbed more than 2% after the U.S. Navy selected the company to build its next-generation carrier-based fighter jet, a marquee multi-year defense program that provides a long revenue runway. It was one of the day’s cleanest single-stock catalysts and a rare bright spot in an otherwise heavy industrials and cyclical complex.
- SEPTEMBER CLOSES AS A LOSING MONTH (Day) – The final session of the quarter locked in a losing September for two of the three majors: the Dow finished the month down about 4.9% and the S&P about 0.7%, while the Nasdaq clung to a 1.7% monthly gain on mega-cap tech strength. Quarter-end repositioning added to the fade, and the split monthly scorecard, tech up, everything else down, is the same narrow-leadership problem carried across the whole month.
AFTER-HOURS EARNINGS SPOTLIGHT
A Light Post-Close Slate Keeps Macro in Charge
- A THIN AFTER-HOURS SLATE LET THE MACRO STORY OWN THE EVENING (AH) – The post-close earnings calendar was light on September 30, with no heavyweight tech or mega-cap print to shift the narrative. That kept the spotlight exactly where it had been all session: on the cool PCE data, the 444-point Dow drop, and the S&P closing the month right on 7,650. When the after-hours tape is quiet, the day’s price action is the story that carries into the next open.
- EARNINGS SEASON IS THE NEXT CATALYST WINDOW (AH) – With the quarter now closed, the market’s attention shifts to the Q3 reporting season that ramps up over the next two weeks, led by the big banks. On a tape where financials have been the weakest group all month, those bank prints will be the first real test of whether the sector’s September damage was justified or overdone. For now, the macro calendar leads and earnings are the catalyst on deck.
WHAT IT SETS UP FOR THURSDAY
A Data-Heavy Start to October
- ISM MANUFACTURING AND JOBLESS CLAIMS HEADLINE THURSDAY (AH) – October opens with a busy calendar: weekly initial jobless claims are expected near 201,000 before the bell, and the ISM Manufacturing PMI lands at 10:00 AM ET as the first read on how factories did in September, alongside ISM prices, new orders, and construction spending. On a tape this sensitive to the rate path, a hot prices-paid or new-orders number would push yields back up; a soft set keeps the PCE relief alive.
- 7,650 IS THE LINE THAT DECIDES OCTOBER’S OPEN (AH) – The S&P closed the month sitting almost exactly on 7,650. That is now the single most important level on the page. Hold it on Thursday and today’s fade stays a healthy, orderly pause with October’s buyers keeping the benefit of the doubt. Lose it, especially if the ISM data pushes yields higher, and the thin breadth that defined today becomes the story, opening 7,600 then 7,550.
Winners & Losers
Winners
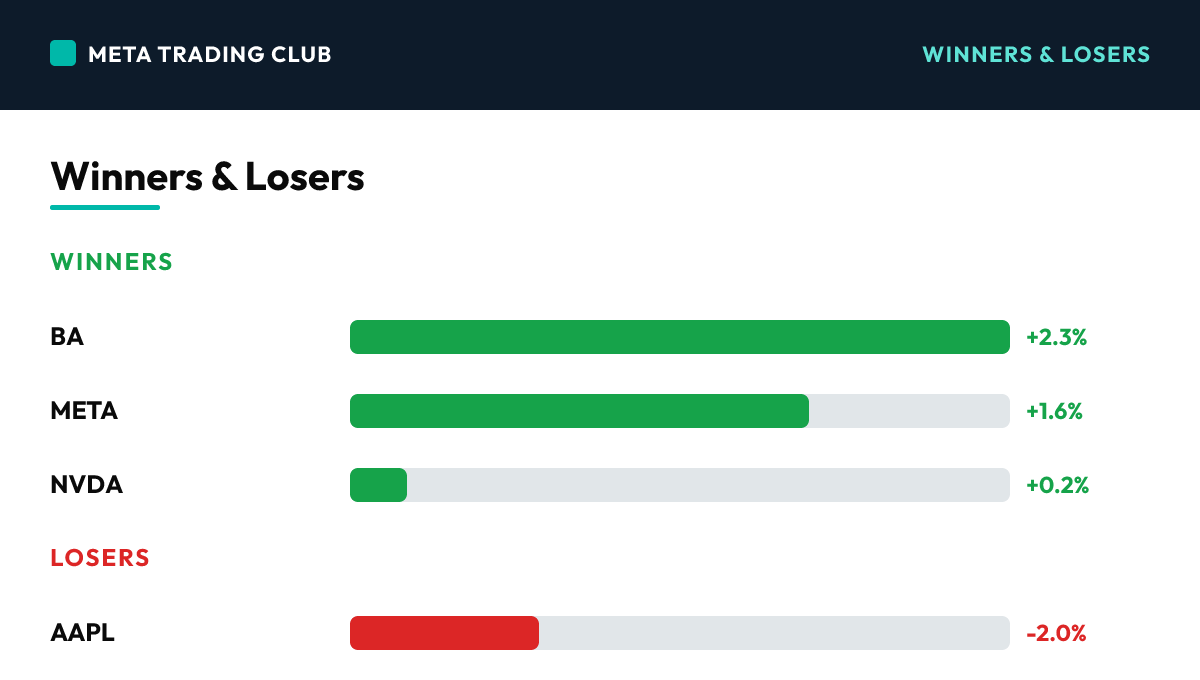
| BA | +2.3% | Boeing was one of the day’s cleanest winners, climbing more than 2% after the U.S. Navy selected the company to build its next-generation carrier-based fighter jet. A marquee multi-year defense contract provides a long, visible revenue runway, and it was a rare bright spot in an otherwise heavy industrials and cyclical complex on a narrow tape. | |
| META | +1.6% | Meta led the mega-cap advance, gaining about 1.6% as the cool PCE print eased pressure on the long-duration growth trade and sent money into the largest platform names. Meta was one of the few stocks doing the heavy lifting to keep the Nasdaq green while most of the tape sold off, the signature of the day’s narrow leadership. | |
| NVDA | +0.2% | Nvidia leaned green as the AI and semiconductor complex caught the duration-relief bid from the soft inflation data. The move was modest, but on a day breadth crumbled and the Dow fell 444 points, simply staying on the right side of the tape put Nvidia among the mega-cap names holding the Nasdaq up. Move approximate. |
Losers
| AAPL | -2.0% | Apple was the single biggest drag on the Dow, falling about 2% and pulling the blue-chip index to its 444-point loss. On a day the cool PCE print lifted the rest of mega-cap tech, Apple’s slide stood out and underlined how narrow the leadership really was: even the strongest sector of the day was not uniform, and its largest name was on the wrong side. | |
| MRNA | -7.0% | Moderna was one of the worst single-stock stories, sliding about 7% after a Wall Street firm downgraded the shares to sell on valuation, noting how far the stock had run. A downgrade of that size on a high-flying biotech name dragged on sentiment across the group and helped push health care lower on the day. | |
| TSLA | -1.4% | Tesla fell about 1.4%, one of the mega-cap names on the wrong side of a narrow tape. With leadership concentrated in a few platform and chip names, the high-beta growth stocks outside that group leaned lower, and Tesla drifted down with the broad fade rather than catching the duration-relief bid. Move approximate. |
What It Sets Up For Tomorrow
Levels Into Tomorrow
- S&P 500 7,650 – THE LINE THAT DECIDES IT. Price closed at 7,651.54, sitting almost exactly on the 7,650 shelf as the month ended. This is the single most important level on the page. Hold 7,650 and today’s fade stays an orderly, quarter-end pause with the bulls keeping the benefit of the doubt into October. Lose it decisively, especially with the ISM data able to push yields back up, and today’s thin breadth becomes the story, opening 7,600 then 7,550. The first clean move relative to 7,650 tells you who owns the tape to start the new month.
- S&P 500 7,700 – THE RECLAIM LEVEL. The round number the index has been capped below and the first hurdle for any bounce. Reclaim 7,700 and hold it, ideally on soft ISM data keeping yields calm, and today’s fade gets written off as quarter-end noise. Fail there and the sellers keep the upper hand. Watching how price behaves at 7,700 on the way back up is the cleanest tell that buyers have regained control and breadth is repairing.
- S&P 500 7,600 – THE SHELF BELOW. The next real support if 7,650 gives way. As long as the S&P holds the 7,600 to 7,650 zone, this stays an orderly pullback inside the range. Lose 7,600 and the market is telling you the thin breadth is winning and the September weakness is carrying into October, with the weakest groups, financials and the cyclicals, likely to lead the move lower.
Bull case: Today was quarter-end noise on top of good news, not the start of a downtrend. Inflation came in cool across the board, the 10-year backed off its 2007 high, and the mega-cap tech complex is still working. If Thursday’s ISM data comes in soft and yields stay calm, the duration relief that held the Nasdaq green broadens out, 7,650 holds, and the buyers who have defended this range step back in to start October. A calm VIX near 16 says today’s selling was orderly repositioning, not a flush, and orderly pauses in a range are where the next leg gets bought.
Bear case: A market that fades a 0.7% gain on cool inflation has a breadth problem it cannot hide. Financials are down more than 6% on the month, the Dow just dropped 444 points, and the whole tape is leaning on three or four mega-cap names to stay afloat. If Thursday’s ISM prices or new orders run hot, yields push back up, the duration relief evaporates, and the S&P loses 7,650 with the weakest groups leading. Lose that line and today’s narrow, top-heavy tape stops being a one-day fade and becomes October’s trend, with 7,600 and 7,550 the next stops.
Risks Into Tomorrow
- When good news can’t hold a rally, watch positioning, not the headline — The market got exactly the inflation print it wanted today. Headline PCE cooled to 3.4%, core to 3.0%, both below expectations, and the S&P jumped 0.7% on the news. Then it faded all day and closed red. That reversal is the lesson. When a market cannot hold a rally on good news, the problem is not the data, it is positioning, breadth, and who is left to buy. On the last day of a losing September, with quarter-end repositioning in the tape, the fade told you more than the PCE number did. The discipline is to read the reaction, not the release. A soft print that gets sold is a warning; a soft print that gets bought and held is a green light. Today was the former, and that is why 7,650 matters more than the 3.4% headline. No alignment between the news and the tape means you wait for price to confirm before trusting the bounce.
- Narrow leadership is a warning, even when the index is green — The Nasdaq closed green today, but strip out Meta, Nvidia and Amazon and the picture changes fast: the Dow fell 444 points, Apple dropped 2%, financials led the tape lower, and most stocks were red. A green index built on three or four mega-cap names is not broad strength, it is a top-heavy tape leaning on a handful of stocks. This is a repeatable tell. When the index is up but breadth is down, the rally is fragile, because the moment those few leaders wobble there is nothing underneath to catch the tape. The skill is to read breadth alongside price. Watch the advance-decline line and the equal-weight index, not just the cap-weighted headline. When they diverge the way they did today, the market is telling you the strength is narrow and the risk is higher than the green number suggests.
- A calm VIX at quarter-end is repositioning, not permission — The VIX barely moved today, holding near 16 while the Dow dropped 444 points. That low reading can be a trap. It tells you the selling was orderly and mechanical, classic quarter-end repositioning rather than a panic, and traders read a calm VIX as a sign the worst is over. But an orderly fade on the last day of a losing month, with breadth this thin, is not the same as a healthy market. Low volatility does not mean low risk when the underlying issue, narrow leadership and a weak financials complex, is still fully intact. The mistake is to buy the dip because the VIX is calm, when calm just means the market is repositioning efficiently, not that the breadth problem is solved. The plan is to separate the emotion gauge from the internals: watch breadth and the 7,650 line for your signal, not the VIX. A quiet VIX on a red, narrow tape is a reason for patience, not a green light.
Frequently Asked Questions
How did the S&P 500 close today?
On Wednesday, September 30, 2026, the S&P 500 closed at 7,651.54 (-0.25%), with the VIX at 16.04. The stock market today got the news it wanted and sold it anyway.
What drove the market today?
COOL PCE FAILS TO HOLD THE RALLY (Day) – The Fed’s preferred inflation gauge came in soft across the board: headline PCE rose 3.4% year over year versus 3.7% expected, and core PCE eased to 3.0% versus 3.3%, with the monthly readings also below consensus. The market’s first reaction was exactly right, stocks jumped and the 10-year backed off its 2007 high, but the S&P gave back a 0.7% gain and closed red. When good news cannot hold a rally, the tape is telling you something about positioning, not data.
What levels matter for tomorrow?
S&P 500 7,650 – THE LINE THAT DECIDES IT. Price closed at 7,651.54, sitting almost exactly on the 7,650 shelf as the month ended. This is the single most important level on the page. Hold 7,650 and today’s fade stays an orderly, quarter-end pause with the bulls keeping the benefit of the doubt into October. Lose it decisively, especially with the ISM data able to push yields back up, and today’s thin breadth becomes the story, opening 7,600 then 7,550. The first clean move relative to 7,650 tells you who owns the tape to start the new month. S&P 500 7,700 – THE RECLAIM LEVEL. The round number the index has been capped below and the first hurdle for any bounce. Reclaim 7,700 and hold it, ideally on soft ISM data keeping yields calm, and today’s fade gets written off as quarter-end noise. Fail there and the sellers keep the upper hand. Watching how price behaves at 7,700 on the way back up is the cleanest tell that buyers have regained control and breadth is repairing. S&P 500 7,600 – THE SHELF BELOW. The next real support if 7,650 gives way. As long as the S&P holds the 7,600 to 7,650 zone, this stays an orderly pullback inside the range. Lose 7,600 and the market is telling you the thin breadth is winning and the September weakness is carrying into October, with the weakest groups, financials and the cyclicals, likely to lead the move lower.
How does Meta Trading Club prepare for the next session?
We wrap every session and carry the read forward through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
New to this? Start with the free training.
Learn how we read the market before you risk a dollar — our free education library and ebook break down the fundamentals step by step.
Free education → Get the free ebookThe session’s over. The prep isn’t.
This is how MTC members close each day — wrap what happened, mark the levels, and carry one clean read into tomorrow. If you want to build that habit and qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process. It’s application-based — see if it’s a fit.
Explore the MTC Incubator → Apply nowSources: Yahoo Finance, CNBC, TheStreet, Benzinga and Investing.com closing coverage for September 30, 2026.. For educational purposes only. Not financial advice.