Wednesday, September 30, 2026 · 8:45 AM ET · MTC Market Intelligence
The stock market today is steady, but only because everyone is standing still ahead of the one number that matters. Tuesday the tape leaked again — the Dow slipped 131.59 points, or 0.26%, to 51,349.92, the S&P 500 eased 0.17% to 7,670.84, and the Nasdaq Composite held up best, off just 0.09% to 26,797.54 — as the 10-year Treasury yield pushed to a fresh multi-decade high near 5.28%. That yield is the whole story. This morning futures are barely green — S&P 500 futures up about 0.05%, Nasdaq-100 futures leading at roughly +0.15%, Dow futures up about 0.10% — because the market is frozen ahead of the August PCE inflation report at 8:30 AM ET, the Fed’s preferred gauge. This is the print that either justifies yields at 5.28% or takes some pressure off. A hot core PCE and the 10-year presses higher and the rate-sensitive tape leaks again; a cool print and yields ease and the chips get room to run. Oil is helping at the margin — WTI eased about 3.5% Tuesday back near $89, taking a little heat off the inflation-and-yield loop. And it’s month-end and quarter-end, so rebalancing flows can distort the tape into the close. But none of that changes the setup: this is a market held hostage by the bond market into a single data point. Today is a lesson in patience — you don’t trade the PCE number, you trade how price reacts to it at your level. SPX 7,700 is the reclaim the open has to earn back, 7,640 is the shelf that keeps the selloff contained, and 7,600 is the downside if that shelf breaks. Micron reports after the close as the marquee AI read. No alignment, no trade.
Market Snapshot
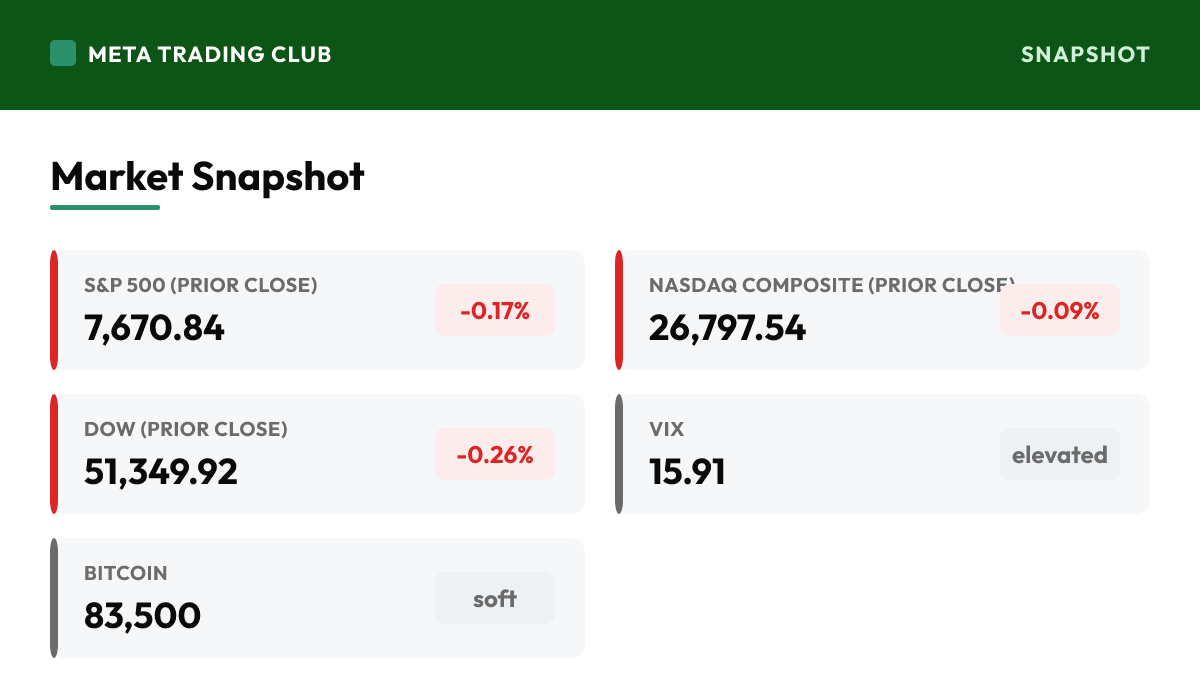
| Instrument | Level | Change | Note |
|---|---|---|---|
| S&P 500 (prior close) | 7,670.84 | -0.17% | Closed Tuesday at 7,670.84, down 0.17%, grinding lower for a second straight session as the 10-year pushed to a fresh multi-decade high. That close is the axis this morning: futures are barely green, so the first job of the open is whether cash can reclaim and hold 7,700 once the PCE number crosses. Don’t read a flat premarket as strength — it’s the market holding its breath, not buying. The reaction to the data at the level, not the futures print, is what tells you which way this breaks. |
| Nasdaq Composite (prior close) | 26,797.54 | -0.09% | Held up best Tuesday, off just 0.09% to 26,797.54, as the megacap and chip names absorbed the yield pressure better than the broad tape. This morning Nasdaq-100 futures lead the majors at about +0.15% — a thin edge, not a green light. When high-multiple growth is the relative winner into a hot rate backdrop, it’s usually because money has nowhere better to hide, not because the pressure is gone. Watch whether it can hold that lead once PCE hits; the chips are the highest-beta read on the reaction. |
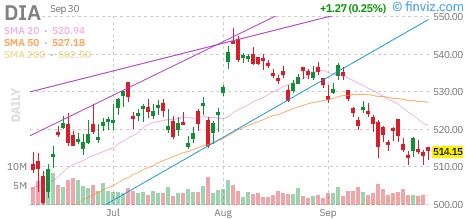
| Dow (prior close) | 51,349.92 | -0.26% | Slipped 131.59 points Tuesday, off 0.26% to 51,349.92, the weakest major as the blue chips leaked with rising yields. This morning Dow futures are up about 0.10%, a modest steadying, but the broad-tape weakness of the last two sessions is the honest signal: with the 10-year at 5.28%, the rate-sensitive, value-heavy corners feel it first. A small green print into PCE isn’t participation — it’s positioning. Watch whether the Dow can actually widen a bounce after the data or keeps lagging the chips. |
| S&P 500 Futures | — | +0.05% | Up about 0.05% this morning — essentially flat, pointing to a quiet open right at Tuesday’s 7,670 close. Don’t over-read it: a dead-flat futures tape into an 8:30 inflation print is the market refusing to commit before it sees the number. The signal isn’t the direction, it’s the indecision. Watch whether the index can reclaim and hold 7,700 once PCE crosses and cash trades — the reaction at the level is the real tell, not the premarket print. |
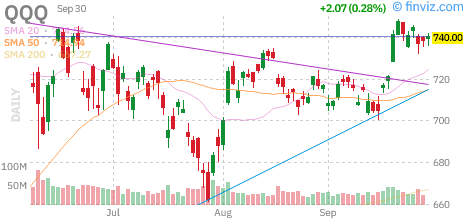
| Nasdaq-100 Futures | — | +0.15% | Up about 0.15%, the strongest major as the chips hold a slim edge into the data — Nvidia and Micron steady premarket, with Micron reporting after Wednesday’s close. High-multiple growth leads first when the tape is bracing, but it’s also the first to roll over if PCE runs hot and yields press again. The Nasdaq is the tell: if the chips can hold their edge through the inflation print, the tape has a foundation; if they fade, there’s no leader to lean on. |
| Dow Futures | — | +0.10% | Up about 0.10%, a modest steadying after two soft sessions for the blue chips. The Dow has been the weakest major as yields climbed — the value and rate-sensitive names feel a 5.28% 10-year first. A small green print into PCE is positioning, not a broad bid. Watch whether participation widens after the data: if the Dow joins a post-print bounce, it’s healthier; if it keeps lagging while the chips carry the tape, the move stays narrow and fragile. |
| VIX | 15.91 | elevated | Holding near 16 after jumping about 7% Tuesday as yields pushed to fresh highs and nerves ticked up into the data. It’s still a low absolute reading, but the direction matters — the options market is pricing a little more caution ahead of PCE, not less. A low-but-rising VIX into the Fed’s preferred inflation gauge is exactly the setup where a surprise reprices volatility fast. Respect that calm can flip in seconds if the number lands hot. |
| WTI Crude | 89.38 | easing | Down about 3.5% Tuesday, settling near $89 as the war premium continued to deflate — the reverse of last week’s spike. Cooling crude is the quiet help this morning: it takes some heat off the inflation-and-yield loop that’s been pressuring the tape. If oil keeps rolling over, it eases the pressure on the 10-year at the margin. But it’s a supporting actor today — the real driver is the PCE print and how the bond market reacts to it, not crude. |
| 10-Yr Yield | 5.28% | higher | Pushed to a fresh multi-decade high near 5.28%, up about 4 basis points, and it’s the single most important number on the screen. Everything about this tape runs through the bond market: yields at generational highs are the ceiling over the rate-sensitive corners, and stocks have been leaking for two sessions because of it. The PCE print at 8:30 is a direct referendum on whether 5.28% is justified. Watch the yield reaction to the data more closely than any single stock — it leads the whole tape. |
| Bitcoin | 83,500 | soft | Holding just above $83,000, soft and down sharply on the year, as the highest-beta risk assets stay pressured with rates at a generational high. Crypto leaking while equities hold steady is a split-tape signal: risk appetite is selective, not broad. Treat Bitcoin’s softness as a caution flag on how much risk the market is really willing to carry into the PCE print — not as an all-clear. When rates are this high, the speculative end of the curve feels it first. |
Charts to Watch
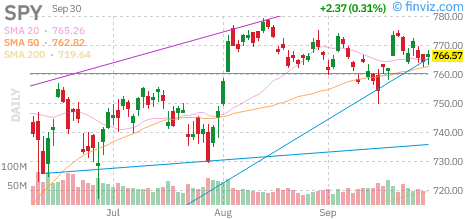
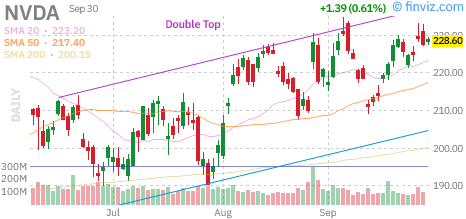
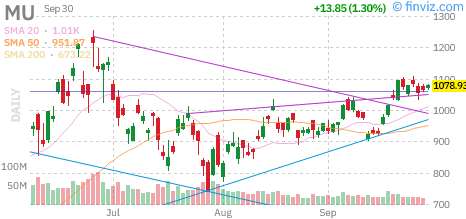
Daily candle charts with moving averages for the index proxies and today’s standout mover. Source: Finviz.
Performance at a Glance
Overnight & Global Markets
Tuesday was a slow bleed, not a crash — the Dow slipped 131.59 points, or 0.26%, to 51,349.92, the S&P 500 eased 0.17% to 7,670.84, and the Nasdaq Composite held up best, off just 0.09% to 26,797.54 — all pressured by the 10-year Treasury yield pushing to a fresh multi-decade high near 5.28%. This morning the tape is dead flat, and the flatness is the tell: S&P 500 futures up about 0.05%, Nasdaq-100 futures leading at roughly +0.15%, Dow futures up about 0.10%. Nobody wants to commit ahead of the August PCE inflation report at 8:30 AM ET — the Fed’s preferred gauge and the number that either justifies yields at 5.28% or takes some pressure off. Oil is a quiet help: WTI eased about 3.5% Tuesday back near $89 as the war premium deflated, easing the inflation-and-yield loop at the margin. But the regime hasn’t moved — the bond market is in control, yields sit at a generational high, and it’s month-end and quarter-end, so rebalancing flows can distort the tape into the close. This is a market held hostage by one data point: a hot core PCE and the 10-year presses higher and the rate-sensitive tape leaks again; a cool print and yields ease and the chips get room to run. Today is a lesson in reaction versus prediction — you don’t trade the PCE number, you trade how price reacts to it. Mark 7,700 as the reclaim, 7,670 as the axis, 7,640 as the shelf, and 7,600 below, and let price prove which side it wants before you act.
MAJOR HEADLINES AND CATALYSTS
Top Premarket Stories
- The entire tape is frozen ahead of the August PCE inflation report at 8:30 AM ET. This is the Fed’s preferred gauge, and it’s the number that either justifies the 10-year at a fresh multi-decade high near 5.28% or takes some pressure off. Futures are dead flat — S&P +0.05%, Nasdaq-100 +0.15%, Dow +0.10% — because nobody wants to commit before the print. Read the flatness as indecision, not stability. A hot core PCE and yields press higher and the rate-sensitive tape leaks again; a cool print and the chips get room to run. The reaction is the trade, not the number.
- The 10-year at 5.28% is the ceiling under everything. Yields pushed to a fresh multi-decade high Tuesday and stocks leaked for a second straight session because of it — this is a bond-market-led tape, full stop. A generational high in the benchmark yield is the weight on every rate-sensitive corner, and until it eases, the ceiling stays over the market. Watch the yield reaction to PCE more closely than any single stock: if the 10-year presses higher on the data, the whole tape feels it; if it eases, that’s the release valve the market has been waiting for.
- It’s month-end and quarter-end, and that adds noise to the tape. The final trading day of September brings rebalancing flows that can distort price into the close — funds adjusting allocations, window-dressing, and index rebalances that move names for mechanical reasons, not fundamental ones. Don’t confuse a rebalancing-driven move for a real read on demand. The clean signal today is the PCE reaction and the yield response; the late-day flows are noise to trade around, not a trend to chase.
Stock-Specific
- The chips are the bounce tell, and Micron (MU) is the marquee name — it reports after Wednesday’s close as the key read on AI-driven memory demand. Nvidia (NVDA) and Micron are steady premarket, holding the Nasdaq’s slim edge into the data. When the highest-beta group holds up into a hot rate backdrop, treat it as a read on risk appetite, not proof the pressure is gone. Micron’s report tonight is the real catalyst — watch the guidance on memory pricing and AI demand more than the headline number.
- Capricor Therapeutics (CAPR) is the standout premarket gainer, surging on positive clinical updates — a reminder that stock-specific catalysts still cut through a macro-frozen tape. It’s a high-volatility, news-driven move, not a macro signal, so treat it as its own setup: news-driven spikes give back fast when the catalyst is fully priced. The lesson is separation — on a day the whole market is waiting on PCE, the clean single-name opportunities are the ones with their own catalyst, traded on their own levels.
- The downside single-names are company-specific, not macro. Mobileye (MBLY) is under pressure on its 2026 growth outlook and a management transition alongside analyst downgrades, WPP is lower on a CFO departure and its ex-dividend date, and Trip.com (TCOM) slid on a Q2 loss driven by an antitrust penalty. None of these are tape-movers — they’re clean examples of idiosyncratic risk. On a macro-frozen morning, that’s the point: know whether you’re trading the market’s story or a single company’s story, because they need different playbooks.
Global and Macro
- Oil is the quiet positive at the margin. WTI down about 3.5% Tuesday near $89 as the war premium deflates is easing the inflation-and-yield loop that’s been pressuring the tape — cooling crude helps take a little heat off the 10-year. But it’s a supporting actor today, not the driver. If the geopolitical story flips and crude re-spikes, it feeds straight back into the inflation narrative the market is trading through PCE. Track oil as a secondary tell on the yield story, not as the main event this morning.
- The macro backdrop is a bond market in control into the single most important inflation print of the month. The 10-year at a fresh multi-decade high, PCE at 8:30 as the Fed’s preferred gauge, and month-end flows layered on top — that’s the tension. The market is pricing higher-for-longer and waiting to see if the data confirms it. Everything hinges on the yield reaction: PCE doesn’t just move stocks directly, it moves the 10-year, and the 10-year moves everything. That’s the chain to watch all session.
TECHNICAL ANALYSIS
S&P 500 Key Levels
- The S&P closed Tuesday at 7,670.84 and futures point to a flat open right on that axis, so the first battle is the 7,700 reclaim. That round level just above the close is where the tape has to prove buyers want control once PCE crosses — reclaim it and hold, and the two-day leak stops and a base forms. Push through toward 7,743 and the recent damage is undone. Don’t chase into the print; let cash react to the data and prove it can take and hold 7,700 before you trust the long side.
- First support is 7,640 — the shelf that’s kept the two-session leak from accelerating. Lose 7,640 on a hot PCE with the 10-year pressing higher, and the tape opens toward 7,600 and the selloff extends. Above, 7,700 is the reclaim and 7,743 is the level that undoes the recent damage. Mark 7,700 above and 7,640 below — inside is chop and indecision, outside is the real signal on whether the PCE reaction favors buyers or the yield ceiling wins again.
Sector and Sentiment
- The leadership read this morning is chips holding a slim edge while the broad tape stays soft — a narrow, defensive kind of leadership, not a broad risk-on bid. Nvidia and Micron holding up says money is hiding in quality growth into the data, not chasing risk. For the tape to build after PCE, you want participation to widen beyond the megacap names — the Dow joining rather than lagging. Until then, trade it tactically off the levels; a narrow bounce led by a thin group isn’t a trend you assume will hold.
- The VIX near 16 and ticking up says the options market is pricing a little more caution into the data — low absolute, rising direction. That’s the honest setup: not fear, but not complacency either, ahead of a print that can reprice the rate path in seconds. Practically: respect that a hot PCE can wake volatility fast, keep the 10-year on your screen as the real driver, and let SPX prove its levels on the actual reaction to the data before you trust either side of the tape.
TODAY’S ECONOMIC CALENDAR
Key Releases (ET)
- The morning’s weight lands at 8:30 AM ET: the August PCE price index, the Fed’s preferred inflation gauge, alongside personal income and spending. Core PCE — stripping food and energy — is the single number Fed officials reference most when they judge whether inflation is on track. With the 10-year at 5.28%, this print is a direct referendum on whether yields are justified. A hot core read presses the bond market higher and the rate-sensitive tape leaks; a cool print eases yields and gives the market its first real breathing room in days.
- Watch the chain, not just the number. PCE moves the 10-year, and the 10-year moves the tape — so the cleanest read this morning is the yield reaction, not the headline print. It’s also month-end and quarter-end, so expect rebalancing flows to add noise into the close on top of the data. Let the rates reaction guide the trade: if the yield presses higher after PCE, the rate-sensitive laggards leak again; if it eases, the chips and the broad tape get room to build a bounce that can actually hold.
Earnings Today
- Micron (MU) headlines the tape, reporting after Wednesday’s close as the marquee read on AI-driven memory demand. Before the bell, Conagra Brands (CAG), Jabil (JBL), FactSet (FDS) and Cal-Maine Foods (CALM) report — a mix of consumer staples, electronics manufacturing and financial data. Conagra is the useful macro read of the group, a window into how the household is holding up with rates this high. But the name that matters most is Micron tonight: its guidance on memory pricing and AI demand is a real catalyst for the whole chip complex into Thursday.
- Treat earnings as texture and trade the macro today. The moves that matter this morning are macro-driven — the tape is frozen on PCE and hostage to the 10-year, and the single-name earnings before the bell are secondary. Where they add value is as a check on demand: staples and consumer names tell you whether spending is holding up as the Fed keeps rates elevated. That’s the tension underneath the tape, and Micron’s report tonight is the release most likely to set the tone for the chip leaders into the back half of the week.
PREMARKET PLAYBOOK
Key Levels
- SPX 7,700 — the reclaim. The round level just above Tuesday’s 7,670 close, and the first thing the open has to earn back once PCE crosses. Reclaim it AND hold it with the chips leading and the two-day leak stops and a base forms, opening the door toward 7,743 and higher. But futures are dead flat into an inflation print, so don’t chase a gap toward 7,700 unless the yield reaction and breadth confirm it. Make price take and hold the level on real strength after the data before you trust the long side.
- SPX 7,670 — the axis. Tuesday’s close and the pivot the flat open sits right on. This is the ‘let it prove itself’ zone where a data-frozen tape tends to chop as the PCE number gets digested and the 10-year picks a direction. The real signal is which side SPX leaves 7,670 on once cash trades and the yield reaction sets in. Inside the range is noise; the move that matters is the one that follows the print. Patience beats prediction here.
- SPX 7,640 — the shelf that keeps the selloff contained. It’s held the two-session leak from accelerating. Lose it on a hot PCE with the 10-year pressing higher, and the tape opens toward 7,600 and the leak extends into a real leg down. Below 7,640 the market is rejecting any relief and the job flips to capital preservation. This is the number that separates a contained pullback from the start of the next move lower — mark it, and respect it if it goes.
Bull case: Core PCE comes in cool, the 10-year eases back off 5.28%, and the chips hold their bid through the print. SPX reclaims 7,700 and pushes toward 7,743, participation widens beyond the megacap names as the Dow joins, and the market gets its first real breathing room in days as the yield ceiling finally lifts. In this scenario the two-day leak was a bond-market scare into the data, month-end flows lean supportive, and the tape stabilizes with the chips leading into Micron’s report tonight and the back half of the week.
Bear case: Core PCE runs hot, the 10-year presses higher over 5.28%, and the rate-sensitive tape leaks again. SPX fails to reclaim 7,700, loses the 7,640 shelf, and opens toward 7,600 as the chips give back their edge and the Dow keeps lagging. A hot inflation print into a bond market already at generational-high yields is the hardest backdrop for stocks — it confirms higher-for-longer with no relief in sight. In this scenario month-end flows amplify the downside and the yield ceiling caps the market straight into Micron and Friday’s data.
Premarket Movers
Gainers
| NVDA | Nvidia | steady premarket as the chips hold the Nasdaq’s slim edge into PCE | Holding steady this morning as the megacap chip names carry the Nasdaq’s thin lead into the inflation print. Nvidia is the epicenter of the AI trade — when it holds up into a hot rate backdrop, it says money is hiding in quality growth, and when it rolls over, the tape has no leader. Treat it as the single best read on risk appetite through the PCE reaction, and keep it on the screen against the 10-year all session. |
| MU | Micron Technology | steady premarket ahead of its report after Wednesday’s close | Steady premarket as the marquee catalyst of the day — Micron reports after Wednesday’s close as the key read on AI-driven memory demand. It’s leading the chip complex’s slim edge into PCE, but the real move comes tonight on the guidance. Watch memory pricing and AI demand commentary more than the headline number: a strong read gives the chip leaders a foundation into Thursday, while soft guidance pulls the whole group’s leadership out from under the tape. |
| CAPR | Capricor Therapeutics | surging premarket on positive clinical updates | The standout single-name gainer this morning, surging on positive clinical updates — proof that stock-specific catalysts still cut through a macro-frozen tape. It’s a high-volatility, news-driven move on heavy volume, so trade it on its own levels, not as a macro signal: catalyst-driven spikes give back fast once the news is fully priced. On a day the whole market is waiting on PCE, this is the kind of clean, self-contained setup that trades independent of the yield story. |
Laggards
| MBLY | Mobileye Global | lower on its 2026 growth outlook and a management transition | Under pressure premarket on its 2026 growth prospects and a management transition, compounded by high short interest and recent analyst downgrades. This is idiosyncratic risk, not a macro signal — a company-specific story that has nothing to do with the PCE print driving the broad tape. It’s a clean reminder to separate the two: on a macro-frozen morning, know whether you’re trading the market’s story or a single company’s, because they demand different playbooks and different risk. |
| TCOM | Trip.com Group | fell on a Q2 loss driven by an antitrust penalty | Lower premarket after its Q2 report revealed a net loss driven by an antitrust penalty, with cautious revenue guidance dampening sentiment. Another clean case of single-name, company-specific risk moving independent of the macro tape. The move is about the penalty and the guidance, not the 10-year or PCE — so it trades on its own story. The lesson holds: on a day dominated by one macro print, the idiosyncratic names are their own setups, not reads on the broad market’s direction. |
Risks Into the Open
- Primary risk: trading the PCE number instead of the reaction. The instinct on an inflation print is to guess the direction and jump — that’s how you get caught on the whipsaw when the first move reverses. Futures are flat because the market itself won’t commit before the data; you shouldn’t either. Let SPX react to the print, watch the 10-year’s response, and require price to reclaim and hold 7,700 or lose 7,640 on real trade before you act. The reaction at the level is the signal — the number alone is noise.
- The 10-year at 5.28% is the ceiling risk for the whole tape. Yields at a fresh multi-decade high are the weight that’s had stocks leaking for two sessions, and PCE is a direct referendum on whether that level is justified. If the data leans hot and the 10-year presses higher, the rate-sensitive corners leak first and even the chip leaders can’t hold. The regime is elevated-and-rising rates in a bond-market-led tape — respect the ceiling, and watch the yield reaction as the real driver of every other move today.
- Event and flow risk are stacked into today. PCE at 8:30 can whip the 10-year and the tape in seconds, and it’s month-end and quarter-end, so rebalancing flows add mechanical noise into the close on top of the data. The VIX ticking up near 16 says the market is pricing a little more caution, which is the right instinct. The risk is treating the flat premarket as calm — it’s a frozen tape into a data point that can reprice the rate path, with month-end distortion layered on top. Trade the levels, not the noise.
Frequently Asked Questions
Where are S&P 500 futures trading ahead of the open?
Ahead of Wednesday, September 30, 2026, S&P 500 futures are at 7,670.84 (-0.17%), with the VIX near 15.91. The stock market today is steady, but only because everyone is standing still ahead of the one number that matters. Tuesday the tape leaked again — the Dow slipped 131.59 points, or 0.26%, to 51,349.92, the S&P 500 eased 0.17% to 7,670.84, and the Nasdaq Composite held up best, off just 0.09% to 26,797.54 — as the 10-year Treasury yield pushed to a fresh multi-decade high near 5.28%. That yield is the whole story. This morning futures are barely green — S&P 500 futures up about 0.05%, Nasdaq-100 futures leading at roughly +0.15%, Dow futures up about 0.10% — because the market is frozen ahead of the August PCE inflation report at 8:30 AM ET, the Fed’s preferred gauge. This is the print that either justifies yields at 5.28% or takes some pressure off. A hot core PCE and the 10-year presses higher and the rate-sensitive tape leaks again; a cool print and yields ease and the chips get room to run. Oil is helping at the margin — WTI eased about 3.5% Tuesday back near $89, taking a little heat off the inflation-and-yield loop. And it’s month-end and quarter-end, so rebalancing flows can distort the tape into the close. But none of that changes the setup: this is a market held hostage by the bond market into a single data point. Today is a lesson in patience — you don’t trade the PCE number, you trade how price reacts to it at your level. SPX 7,700 is the reclaim the open has to earn back, 7,640 is the shelf that keeps the selloff contained, and 7,600 is the downside if that shelf breaks. Micron reports after the close as the marquee AI read. No alignment, no trade.
What is the biggest catalyst for the market today?
The entire tape is frozen ahead of the August PCE inflation report at 8:30 AM ET. This is the Fed’s preferred gauge, and it’s the number that either justifies the 10-year at a fresh multi-decade high near 5.28% or takes some pressure off. Futures are dead flat — S&P +0.05%, Nasdaq-100 +0.15%, Dow +0.10% — because nobody wants to commit before the print. Read the flatness as indecision, not stability. A hot core PCE and yields press higher and the rate-sensitive tape leaks again; a cool print and the chips get room to run. The reaction is the trade, not the number.
What key levels should traders watch today?
SPX 7,700 — the reclaim. The round level just above Tuesday’s 7,670 close, and the first thing the open has to earn back once PCE crosses. Reclaim it AND hold it with the chips leading and the two-day leak stops and a base forms, opening the door toward 7,743 and higher. But futures are dead flat into an inflation print, so don’t chase a gap toward 7,700 unless the yield reaction and breadth confirm it. Make price take and hold the level on real strength after the data before you trust the long side. SPX 7,670 — the axis. Tuesday’s close and the pivot the flat open sits right on. This is the ‘let it prove itself’ zone where a data-frozen tape tends to chop as the PCE number gets digested and the 10-year picks a direction. The real signal is which side SPX leaves 7,670 on once cash trades and the yield reaction sets in. Inside the range is noise; the move that matters is the one that follows the print. Patience beats prediction here. SPX 7,640 — the shelf that keeps the selloff contained. It’s held the two-session leak from accelerating. Lose it on a hot PCE with the 10-year pressing higher, and the tape opens toward 7,600 and the leak extends into a real leg down. Below 7,640 the market is rejecting any relief and the job flips to capital preservation. This is the number that separates a contained pullback from the start of the next move lower — mark it, and respect it if it goes.
How does Meta Trading Club approach the market open?
We qualify every setup through the MTC Alignment Engine — bias, level, reaction, confirmation, execution, targets. No alignment, no trade. Learn the full process inside the MTC Incubator.
Trade with a system, not signals.
This is exactly how MTC members read the open — bias, level, reaction, confirmation, execution. If you want to learn to qualify your own A+ setups instead of chasing alerts, the MTC Incubator is mentorship and a repeatable process.
Apply for the Incubator → Learn moreSources: Yahoo Finance | CNBC | Benzinga | Investing.com | TheStreet – September 30, 2026 (8:15-8:45 AM ET window). For educational purposes only. Not financial advice.